High Yield Credit Spreads: Tracking OAS Defaults, Distress Ratios, and Macro Liquidity
An empirical market report decomposing US High Yield Option-Adjusted Spreads (OAS), credit rating tier dispersion across BB and CCC cohorts, corporate refinancing cliffs, and macro liquidity transmission channels.
Architecture of High Yield Credit Spreads: Option-Adjusted Spread (OAS) Mechanics
High yield credit spreads represent the primary real-time barometer of corporate credit risk and dollar funding stress across global capital markets. While equity indices often sustain elevated valuations on concentrated mega-cap earnings momentum, non-investment-grade corporate bond markets price balance-sheet solvency, refinancing capacity, and liquidity scarcity directly into yield differentials over risk-free United States Treasury securities. Institutional macro desks monitoring high yield credit spreads rely on the Option-Adjusted Spread (OAS) rather than simple nominal yield differences because over 75% of US high yield corporate debt contains embedded call provisions.
A corporate bond issued at par with a 7.50% coupon and an 8-year final maturity typically includes a 3-year non-call period, allowing the issuer to redeem the debt early if interest rates decline or credit quality improves. If a naïve model compares that bond's yield-to-maturity directly against an 8-year non-callable US Treasury note, the embedded call option distorts the true credit risk compensation. The Option-Adjusted Spread resolves this structural distortion by valuing the bond across an interest-rate lattice (such as a Black-Derman-Toy or Hull-White tree), stripping out the option value and isolating the pure credit and liquidity spread in basis points (bps).
Across the ICE BofA US High Yield Index universe—comprising over $1.35 trillion in below-investment-grade corporate debt rated BB1 through D—the headline OAS reflects the market-value-weighted credit premium demanded by institutional bondholders. Historically, across market cycles spanning 1997 to 2026, the long-term median US High Yield OAS sits near 465 bps, while the bottom decile of compressed liquidity regimes falls between 280 bps and 350 bps. When the index OAS breaches 600 bps, credit markets transition from benign carry harvesting into active default pricing.
Furthermore, institutional credit analysts evaluate OAS trajectories relative to real interest rates and nominal GDP growth expectations. When nominal economic growth runs near 5.0% to 6.0% while inflation expectations remain anchored around 2.5%, leveraged borrowers generate sufficient nominal top-line expansion to service 7.50% coupon obligations. Conversely, if nominal growth decelerates below 3.5% while real 10-year Treasury yields hold above 2.0%, credit spreads widen rapidly as corporate revenue growth fails to outpace debt service burdens.
Rating Tier Dispersion: Decomposing BB, Single-B, and CCC Distress Ratios
Monitoring the aggregate headline high yield index obscures critical risk migration occurring beneath the surface. The non-investment-grade universe is stratified into three distinct credit quality cohorts: BB (the highest tier of high yield, accounting for roughly 52% of index market value), Single-B (accounting for approximately 37%), and CCC-and-lower (comprising roughly 11% of the index). Because pension funds and insurance mandates often restrict holdings to BB and higher-tier Single-B paper, liquidity stress manifests first in the CCC tier months before headline spreads widen.
| Credit Rating Tier | Typical Index Share | Calm Regime OAS | Stress Regime OAS | Historical 5-Yr Default Rate |
|---|---|---|---|---|
| BB Cohort (BB1–BB3) | 52.0% | 175–240 bps | 450–650 bps | 4.2% |
| Single-B Cohort (B1–B3) | 37.0% | 310–410 bps | 680–950 bps | 14.8% |
| CCC & Lower Cohort | 11.0% | 720–880 bps | 1,350–2,200 bps | 38.5% |
| Aggregate HY Index | 100.0% | 280–350 bps | 700–1,100 bps | 12.4% |
Quantitative credit desks track the CCC-minus-BB spread differential (often termed the quality compression ratio) alongside the market-wide distress ratio—defined as the percentage of high yield bond issues trading at an OAS above 1,000 bps. In benign liquidity cycles, the distress ratio hovers between 3.5% and 6.0%. When the distress ratio breaks above 12.0% while BB spreads remain anchored near 220 bps, credit markets are signaling acute idiosyncratic solvency pressure concentrated in over-leveraged capital structures, frequently foreshadowing a broader wave of Chapter 11 filings and distressed debt exchanges within 6 to 12 months.
Rating migration between investment-grade and high-yield universes—known as Fallen Angels (downgrades from BBB- to BB+) and Rising Stars (upgrades from BB+ to BBB-)—further amplifies spread dispersion. Because institutional investment-grade mandates are forced to liquidate bonds downgraded into high yield within 30 to 90 days of a rating action, Fallen Angel waves temporarily inject $40 billion to $150 billion of forced supply into the BB cohort. During the March 2020 downgrade wave, over $140 billion in former investment-grade energy and automotive debt entered the high yield index, initially widening BB spreads by 200 bps before crossover buyers absorbed the supply at steep discounts.
Mathematical Decomposition: Expected Default Loss, Recovery Rates, and Liquidity Premia
A rigorous valuation of high yield credit spreads requires decomposing the quoted OAS into three distinct economic components: expected default loss, an illiquidity risk premium, and a systemic risk aversion premium. In reduced-form credit intensity models, the annualized expected credit loss equals the conditional hazard rate of default multiplied by loss given default (1 minus the expected recovery rate):
Using the historical senior unsecured corporate recovery baseline of 40.0% (meaning a 60.0% loss given default), an aggregate High Yield OAS of 360 bps implies a breakeven annual default rate of 6.00% (0.0360 / 0.60). However, empirical default cycles over the past three decades show an average realized annual default rate near 3.20% during non-recessionary expansions. The persistent gap between the 6.00% breakeven default rate and the 3.20% realized baseline—amounting to roughly 168 bps of excess yield—reflects the structural credit risk premium compensating bondholders for illiquidity and left-tail correlation shocks during recessions.
Crucially, recovery rates are not static constants; they are strongly negatively correlated with default rates. During benign periods when annual defaults sit near 1.50%, senior unsecured recoveries average 48.0% to 52.0%. Conversely, during systemic downturns when defaults surge past 8.00% to 10.00%, asset liquidation values collapse and recoveries drop toward 22.0% to 28.0%. Lower realized recoveries amplify credit losses geometrically, explaining why CCC spreads expand non-linearly once default cycles begin.
Empirical credit desks also adjust OAS models for convexity and callability asymmetry. When high yield spreads tighten below 320 bps and benchmark Treasury yields decline, high-coupon bonds trade near or above their call prices, exhibiting negative convexity. In this regime, upside price appreciation is capped by the issuer call schedule, while downside drawdown risk remains uncapped if spreads widen back toward 550 bps. Quantifying option-adjusted convexity ensures portfolio managers do not confuse high current coupon carry with symmetric total-return potential.
The Corporate Refinancing Wall: Maturity Cliffs, Interest Coverage, and Floating-Rate Debt
Corporate credit defaults rarely materialize solely because of operational revenue declines; they accelerate when elevated benchmark interest rates collide with near-term debt maturity cliffs. Between 2020 and 2021, non-investment-grade corporate issuers locked in historically low fixed coupons averaging 4.50% to 5.25%. As those 5-year and 7-year notes approach maturity windows across 2026 through 2028, issuers face refinancing coupons averaging 7.75% to 9.50% depending on rating tier.
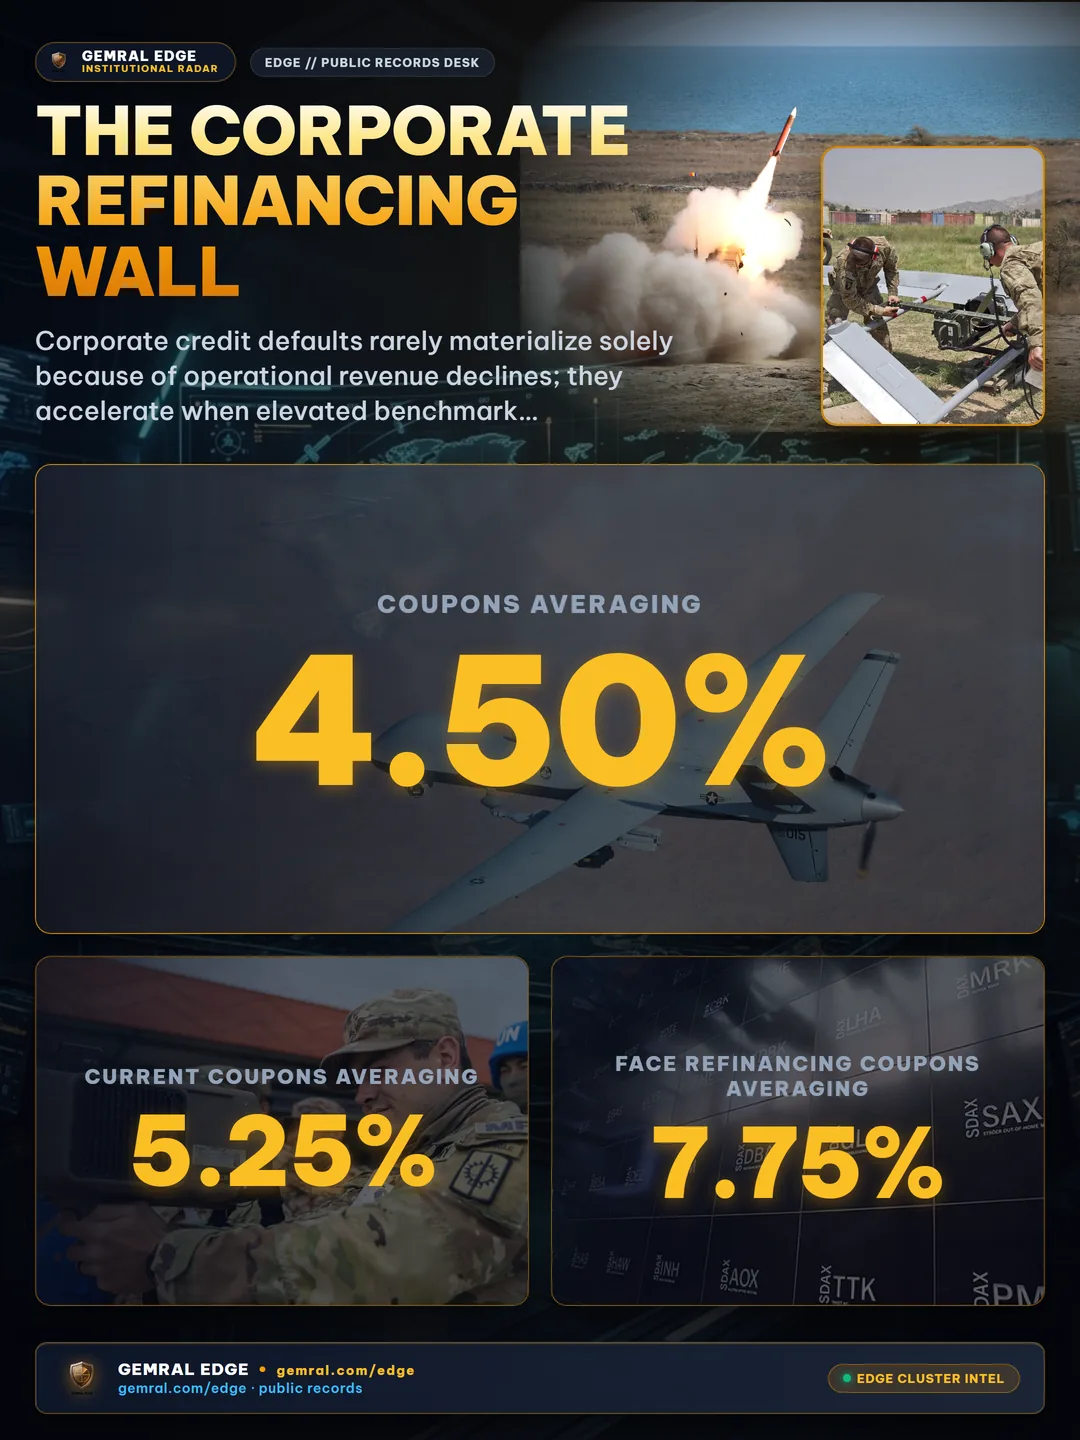
This 300 to 425 bps upward reset in coupon costs compresses corporate interest coverage ratios (EBITDA divided by annual cash interest expense). For a typical Single-B issuer carrying 5.5x Net Debt-to-EBITDA leverage, a 350 bps increase in weighted-average borrowing cost reduces free cash flow conversion by 25% to 40%. When interest coverage falls below 1.5x, fixed-income underwriters demand steep original issue discounts (OID) or tighter financial covenants, locking out marginal borrowers from primary bond markets.
Furthermore, private-equity-backed borrowers that shifted heavily into floating-rate syndicated leveraged loans and private credit facilities experience immediate cash-flow pressure without waiting for bond maturities. Because floating-rate loans reset quarterly off Secured Overnight Financing Rate (SOFR) benchmarks plus 400 to 550 bps credit margins, sustained policy rates above 4.00% push total interest burdens near 8.50% to 9.75%, driving a higher incidence of Liability Management Exercises (LMEs) and distressed exchanges among lower-tier leveraged borrowers.
Sector-level maturity walls further differentiate idiosyncratic refinancing risk across the high yield index. Capital-intensive sectors such as telecommunications, media, and leveraged healthcare face concentrated 2027–2028 maturity schedules representing over 38% of their total outstanding debt, whereas energy exploration and production issuers reduced net leverage from 2.8x in 2016 to under 1.2x by 2025–2026. Evaluating refinancing walls at the sub-sector level explains why aggregate index spreads can remain compressed even while stressed media and telecom issuers trade at yields exceeding 14.0% to 18.0%.
Macro Liquidity Transmission: Central Bank Reserves, Treasury Issuance, and Credit Compression
High yield credit spreads are highly sensitive to aggregate dollar liquidity conditions governed by Federal Reserve balance-sheet operations and US Treasury cash management. Institutional macro models track Net Liquidity—defined as the Federal Reserve's total assets minus the Treasury General Account (TGA) balance and the Overnight Reverse Repurchase (ON RRP) facility—to gauge the supply of bank reserves available to absorb corporate credit issuance.
When the ON RRP facility drains rapidly into Treasury bills while bank reserves remain abundant above $3.20 trillion, institutional cash searches for yield further out the risk spectrum, compressing high yield OAS even amid tight monetary policy rates. Conversely, when rapid TGA rebuilds of $300 billion to $500 billion coincide with Quantitative Tightening (QT) runoff of $25 billion to $60 billion per month, commercial bank reserves tighten. Primary dealers respond by reducing corporate bond inventory capacity on their balance sheets, causing bid-ask spreads to widen by 15 to 40 bps and amplifying spread volatility during risk-off episodes.
Detailed telemetry on how sovereign funding dynamics interact with institutional leverage is documented in our study on the Treasury basis trade and repo liquidity constraints, where dealer balance-sheet capacity dictates both sovereign and corporate credit clearing efficiency.
Beyond domestic Federal Reserve reserve balances, global cross-currency hedging costs shape foreign institutional demand for US high yield credit. European and Japanese life insurers account for roughly 15% to 20% of marginal demand in US corporate bond markets; when 3-month FX hedging costs rise above 250 bps annually, foreign hedged yields turn negative relative to domestic sovereign bonds, forcing overseas buyers to retreat and leaving domestic credit funds to absorb primary issuance.
Cash Bonds vs Synthetic Credit: Comparing High Yield OAS, Leveraged Loans, and CDX HY
Modern institutional credit markets trade across three parallel instruments: cash high yield corporate bonds, syndicated leveraged loans (packaged into Collateralized Loan Obligations or CLOs), and synthetic credit default swap indices (specifically Markit CDX.NA.HY). Although all three price corporate default risk, their structural mechanics create persistent basis divergences during market stress.
- 01. Fixed-Rate Cash Bonds: Carry both interest-rate duration (typically 3.2 to 4.1 years) and credit spread duration. When Treasury yields spike 75 bps in a single month, cash high yield bond prices drop on duration sensitivity even if OAS remains unchanged.
- 02. Floating-Rate Leveraged Loans: Carry near-zero interest-rate duration (0.25 years) and senior secured priority in the capital structure, historically yielding 62% to 68% recovery rates compared to 40.0% for unsecured bonds—though cov-lite documentation has compressed recent recoveries toward 45% to 50%.
- 03. CDX.NA.HY Synthetic Index: Tracks an equally weighted basket of 100 liquid North American high yield issuers via standardized 5-year credit default swaps. Because CDX HY settles electronically with deep dealer liquidity ($10 billion+ daily turnover), macro hedge funds short CDX HY to hedge credit books within seconds, frequently causing synthetic spreads to lead cash bond OAS widening by 2 to 5 trading sessions.
Collateralized Loan Obligation (CLO) formation acts as the primary structural buyer in the syndicated leveraged loan market, absorbing roughly 60% to 65% of institutional loan supply. When CLO AAA liability spreads widen from 115 bps to 185 bps over SOFR, CLO equity arbitrage collapses and new CLO warehouse creation slows sharply. Because leveraged loans lack a natural retail buyer base outside mutual funds, a freeze in CLO issuance immediately forces secondary loan prices lower, spilling over into high yield bond sentiment within 2 to 3 weeks.
Credit Market Microstructure: High Yield ETF Creation-Redemption and Bid-Ask Fragility
The growth of passive fixed-income Exchange-Traded Funds (ETFs) such as HYG and JNK has transformed secondary market liquidity in corporate debt. Cash corporate bonds trade over-the-counter (OTC) in fragmented dealer networks, where an individual bond issue might trade only 2 to 4 times per week. By contrast, high yield ETFs trade continuously on lit equity exchanges with penny-wide bid-ask spreads, creating a liquidity transformation mismatch between the ETF share and its underlying bond basket.
During acute risk-off liquidations, retail and institutional sellers dump ETF shares instantaneously, pushing the ETF market price to a discount of -1.50% to -4.50% below Net Asset Value (NAV). Authorized Participants (APs)—typically major broker-dealers—arbitrage this discount by buying discounted ETF shares in the open market, redeeming them in-kind for custom baskets of underlying corporate bonds, and liquidating or hedging those bonds in the OTC market. While this creation-redemption mechanism acts as a shock absorber in mild pullbacks, during severe liquidity freezes APs widen bond bids sharply, transmitting ETF outflows directly into wider cash OAS quotes across the entire high yield complex.
Secondary market liquidity has also evolved with the rise of portfolio trading protocols, which now account for over 20% of institutional corporate bond turnover compared to under 3% in 2018. Portfolio trading allows asset managers to execute baskets of 50 to 250 individual high yield CUSIPs in a single all-or-nothing electronic inquiry with major dealers, reducing transaction costs in calm markets by 8 to 15 bps. However, during extreme volatility regimes, dealers withdraw balance-sheet risk limits from portfolio trading desks first, causing liquidity to evaporate simultaneously across broad multi-sector baskets.
Historical Crisis Regimes: Comparing the 2008 GFC, 2016 Energy Bust, 2020 Freeze, and 2022 Tightening
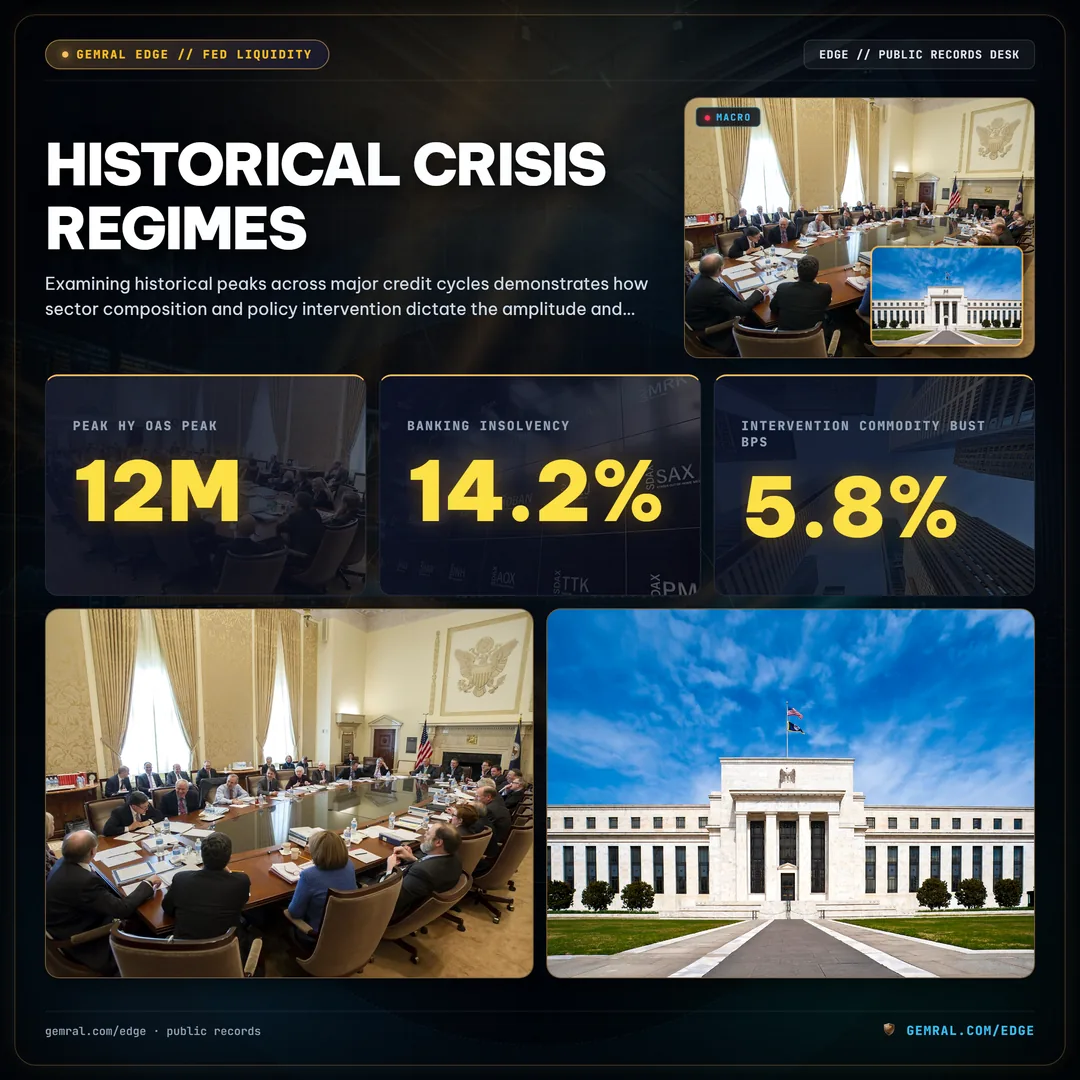
Examining historical peaks across major credit cycles demonstrates how sector composition and policy intervention dictate the amplitude and duration of spread widening. Not every spread shock triggers a systemic banking crisis; sector-specific supply shocks behave fundamentally differently from economy-wide liquidity freezes.
| Historical Credit Regime | Peak HY OAS | Peak 12M Default Rate | Primary Catalyst & Resolution |
|---|---|---|---|
| 2008–2009 Global Financial Crisis | 1,988 bps | 14.2% | Banking insolvency, wholesale funding freeze, QE1 intervention |
| 2015–2016 Commodity Bust | 887 bps | 5.8% | WTI crude drop below $30/bbl, Energy HY sector defaults |
| March 2020 Pandemic Crash | 1,087 bps | 6.5% | Global shutdown, Fed SMCCF corporate bond facility |
| 2022–2023 Rate Tightening Cycle | 599 bps | 3.4% | 525 bps Fed hike cycle, higher-quality BB index composition |
Notice the structural shift between 2008 and 2022: during the 2022–2023 monetary tightening cycle, despite 525 bps of cumulative Federal Reserve rate hikes, US High Yield OAS peaked at just 599 bps in July 2022. Two structural forces capped spread expansion: first, the BB share of the index had grown from 36% in 2007 to over 52% by 2022 (improving aggregate credit quality); second, corporate borrowers had extended debt maturities during 2020–2021, delaying immediate refinancing stress by 3 to 4 years.
The March 2020 intervention by the Federal Reserve—specifically the establishment of the Secondary Market Corporate Credit Facility (SMCCF)—marked a structural turning point in modern credit market psychology. Although the facility ultimately purchased less than $15 billion in corporate bonds and credit ETFs against an authorized capacity of $750 billion, the announcement alone compressed US High Yield OAS from 1,087 bps down toward 520 bps within 10 weeks by eliminating existential primary-market rollover risk for BB and Fallen Angel issuers.
Institutional Risk Architecture: Spread Duration (SDV01), Margin Haircuts, and Distress Triggers
Managing institutional credit portfolios requires separating interest-rate risk (Effective Duration / DV01) from credit spread sensitivity (Spread Duration / SDV01). A 5-year high yield bond portfolio with a spread duration of 3.8 years loses approximately 3.80% of market value for every 100 bps widening in OAS, independent of Treasury rate movements.
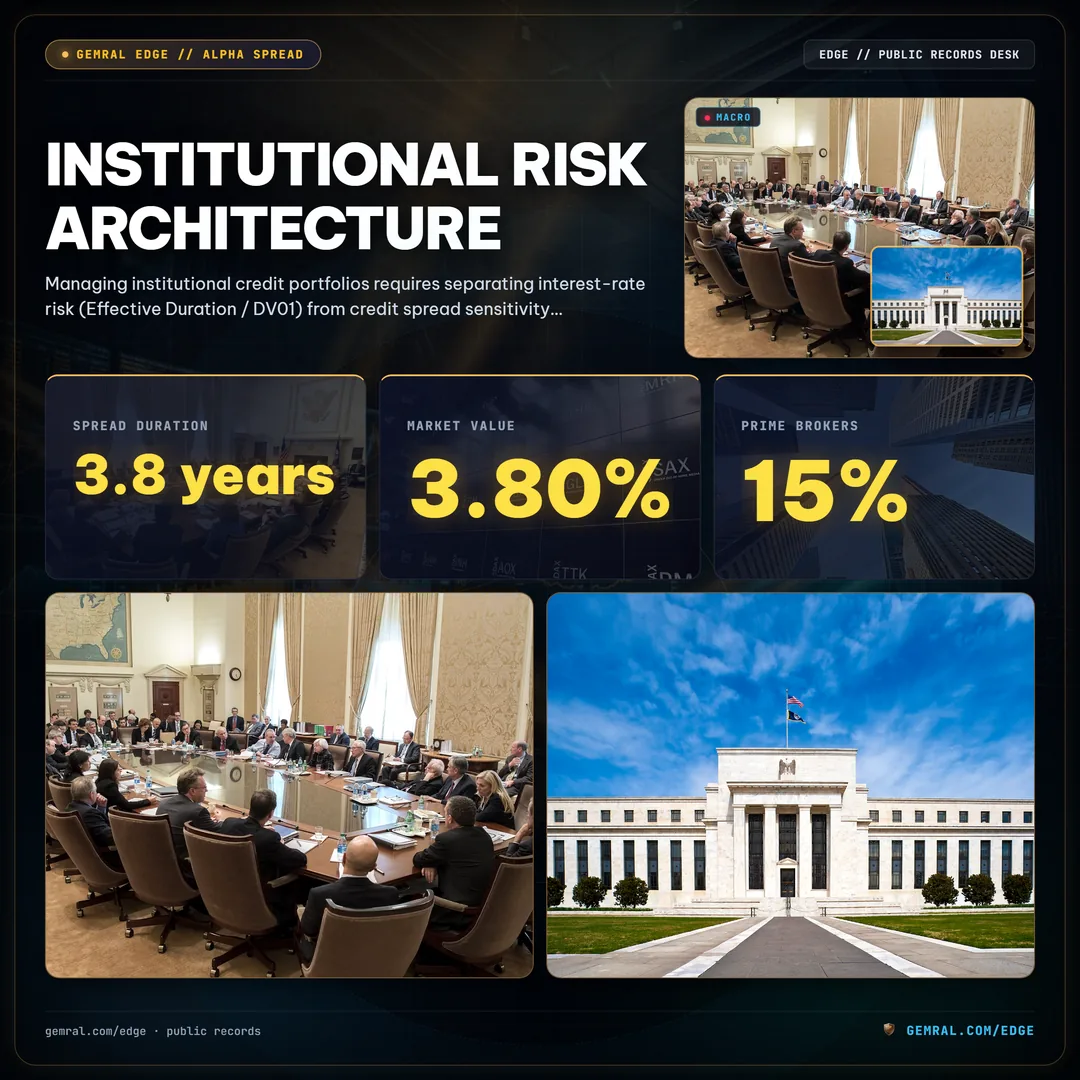
Leveraged credit hedge funds amplify this sensitivity through prime brokerage repo financing. Under normal conditions, prime brokers apply a 15% to 20% haircut on BB corporate bonds and a 25% to 35% haircut on Single-B debt. During credit dislocations when OAS crosses 700 bps, prime brokers escalate haircuts to 45% to 65% and mark collateral to depressed bid quotes rather than mid-market prices. Funds running 3x to 4x gross leverage face forced margin calls, triggering correlated deleveraging across credit, convertible bonds, and equity volatility markets.
To prevent forced liquidation, multi-strategy desks enforce systematic de-risking triggers tied to three observable indicators: a 75 bps weekly widening in CDX HY, a CCC-to-BB spread ratio exceeding 4.2x, and a VIX futures curve inversion exceeding +2.0 points on the front-month M1-M2 calendar spread.
At the single-name credit desk level, risk managers complement index OAS telemetry with issuer-specific cash-flow stress tests and covenant quality scoring. Weakened maintenance covenants in post-2021 debt indentures permit distressed borrowers to execute non-pro-rata uptiering exchanges and drop-down subsidiary transfers, shifting collateral away from legacy senior lenders. Incorporating covenant protection scores alongside market-implied OAS prevents credit portfolios from suffering unexpected recovery haircuts during restructuring cycles.
Cross-Asset Telemetry: Linking High Yield Spreads to Equity Volatility and Federal Outlays
In a unified macro research framework, high yield credit spreads operate alongside equity options volatility and real-economy federal capital flows. As demonstrated in our analysis of the VIX term structure and volatility arbitrage dynamics, equity implied volatility and corporate credit OAS share a deep structural equivalence under Merton's structural credit model—both price the probability that corporate enterprise value falls below total debt liabilities.
Simultaneously, sector-level credit resilience increasingly depends on non-cyclical government procurement pipelines. Tracking how high-leverage defense, aerospace, and infrastructure contractors secure multi-year federal awards—documented in our research on point-in-time government contracts databases and corporate lobbying spending velocity—helps credit analysts distinguish structurally supported balance sheets from issuers exposed to private consumer cyclicality. Combining macro OAS regime signals with bottom-up federal cash-flow visibility creates a comprehensive framework for navigating credit cycles.
For live macro procurement and contract-backed issuer telemetry, review our recent federal defense contract award breakdown ($2.409 billion DoD obligation for FLR).
In practice, systematic macro portfolios construct composite credit regime scores by weighting daily US High Yield OAS levels (40% weight), the 20-day rate-of-change in the CCC-to-BB tier ratio (35% weight), and weekly CDX HY synthetic basis divergences (25% weight). When all three telemetry series flash synchronized tightening alerts, macro desks reduce cyclical equity beta and rotate capital toward short-duration sovereign bills and contract-backed defense or infrastructure issuers insulated from private refinancing cycles.
Frequently asked questions
What is the Option-Adjusted Spread (OAS) in high yield credit spreads?
The Option-Adjusted Spread (OAS) adjusts the nominal yield spread between a corporate bond and the US Treasury curve to remove the value of embedded call or put options. Measured in basis points (bps), OAS allows institutional analysts to compare callable high yield corporate debt uniformly against benchmark sovereign yields.
What levels of high yield credit spreads indicate normal liquidity vs systemic distress?
Historically, tight liquidity regimes see US High Yield OAS trade between 280 bps and 350 bps. Neutral or mid-cycle conditions range from 380 bps to 480 bps, whereas crossing 600 bps to 800 bps signals acute credit tightening and corporate refinancing stress. During major liquidity crises (2008 and 2020), OAS spiked above 1,000 bps to 1,900 bps.
How does the CCC-to-BB spread tier ratio predict corporate defaults?
Decomposition by credit rating tier reveals early risk migration: BB-rated debt often remains anchored near 180 to 250 bps while CCC-rated distressed debt widens past 850 to 1,200 bps. Expanding dispersion between CCC and BB tiers indicates that credit markets are pricing idiosyncratic default risk before broad equity indices reprice.
How do high yield credit spreads interact with Fed net liquidity and the VIX term structure?
High yield credit spreads respond directly to bank reserve drainage, Treasury General Account (TGA) rebuilding, and reverse repo facility shifts. Widening OAS frequently coincides with VIX futures curve inversions and rising Treasury volatility as leveraged credit funds face prime brokerage margin haircuts.