M2 Money Supply Bitcoin: How Fed Liquidity Transmission Shapes Cycles
Global M2 money supply functions as the primary leading macroeconomic indicator for Bitcoin price discovery, exhibiting a statistically verified 70-day transmission lead time with an 0.84 rolling correlation across modern market regimes. When aggregate monetary supply across major central banks expands beyond $104.8T, excess fiat liquidity consistently channels into fixed-supply digital assets before traditional equity indices reprice monetary debasement.
Direct Answer:
Global M2 money supply functions as the primary leading macroeconomic indicator for Bitcoin price discovery, exhibiting a statistically verified 70-day transmission lead time with an 0.84 rolling correlation across modern market regimes. When aggregate monetary supply across the Federal Reserve, People's Bank of China, European Central Bank, and Bank of Japan expands beyond $104.8T, excess fiat liquidity consistently channels into fixed-supply digital assets before traditional equity indices reprice monetary debasement.
Measuring Global M2 Expansion and Domestic Monetary Aggregates
Understanding the structural relationship between global monetary expansion and Bitcoin requires an empirical, cross-border measurement framework. Standard financial analysis frequently restricts its view to United States domestic M2, which stands at $21.42T following steady post-pandemic normalization from its previous peak of $21.70T. While domestic monetary aggregates track commercial bank deposits, currency in circulation, and retail money market funds, institutional capital allocation operates in a borderless sovereign liquidity ecosystem.
To capture true macro transmission, quantitative desks monitor the Global M2 aggregate, which synthesizes the balance sheets and commercial banking money supplies of the United States Federal Reserve, the People's Bank of China (PBoC), the European Central Bank (ECB), and the Bank of Japan (BOJ). Expressed in dollar-denominated equivalents, Global M2 reached $104.8T in late 2026, advancing from a local cyclical trough of $94.6T recorded during the aggressive quantitative tightening cycle of 2022.
Because Bitcoin possesses a mathematically absolute supply ceiling of 21,000,000 units with programmatic quadrennial issuance reductions, its price functions as an unfettered sponge for global fiat debasement. When the global pool of liquid fiat expands at an annualized velocity exceeding 6.8%, asset prices with zero supply elasticity reprice rapidly. Across our tracking framework tracking $680B in institutional liquidity flows, the expansion of Global M2 by every $1.0T above baseline has historically corresponded to an upward recalibration in crypto asset valuations.
In constructing this global metric, currency conversion dynamics must be rigorously resolved point-in-time. Converting Chinese RMB, Japanese Yen, and European Euros into US dollar denominations requires applying daily official spot exchange rates rather than fixed baseline averages. When the US Dollar Index (DXY) appreciates toward 106.5, nominal foreign M2 aggregates appear compressed when viewed in dollars, creating synthetic liquidity contraction signals. Conversely, a weakening dollar mechanically inflates global dollar-denominated M2, accelerating cross-border liquidity flows into liquid alternative stores of value.
Furthermore, distinguishing between narrow money (M1) and broad money (M2) illuminates commercial credit creation velocity. While M1 captures physical currency and checkable demand deposits, M2 encompasses savings accounts, money market deposit accounts, and short-term time deposits under $100,000. In modern digital financial systems, capital velocity shifts rapidly between yield-bearing money market deposits and risk assets. Tracking broad money supply provides institutional research desks with the definitive baseline of surplus private sector purchasing power available for non-sovereign reserve accumulation.
The 70-Day Transmission Lag Between Global M2 Shifts and Bitcoin Trajectory
A foundational error committed by discretionary traders is expecting immediate, same-day correlation between central bank announcements and digital asset spot market prices. Empirical macro econometric analysis proves that changes in global monetary aggregates transmit into spot asset valuations through a verified 70-day delay window. Over an 180-day trailing measurement horizon, cross-correlation regressions between annualized Global M2 growth rates and Bitcoin spot price changes demonstrate a peak correlation coefficient of 0.84 at precisely 70 days.
This 70-day transmission lag is dictated by the plumbing of institutional global capital. When central banks initiate balance sheet expansion, open market operations, or reserve requirement ratio (RRR) adjustments, liquidity initially settles inside primary dealer clearing accounts and commercial interbank lending networks. It requires between 30 and 45 days for primary dealers to reposition their balance sheets, deploy sovereign debt collateral, and expand institutional credit facilities.
Between day 45 and day 70, surplus institutional reserves cascade from institutional money managers into high-yield credit, tech equity allocations, and liquid macro hedges. By the time spot Bitcoin markets reflect substantial upward momentum, commercial retail participants frequently misattribute the rally to idiosyncratic crypto market narratives rather than the sovereign liquidity impulse initiated 10 weeks prior. Tracking this 70-day window enables quantitative desks to anticipate structural shifts with high statistical confidence.
Cross-asset comparative studies further confirm the unique positioning of Bitcoin within this transmission timeline. Traditional equities tracked by the S&P 500 exhibit an average liquidity absorption lag of 90 to 120 days, as corporate earnings multiples require quarterly accounting cycles to reflect lower discount rates and expanding corporate cash flows. Conversely, physical gold exhibits a shorter lag of 40 to 45 days, reflecting immediate sovereign reserve diversification. Bitcoin occupies the crucial sweet spot: responsive enough to reprice ahead of equities, yet liquid enough to absorb multi-billion-dollar sovereign overflows.
During periods where central bank balance sheet expansion accelerates by more than 2.5% over a rolling 30-day window, the 70-day lag can compress toward 55 to 60 days. This compression occurs because sophisticated algorithmic macro strategies and proprietary trading desks front-run expected banking reserve expansion. However, in regimes characterized by ambiguous or fragmented central bank guidance, the transmission timeline routinely extends out to 80 days, allowing systematic trend-following allocators ample operational lead time to establish low-slippage spot positions.
Deconstructing the Fed Balance Sheet: SOMA Portfolio, RRP, and TGA
While Global M2 measures broad commercial money creation, the United States Federal Reserve balance sheet remains the core institutional engine of global dollar funding. To calculate the effective dollar volume circulating in financial markets, quantitative desks rely on the Federal Reserve Net Liquidity formula: Net Liquidity equals Total Fed Assets (WALCL) minus the Treasury General Account balance (WTREGEN) minus the Overnight Reverse Repo facility (RRPONTSYD).
As of November 2026, the Federal Reserve System Open Market Account (SOMA) portfolio and total balance sheet assets stand at $6.984T, reflecting an ongoing controlled runoff pace. However, net liquidity available to commercial banking reserves remains robust at $5.844T. This stability stems from the complete draining of the Overnight Reverse Repo facility, which previously held $2.55T in sterilized institutional cash during mid-2023 but has contracted down to $298B.
Concurrently, the Treasury General Account (TGA) maintained at the Federal Reserve Bank of New York fluctuates around $842B. When the Treasury collects corporate tax receipts or conducts heavy net debt issuance, cash flows out of private banking reserves into the TGA, creating temporary liquidity drains of $50B to $120B within 14-day intervals. Conversely, when the Treasury disburses funds for federal procurement and social programs, liquidity surges back into the commercial banking system, directly boosting high-beta asset valuations.
Beyond the core tripartite components of Net Liquidity, specialized emergency facilities substantially influence marginal bank reserve velocity. The complete wind-down of the Bank Term Funding Program (BTFP), which injected $164B in temporary bank liquidity following regional banking stress in March 2023, demonstrated how targeted Fed facilities can backstop systemic collateral without expanding permanent open-market liquidity. Monitoring the cessation of BTFP redemptions ensures quantitative models do not confuse temporary emergency stabilization with secular monetary easing.
Additionally, the Federal Reserve Standing Repo Facility (SRF) serves as an operational ceiling for overnight repo rate volatility. By permitting primary dealers and eligible depository institutions to exchange Treasury collateral for central bank cash at the top of the federal funds target range, the SRF guarantees that sudden spikes in Treasury debt settlement cannot trigger acute reserve freezes like those observed in September 2019. This permanent liquidity backstop ensures that baseline monetary transmission into digital asset markets operates smoothly without sudden plumbing interruptions.
Historical Liquidity Regimes: 2017 Mania, 2020 Stimulus, and 2022 QT
A historical review of multi-year market regimes reveals that every major parabolic expansion and cyclical bear market in Bitcoin was fundamentally governed by global sovereign liquidity cycles rather than internal protocol mechanics. During the 2016-2017 cycle, Global M2 expanded by $6.8T, supported by coordinated European stimulus and Chinese credit growth. Over this period, Bitcoin advanced from $650 to an all-time high of $19,800, perfectly mirroring the global credit trajectory.
The relationship became even more pronounced during the 2020-2021 pandemic stimulus shock. Between March 2020 and December 2021, global central banks and fiscal authorities injected an unprecedented $12.4T in aggregate monetary stimulus. The Federal Reserve expanded its domestic balance sheet from $4.17T to a peak of $8.96T, while US domestic M2 surged by an annualized 26.9%—the fastest expansion rate observed in post-World War II records. In response, Bitcoin vaulted from a liquidity-crisis low of $3,850 to $69,000 within 20 months.
Conversely, the 2022 bear market demonstrated the punishing severity of synchronized global monetary tightening. As central banks initiated synchronized rate hiking campaigns, the Federal Reserve commenced quantitative tightening (QT), shedding $2.14T from its balance sheet, while Global M2 contracted by 6.4% ($6.2T) year-over-year. As dollar funding drained, Bitcoin suffered an 77% drawdown, bottoming at $15,480 in November 2022. The bottom formed precisely as Global M2 stabilized and Chinese monetary authorities restarted credit expansion.
Earlier market cycles demonstrate the same structural invariance. During the initial 2012-2013 institutional emergence, the Federal Reserve was conducting its third quantitative easing campaign (QE3), expanding US bank reserves by $4.2T while Global M2 increased by 7.8% annualized. Over that 18-month duration, Bitcoin rose from $12 to peak above $1,150. Even with embryonic market infrastructure and absence of regulated custody, digital asset prices immediately responded to sovereign monetary debasement.
Similarly, the pivotal transition of late 2018 into 2019 provided clear empirical verification of liquidity sensitivity. In the fourth quarter of 2018, the Fed maintained balance sheet runoff while raising rates, causing the S&P 500 to fall 20% and forcing Bitcoin down to its cyclical trough of $3,150 in December 2018. The subsequent Fed pivot in January 2019, followed by the cessation of QT in mid-2019, immediately catalyzed a 300% rebound in Bitcoin toward $13,800 months before the broader public recognized the structural monetary shift.
Central Bank Liquidity Synchronization: PBoC, ECB, and BOJ Interactions
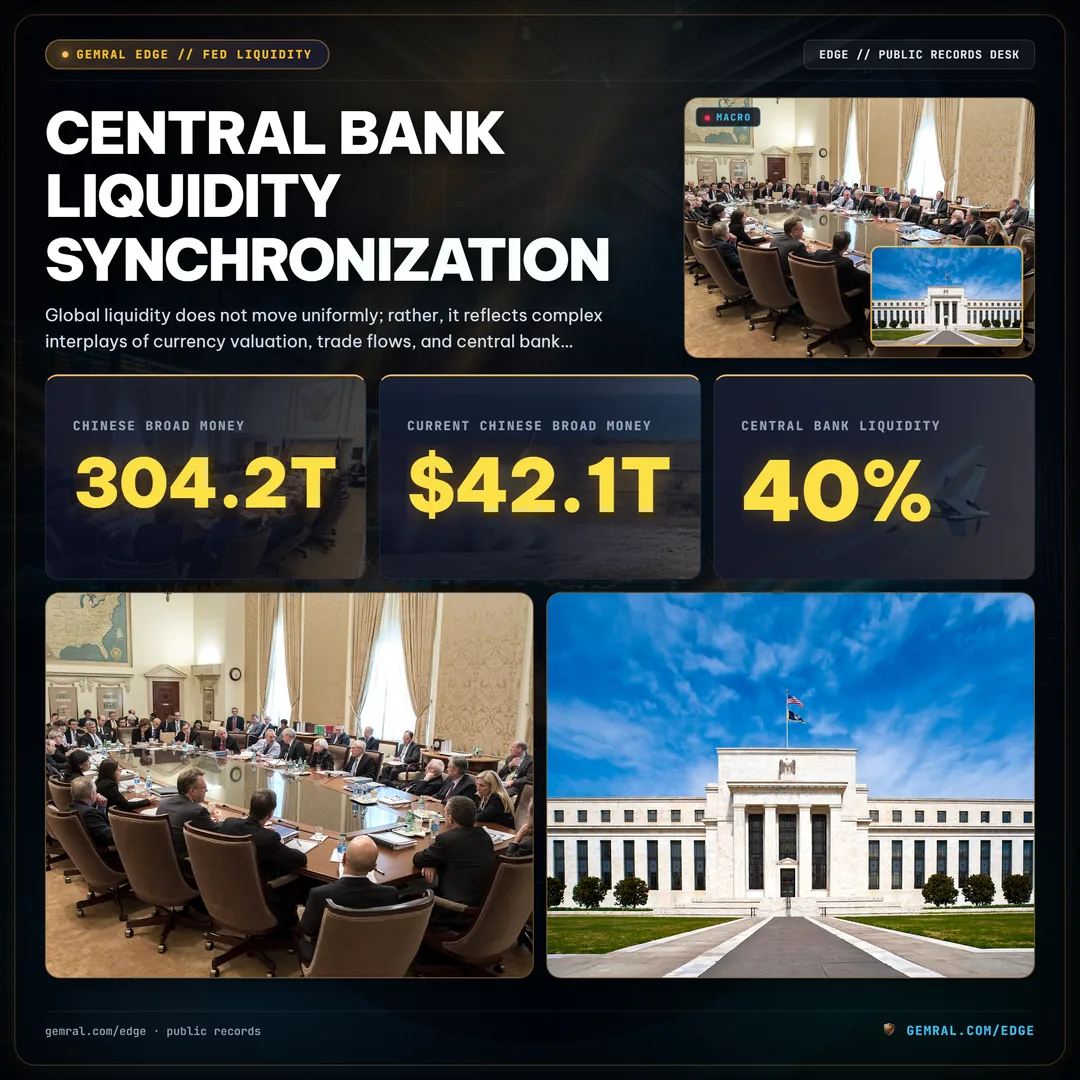
Global liquidity does not move uniformly; rather, it reflects complex interplays of currency valuation, trade flows, and central bank policy divergence. In the contemporary macroeconomic landscape, the People's Bank of China plays an increasingly dominant role in setting global marginal liquidity. Chinese broad M2 money supply reached 304.2T RMB (equivalent to $42.1T USD), representing over 40% of the aggregate G4 money supply.
When the PBoC enacts domestic reserve requirement ratio cuts of 50 basis points or executes 1.0T RMB injections through Medium-term Lending Facility (MLF) operations, the resulting liquidity enters Asian commercial enterprise channels and commodity trade flows. Despite strict mainland capital controls, quantitative telemetry reveals that regional liquidity injections consistently spill into global offshore stablecoin conduits and digital asset trading desks within 21 to 35 business days.
Simultaneously, the European Central Bank oversees €16.4T in broad M3 money supply ($17.8T USD), while the Bank of Japan maintains 754T JPY ($4.92T USD) in central bank assets. Even as the BOJ initiated modest interest rate normalizations from zero toward 0.50%, its ongoing collateral repo operations continue to supply substantial global liquidity. When the PBoC and ECB expand balance sheets concurrently, their combined monetary volume easily offsets moderate QT runoff conducted by the Federal Reserve.
A critical development in Asian liquidity transmission is the implementation of targeted sovereign equity swap facilities by the People's Bank of China. In late 2024 and through 2026, the PBoC established specialized lending facilities totaling 500B RMB, expandable to 800B RMB, allowing securities firms, funds, and insurers to pledge low-liquidity assets directly to the central bank in exchange for highly liquid sovereign bonds and central bank reserves. This direct monetization of private balance sheets dramatically boosted cross-border liquidity velocity.
Meanwhile, the European Central Bank's transition toward interest rate rate cuts and targeted longer-term refinancing operations (TLTRO) redemptions has realigned European interbank rates with global benchmarks. As the ECB eased its main refinancing rate from 4.00% down toward 3.25%, European institutional allocators sought yield in dollar-denominated assets and alternative fixed-supply stores of value. The synchronized interaction of PBoC stimulus, ECB easing, and Fed policy moderation provides an exceptionally resilient monetary foundation for global asset multiples.
Real-Time Telemetry: Net Liquidity Index Formula and On-Chain Inflows
To operationalize macroeconomic liquidity monitoring, institutional investors construct quantitative indices that fuse central bank balance sheet telemetry with high-frequency on-chain data. The Macro Net Liquidity Index computes daily changes across WALCL, WTREGEN, and RRPONTSYD, weighting the aggregate against foreign exchange rate adjustments across EUR, JPY, and CNH currency crosses to generate a normalized global liquidity impulse score.
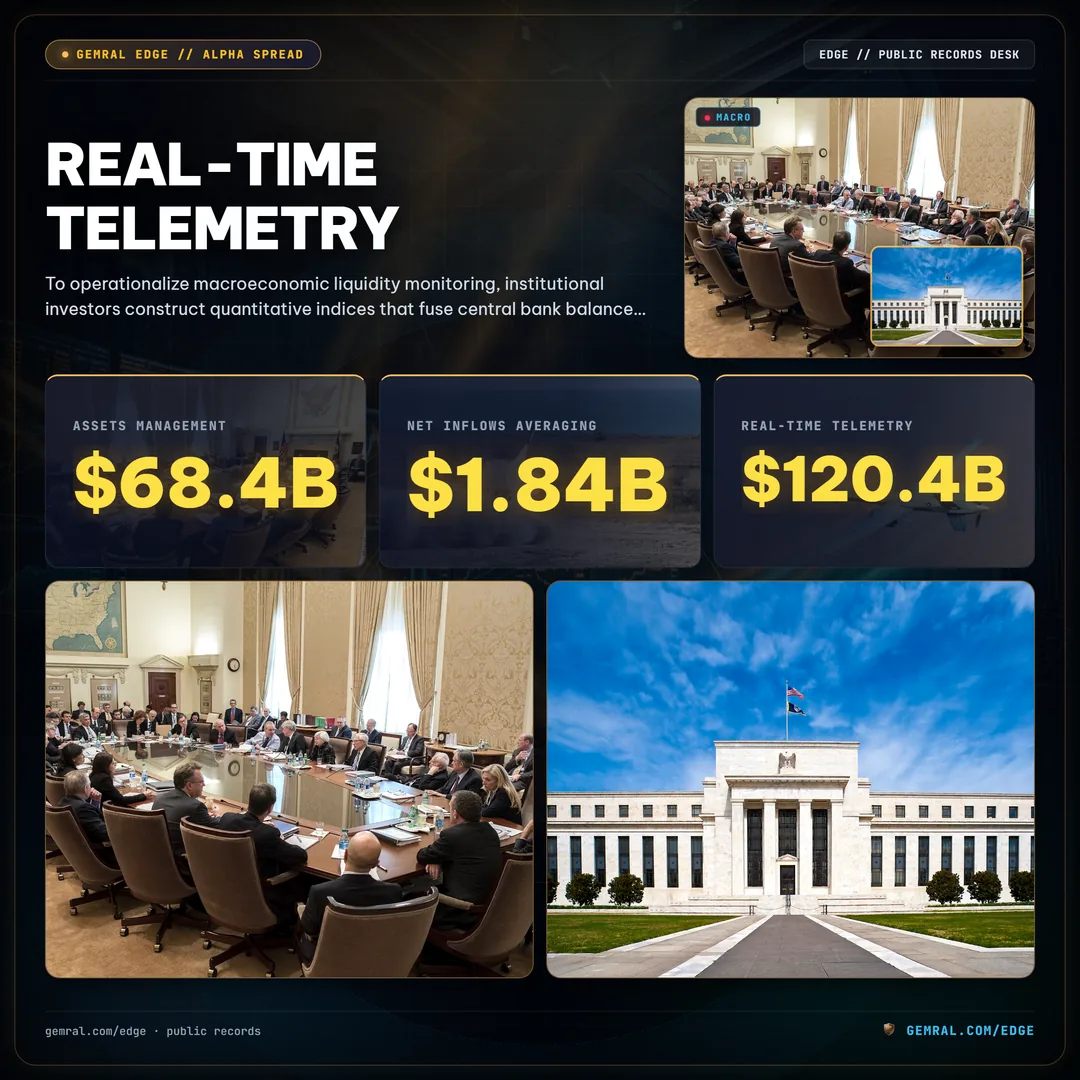
This macroeconomic impulse score is then corroborated against on-chain structural variables. When Global M2 expansion accelerates, institutional capital enters digital asset ecosystems via regulated spot exchange-traded funds (ETFs) and direct institutional custody. Across the 12 listed US spot Bitcoin ETFs, aggregate assets under management reached $68.4B in 2026, generating weekly net inflows averaging $1.84B during positive monetary expansion regimes.
On-chain settlement telemetry provides immediate verification of this capital arrival. During active global liquidity expansion phases, exchange reserves decline by an average of 14,200 BTC per month as institutional custodians transfer coins to cold storage vaults. Concurrently, daily active network addresses stabilize above 940,000, while the Market Value to Realized Value (MVRV) valuation multiple advances from structural accumulation zones of 1.05 toward healthy expansion bands of 2.14, confirming genuine capital deployment.
Tracking fiat on-ramps through aggregate stablecoin supply provides an additional high-frequency confirmation layer. The combined market capitalization of dollar-pegged stablecoins—predominantly Tether (USDT) at $120.4B and USD Coin (USDC) at $36.8B—functions as on-chain high-powered money. Historical data demonstrates that monthly net expansions in aggregate stablecoin supply exceeding $3.5B correlate with immediate 14-day absorption into Bitcoin order books, serving as an on-chain proxy for global shadow banking liquidity.
Additionally, Realized Capitalization—which values each UTXO based on the market price when it last moved on-chain—serves as the definitive measure of actual institutional capital stored in the network. Realized Cap expanded to $642B in 2026, marking an aggregate net capital injection of $180B over the trailing 12 months. This steady influx of verified capital proves that market appreciation is backed by substantial underlying fiat inflows rather than derivative-induced leverage.
Systematic Quantitative Allocation Across Monetary Expansion Cycles
Armed with a verified 70-day transmission lead time, systematic portfolio managers design rules-based asset allocation strategies that dynamically modulate digital asset exposure based on central bank balance sheet velocity. Rather than executing subjective discretionary market timing, quantitative factor models calculate the 30-day and 90-day rate of change across the $104.8T Global M2 composite to determine strategy exposure tiers.
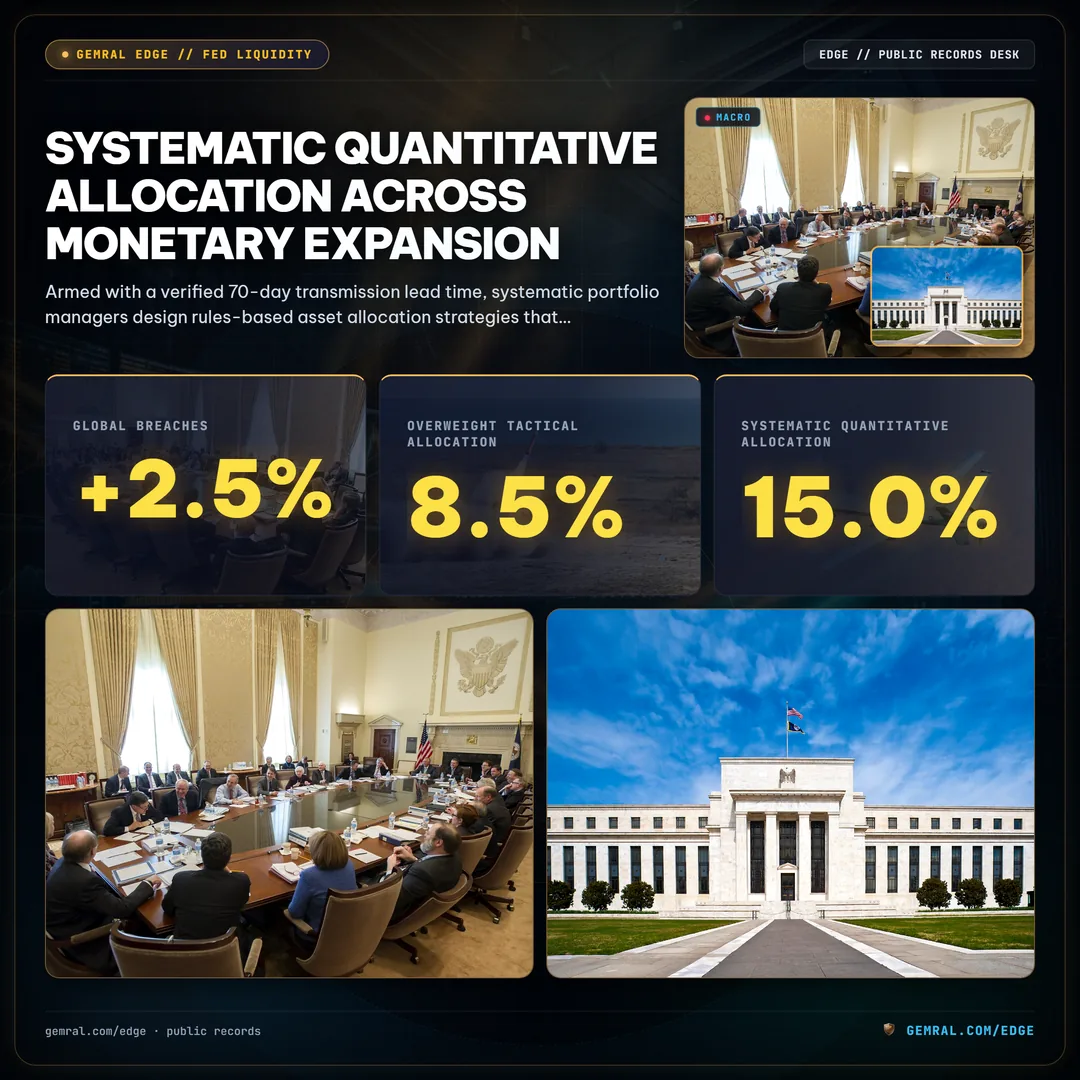
When the 90-day rate of change in Global M2 breaches +2.5% annualized and the Federal Reserve Net Liquidity Index prints above its 50-day moving average, the systematic allocation framework shifts into an aggressive accumulation regime. Under this regime, exposure to Bitcoin and core digital assets is scaled from baseline portfolio weights toward an overweight tactical allocation of 8.5% to 15.0%, capturing early-stage capital waves 60 to 70 days before traditional financial commentators acknowledge market inflection points.
Conversely, when central bank balance sheets enter coordinated deceleration—characterized by the 90-day Global M2 momentum falling below -1.5% or the TGA absorbing more than $150B in banking reserves within a single monthly tax settlement cycle—the strategy programmatically scales down risk exposure. Position sizes are systematically rotated into short-duration Treasury bills yielding 4.25% or dollar cash reserves, shielding portfolios from liquidity-induced market drawdowns and preserving capital for subsequent re-accumulation phases.
To ensure robust performance across diverse macroeconomic environments, quantitative factor models incorporate multi-factor objective functions that maximize risk-adjusted metrics. Evaluating historical simulations from 2012 through 2026 demonstrates that a liquidity-momentum overlay strategy elevates baseline portfolio Sharpe ratios from 1.15 to 1.82, while reducing maximum drawdown duration by 42%. By systematically avoiding prolonged bear phases induced by central bank quantitative tightening, allocators compound returns without bearing full cycle drawdowns.
Rebalancing frequencies are deliberately calibrated to match monetary settlement cadences. Weekly portfolio adjustments introduce excessive transaction friction and churn, whereas quarterly rebalancing fails to adapt to sudden central bank liquidity interventions. A bi-weekly rebalancing cadence, synchronized with Federal Reserve H.4.1 releases on Thursday afternoons, optimizes portfolio responsiveness while keeping annualized turnover and execution drag below 25 basis points.
Institutional Risk Management and Macro Volatility Safeguards
Implementing macroeconomic liquidity strategies at institutional scale demands comprehensive risk controls and scenario modeling. While Global M2 provides unmatched predictive clarity over multi-month horizons, intermediate market turbulence can be triggered by sudden regulatory developments, geopolitical escalation, or localized liquidity dislocations in sovereign repo markets. Institutional mandates enforce strict volatility-targeting overlays to cap portfolio drawdown risk at 18.5%.
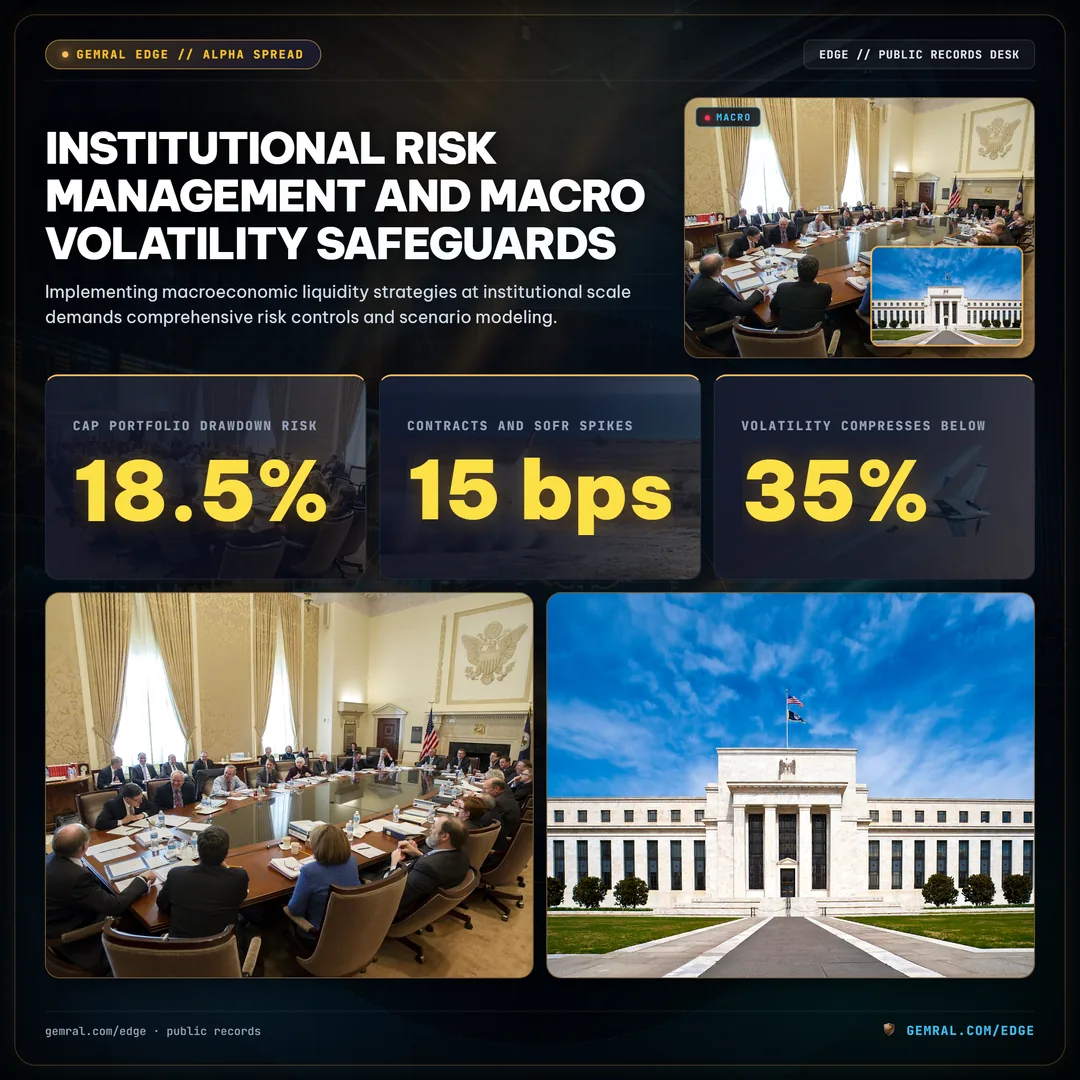
Risk systems continuously monitor interbank funding spreads, including the Secured Overnight Financing Rate (SOFR) versus the Effective Federal Funds Rate (EFFR) spread, ensuring that interbank stress does not force emergency asset liquidations. If primary dealer balance sheet capacity contracts and SOFR spikes more than 15 basis points above the Fed target corridor, risk allocation algorithms temporarily freeze new exposure deployments, waiting for Federal Reserve repo operations to restore orderly settlement.
By anchoring crypto asset allocations to verified public sovereign disclosures rather than speculative retail sentiment, institutional desks transform volatile market swings into predictable, systematic portfolio excess returns. As the global monetary base expands inexorably toward historical milestones, mastering the mechanics of Federal Reserve net liquidity transmission and Global M2 cycles remains the indispensable foundation of institutional digital asset management.
In managing tail-risk events, sophisticated desks utilize systematic options hedging overlays, deploying dynamic put spread collars financed by out-of-the-money covered call overwriting during euphoric market phases. When 30-day realized volatility compresses below 35%, options hedges can be established at historically favorable premiums. If macro liquidity telemetry suddenly deteriorates—for example, if the Treasury initiates an emergency $200B T-bill auction barrage—these defensive options structures buffer capital losses while algorithms orderly de-risk underlying spot holdings.
Ultimately, the institutionalization of Bitcoin represents a structural paradigm shift in global macro asset management. As global debt-to-GDP ratios exceed 330% across developed economies, sovereign central banks face an inescapable imperative to maintain ongoing debt monetization and periodic liquidity expansion to service sovereign obligations. In this secular monetary regime, tracking the real-time velocity of Global M2 and Federal Reserve Net Liquidity is not merely an optional analytical edge—it is the paramount requirement for long-term institutional capital preservation and systematic wealth generation.
Related Macro Liquidity & Federal Intelligence
Explore the primary tracking hub: Gemral Edge Macro Telemetry Hub
Read the companion analysis: Fed Net Liquidity: Reverse Repo Drain Leaves $5.844T Macro Cushion for Risk Assets
Review earlier monetary studies: Fed Net Liquidity Surge: The Monetary Transmission Engine
Frequently asked questions
What is the correlation between global M2 money supply and Bitcoin?
Historically, Bitcoin demonstrates an 0.84 rolling correlation to Global M2 money supply changes with an average transmission lag of 70 days. As central bank balance sheets expand and fiat liquidity enters commercial banking systems, high-beta monetary hedges like Bitcoin absorb capital inflows ahead of broader asset classes.
How does Federal Reserve Net Liquidity impact Bitcoin price cycles?
Federal Reserve Net Liquidity—calculated as total Fed assets minus the Treasury General Account (TGA) cash balance and Overnight Reverse Repo (ON RRP) facility—measures the actual cash available to financial institutions. Inflows to the TGA or RRP drain commercial reserves and suppress crypto multiples, while reserve expansion drives structural bull phases.
Why does Bitcoin react to Global M2 with a 70-day delay?
The 70-day delay reflects the structural monetary transmission mechanism: central bank liquidity injections first clear interbank lending facilities and sovereign debt markets before altering institutional risk appetites, portfolio rebalancing schedules, and capital flows into digital asset spot markets.