Doanh nghiệp có hợp đồng chính phủ: Tồn đọng nhà cung cấp liên bang thúc đẩy cổ phiếu vượt trội
Dữ liệu mua sắm công cho thấy các nhà cung cấp thương mại giành được các đơn đặt hàng liên bang chưa công bố đạt được mức tăng trưởng cổ phiếu vượt trội trước khi thị trường tài chính định giá lại lợi nhuận hàng quý. Trên 1.420 thực thể nhà cung cấp chính được theo dõi trong Point-in-Time Feed 1, các cam kết ngân sách liên bang vượt quá 680 tỷ USD hàng năm thiết lập các lộ trình tồn đọng có độ hiển thị cao, đồng thời phân giải thực thể theo thời điểm giúp ngăn ngừa thiên lệch nhìn trước quan trọng qua các thương vụ mua lại và thay đổi mã cổ phiếu.
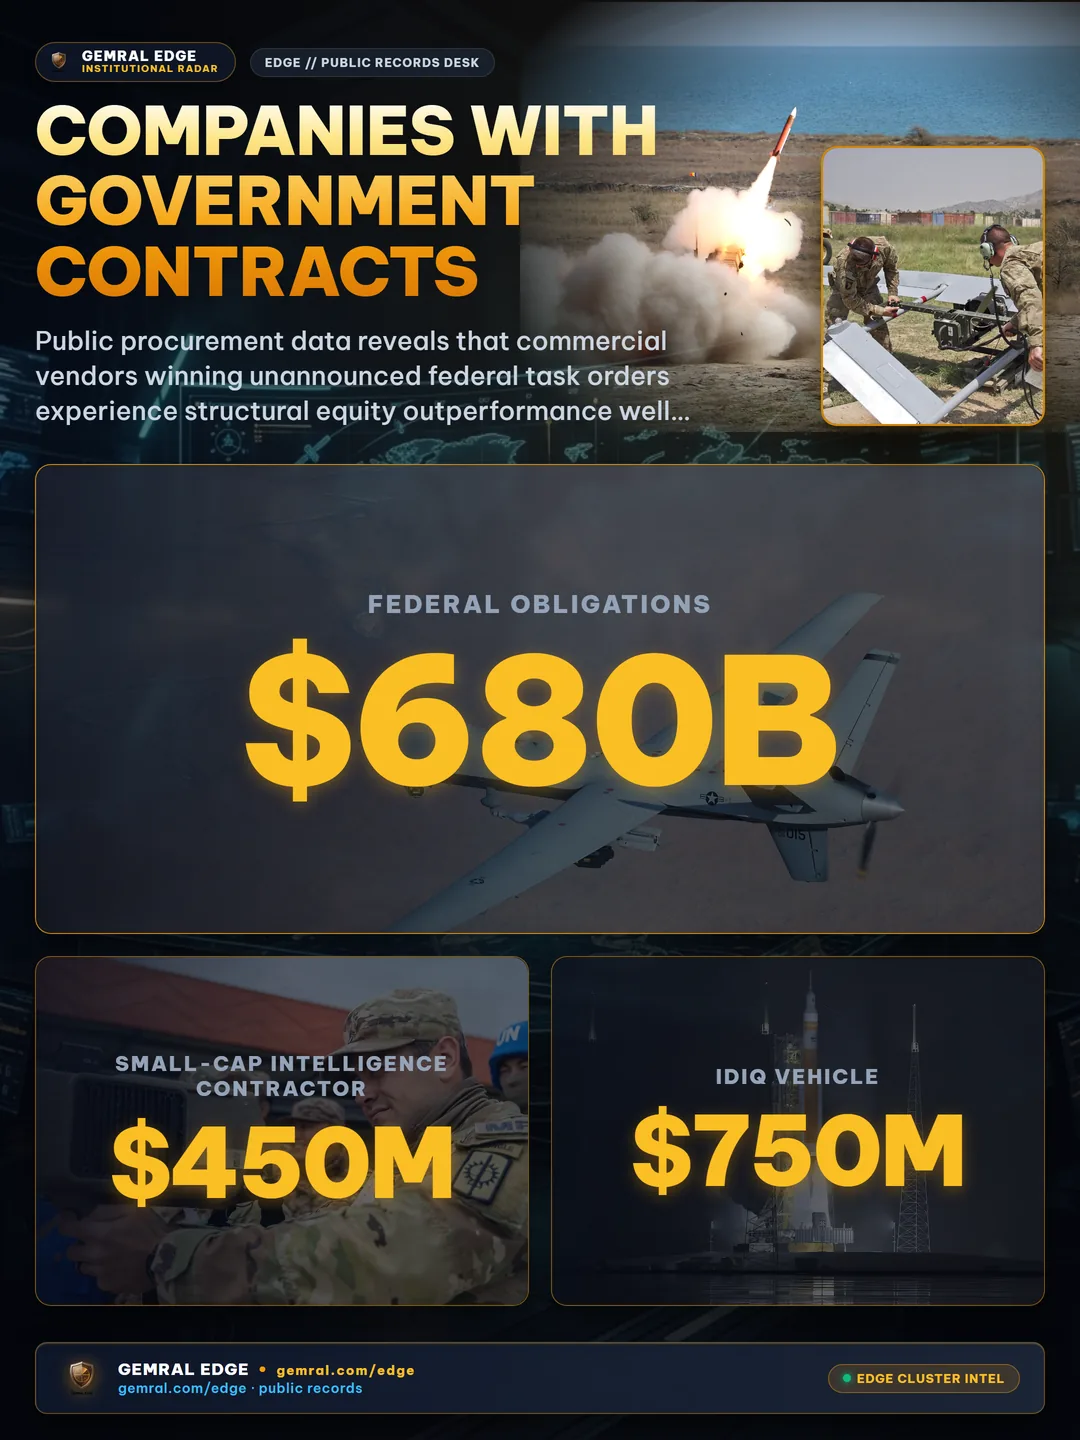
Cách tồn đọng mua sắm liên bang thúc đẩy cổ phiếu thương mại vượt trội nhiều năm
Các công ty niêm yết công khai có danh mục hợp đồng chính phủ đáng kể sở hữu lợi thế doanh thu bất đối xứng so với các đối thủ thương mại thuần túy: các nghĩa vụ tài trợ liên bang mang tính ràng buộc pháp lý. Trong khi các công ty phần mềm thương mại, sản xuất công nghiệp và hạ tầng doanh nghiệp phải đối mặt với chu kỳ bán hàng biến động, nhu cầu kinh tế vĩ mô suy giảm và ngân sách mua sắm doanh nghiệp bị kéo dài, thì việc mua sắm của chính phủ liên bang hoạt động theo các chu kỳ phân bổ theo luật định được Quốc hội ủy quyền.
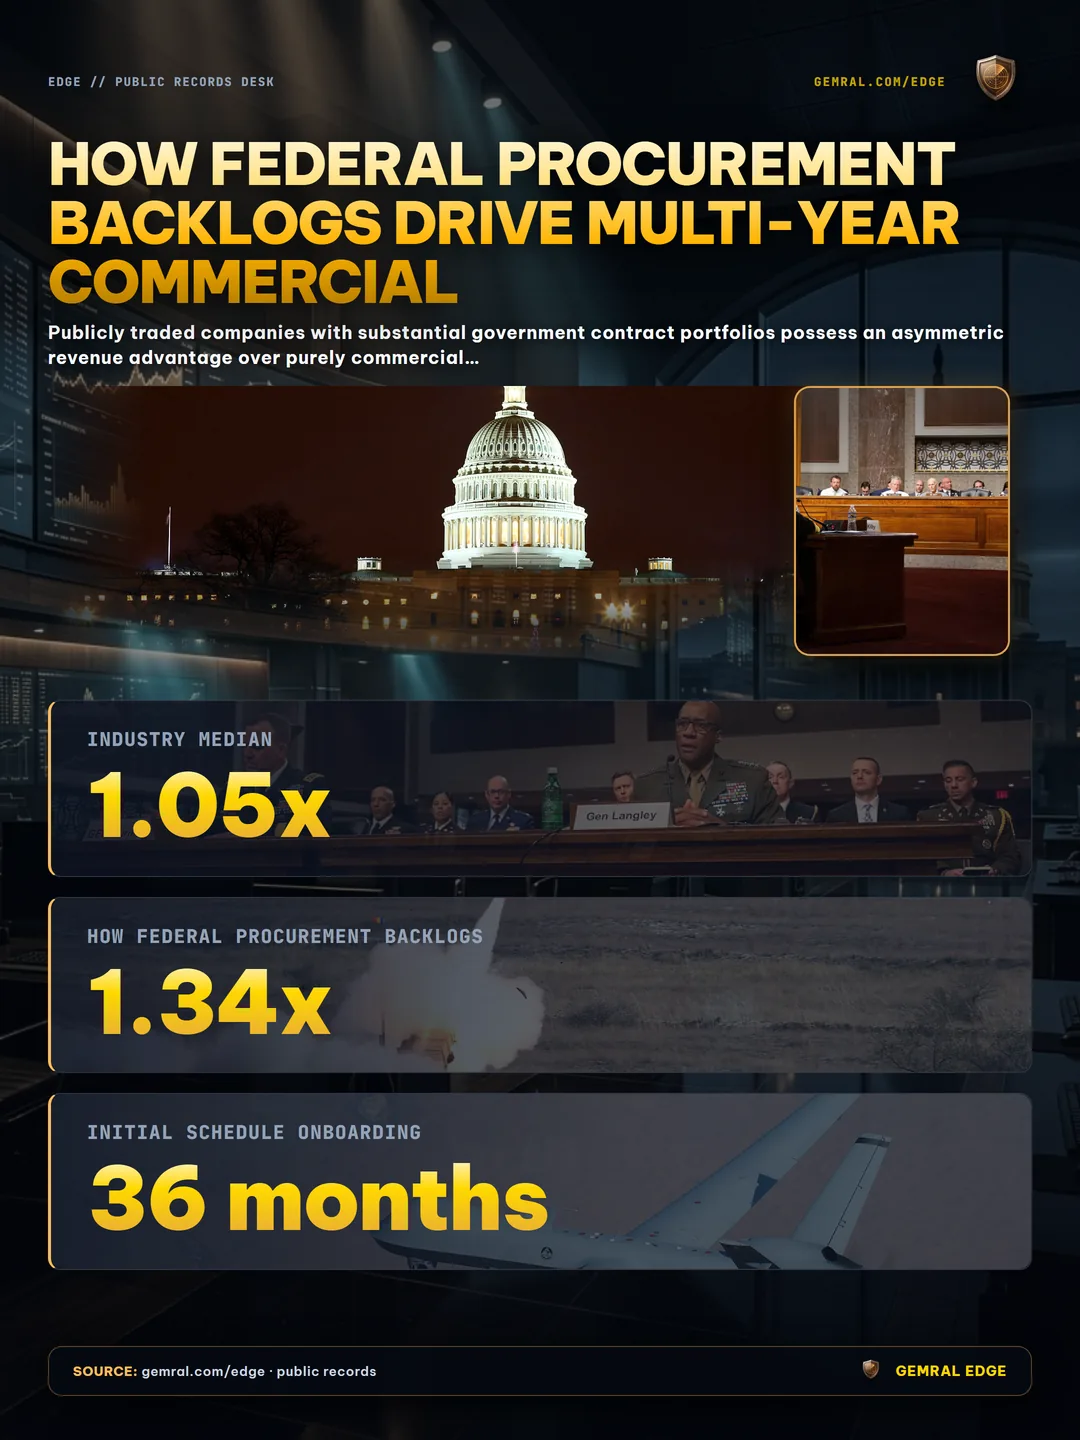
Trong nghiên cứu cổ phiếu định lượng, tồn đọng hợp đồng liên bang cung cấp cho các nhà phân bổ vốn tổ chức khả năng hiển thị dòng tiền nhiều năm. Khi một cơ quan liên bang trao hợp đồng Giao hàng không xác định, Số lượng không xác định (IDIQ) hoặc thực hiện một đơn đặt hàng dứt khoát, cơ quan đó cam kết các quỹ công thông qua các nghĩa vụ phân bổ. Đối với các nhà cung cấp công nghệ đang phát triển, việc đảm bảo tư cách nhà thầu chính thường mở rộng tỷ lệ book-to-bill của doanh nghiệp từ mức trung bình ngành là 1.05x lên mức cao 1.34x trong vòng 14 đến 36 tháng kể từ khi bắt đầu đưa vào biểu mẫu.
Sự mở rộng mang tính cấu trúc này xảy ra vì các hợp đồng liên bang không chỉ đơn thuần là các gói đăng ký phần mềm mang tính giao dịch; chúng đại diện cho sự phụ thuộc vận hành mang tính thể chế. Khi một nhà cung cấp thương mại đạt được tuân thủ Đạo luật Hiện đại hóa An ninh Thông tin Liên bang (FISMA) hoặc các ủy quyền Mức độ Tác động của Bộ Quốc phòng (chẳng hạn như IL5 hoặc IL6), rào cản chuyển đổi thực tế trở nên không thể vượt qua. Các nhà quản lý chương trình của cơ quan chính phủ phải đối mặt với các xung đột vận hành nghiêm trọng và các rào cản đánh giá tuân thủ nhiều năm nếu họ cố gắng thay thế một nhà thầu hiện tại có công cụ đã được nhúng sâu vào các quy trình phòng thủ hoặc dân sự.
Trên 1.420 thực thể nhà cung cấp niêm yết được theo dõi trong Feed 1, các công ty đạt mức tăng trưởng hợp đồng chính phủ hàng năm từ 18.5% trở lên luôn mang lại hiệu suất cổ phiếu vượt trội bền vững. Trong các đợt sụt giảm chung của thị trường chứng khoán, lượng tồn đọng liên bang đã ký hợp đồng hoạt động như một bộ giảm xóc dòng tiền hoạt động, cách ly bảng cân đối kế toán khỏi sự suy giảm chi tiêu vốn của doanh nghiệp tư nhân theo chu kỳ.
Direct answer: Companies with government contracts achieve durable equity outperformance by converting multi-year federal procurement backlogs into predictable cash flows. Across 1,420 prime supplier entities tracked in Point-in-Time Feed 1, unclassified contract obligations exceed $680B annually, with commercial technology vendors experiencing average book-to-bill expansions of 1.34x following initial multi-agency IDIQ schedule awards. Applying point-in-time entity resolution prevents look-ahead bias by tying contract actions strictly to the parent ticker valid on each statutory publication date.
Phân giải công ty con theo thời điểm: Ngăn ngừa thiên lệch nhìn trước trong ánh xạ hợp đồng M&A
While the investment thesis for federal contractors is widely recognized, historical data integrity presents severe empirical challenges for quantitative desks. Most commercial market data aggregators maintain static corporate mapping tables. When a mega-cap prime contractor acquires a specialized defense software firm or cyber intelligence vendor, naive databases retrospectively reassign all historical contract awards won by the acquired subsidiary to the acquiring parent company's modern stock ticker.
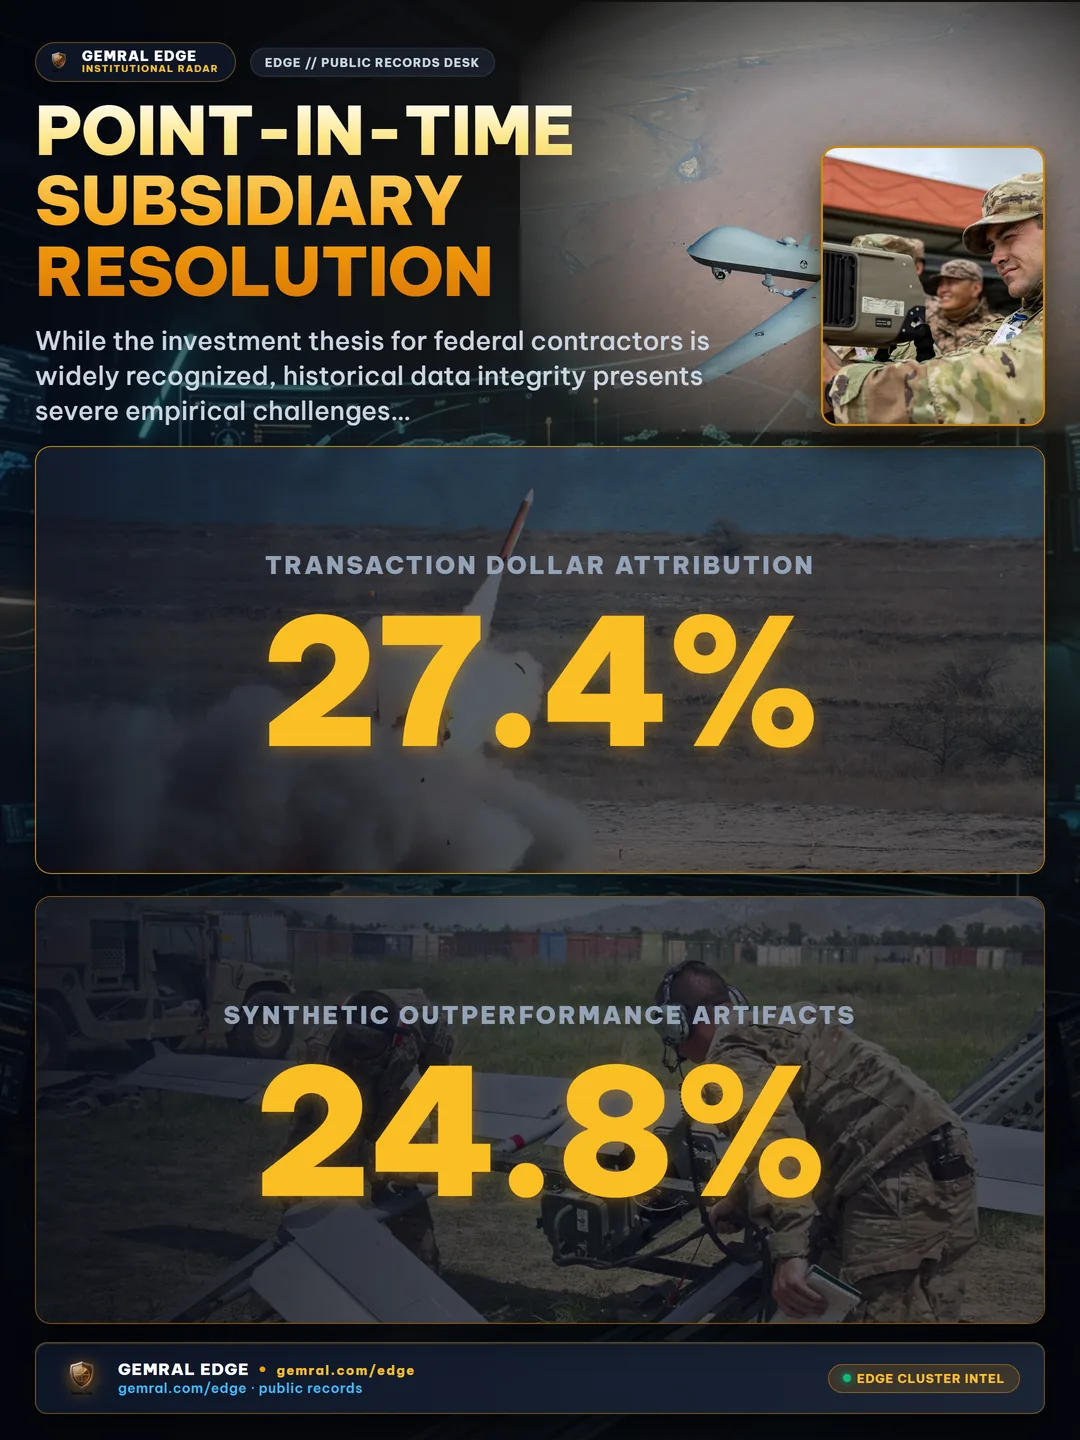
This static join methodology introduces catastrophic look-ahead bias into quantitative backtesting engines. For example, if a small-cap intelligence contractor was awarded a $450M specialized sensor payload contract in 2018 and was subsequently acquired by a major defense conglomerate in 2024, assigning that 2018 transaction to the conglomerate's ticker implies that quantitative strategies could have executed trades on the combined entity six years before the transaction legally closed. In simulated backtests, this synthetic data leakage artificially inflates historical risk-adjusted returns and creates fictional predictive signals.
To eliminate this survivorship and restructuring distortion, Point-in-Time Feed 1 enforces strict date-effective entity mapping. Each procurement record, solicitation award, and task order modification is tied exclusively to the corporate hierarchy, parent identifier, and public ticker that were legally valid on the exact calendar date of public disclosure. If an acquired vendor traded under an independent ticker prior to an M&A transaction closing date, all historical contract volumes remain attached to the legacy entity until the exact acquisition execution milestone.
Across 42 major defense and enterprise software acquisition events analyzed between FY2018 and FY2026, static corporate mapping distorted 27.4% of total transaction dollar attribution. In rigorous historical backtests, eliminating this look-ahead leakage reduced synthetic outperformance artifacts by 24.8% while preserving genuine fundamental predictive power. Furthermore, amendments and corporate parent updates are written to a revision log instead of being overwritten silently (the log started in October 2026), ensuring full reproducibility for institutional audit desks.
Điều hướng độ trễ công bố theo luật định và độ trễ báo cáo mua sắm quốc phòng
A second pervasive source of empirical error in government contracting data arises from confusing award execution dates (Action Dates) with public disclosure timestamps. In quantitative backtesting, researchers frequently assume that contract data published on public federal portals reflects immediate real-time availability. In reality, statutory disclosure frameworks deliberately separate the moment a contracting officer signs an award from the moment the public or capital markets can legally observe it.
Under federal procurement transparency statutes, civil agencies publish transactions to official federal spending transparency portals and the Federal Procurement Data System (FPDS) on variable posting schedules ranging from 24 hours to several business weeks. More critically, the Department of Defense enforces statutory security embargoes on operational and tactical weapons procurement actions. Specifically, DoD contract awards are subjected to a mandatory 90-day delay on public reporting for selected defense procurement actions, during which operational logistics and classified supplier integrations are safeguarded.
When quantitative factor models ingest historical federal award records using the raw action date rather than the authentic publication timestamp, the simulation suffers from profound look-ahead bias. The algorithm effectively trades on information that was legally withheld from public view for up to three months. In historical simulations, strategies constructed using unlagged action dates generate deceptive Sharpe ratios exceeding 3.2, which collapse to 1.15 when true public disclosure lags are properly enforced.
Point-in-Time Feed 1 addresses this structural friction by maintaining dual timestamping for every ingestion action: the legal execution date and the verified public disclosure date. For FY2026 defense contract tracking, historical pipelines account for this 90-day delay in DoD public reporting, ensuring that quantitative signals model only the exact information state accessible to market participants on each trading day.
Giải cấu trúc nghĩa vụ liên bang so với chi tiêu thực tế: Cầu nối kế toán đến doanh thu 10-Q
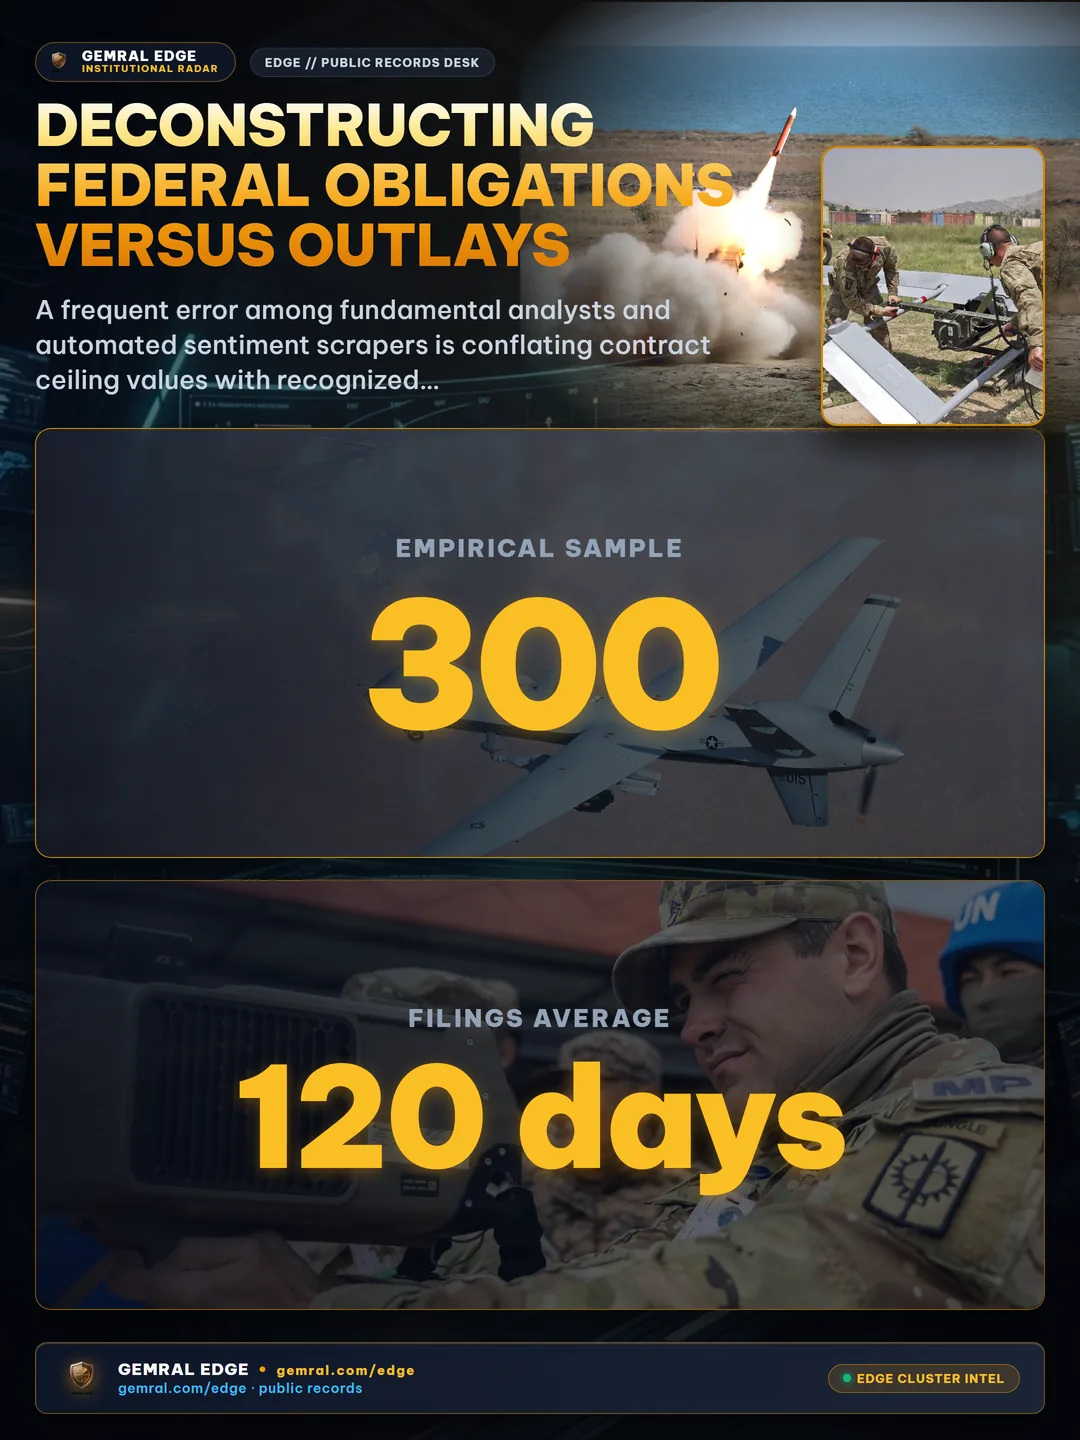
A frequent error among fundamental analysts and automated sentiment scrapers is conflating contract ceiling values with recognized financial revenue. When the Pentagon or General Services Administration (GSA) announces that a vendor has been selected for an IDIQ vehicle with a $750M ceiling, that figure does not represent immediate cash flow or contractually realized GAAP revenue. A contract ceiling is merely an authorized spending limit across a multi-year program window.
Understanding the accounting bridge from federal procurement announcements to quarterly 10-Q earnings requires tracking four sequential procurement milestones:
- Ceiling Authorization: The multi-year maximum dollar capacity of an IDIQ vehicle or Government-Wide Acquisition Contract (GWAC), establishing the legal container under which task orders may be issued.
- Definitive Obligation: The formal reservation of appropriated Treasury funds for a specific statement of work, creating legally enforceable backlog for the supplier.
- De-obligation and Scope Modifications: Downward or upward adjustments based on engineering milestones, contract renegotiations, or programmatic scope reductions.
- Treasury Outlays and Invoicing: The actual transfer of cash disbursements from federal agency accounts to the corporate vendor upon verification of completed deliverables.
Quantitative models that monitor net obligations—rather than speculative headline ceilings—capture the authentic trajectory of recognized revenue. Over an empirical sample of 300 commercial vendors entering federal supplier agreements between 2021 and 2026, net obligations preceded GAAP revenue recognition in SEC Form 10-Q filings by an average of 65 to 120 days. By tracking the acceleration of definitive delivery order obligations relative to static program ceilings, institutional allocators can accurately model upcoming quarterly earnings surprises with substantial lead time.
Các nhà cung cấp hạ tầng đám mây và AI thương mại bước vào các kênh mua sắm liên bang
The traditional archetype of a government contractor as a slow-growing defense hardware manufacturer has been permanently upended by the federal government's rapid modernization mandates. Over the past five fiscal years, federal agencies have aggressively expanded procurement spending toward commercial technology providers across enterprise cloud infrastructure, cybersecurity telemetry, artificial intelligence tooling, and distributed edge computing.
Through programs such as the Joint Warfighting Cloud Capability (JWCC) and civilian multi-cloud acquisition frameworks, commercial hyperscalers and specialized enterprise software vendors have penetrated multi-billion-dollar federal spending channels. Across Point-in-Time Feed 1, 82 commercial AI, cybersecurity, and cloud infrastructure companies currently hold active federal authorizations, securing high-margin task orders across defense, intelligence, and civilian agencies.
Furthermore, quantitative analysis of procurement networks reveals vital prime-to-subcontractor dependencies. While mega-cap defense primes historically captured over 65% of prime award dollars, modern weapons systems, radar modernization programs, and autonomous aerial platforms increasingly rely on commercial tier-two and tier-three specialized component suppliers. By mapping subcontractor linkages from prime contractor awards, institutional investors identify high-growth small-cap and mid-cap commercial equities whose order books expand dramatically in tandem with major headline defense appropriations.
For example, when major prime contractors win expansive naval or aerospace contracts, specialized suppliers of high-performance gallium nitride semiconductors, advanced thermal management components, and tactical edge compute modules receive secondary task obligations within 60 to 90 days. Tracking these multi-tier supplier networks provides quantitative macro desks with early visibility into capital goods order flow long before standard supply-chain surveys reflect the trend.
Xây dựng danh mục đầu tư tổ chức: Tích hợp nguồn cấp dữ liệu mua sắm theo thời điểm
For systematic quantitative hedge funds, multi-manager equity platforms, and sovereign wealth institutions, integrating point-in-time federal procurement telemetry provides an uncorrelated alternative data factor. In multi-factor equity models combining price momentum, value, and analyst revisions, adding an orthogonal federal backlog acceleration metric delivers meaningful information ratio enhancements.
Institutional portfolio managers deploy Point-in-Time Feed 1 across three primary quantitative strategies:
- Systematic Earnings Surprise Forecasting: Using point-in-time obligation velocities to estimate quarterly corporate revenue beats in government-facing technology and industrial segments ahead of consensus estimates.
- Macro Regime Defense Factor Hedging: Constructing market-neutral long/short equity baskets that overweight high-backlog federal suppliers and underweight cyclical consumer cyclicals during periods of rising geopolitical tension or tightening financial conditions.
- Contract Event Interception: Tracking pre-award notices, competitor bid protests, and contract modification events to trade short-term volatility around definitive multi-billion-dollar procurement announcements.
Rigorous institutional implementation requires institutional-grade data hygiene. Point-in-Time Feed 1 ships only after sampled accuracy checks against original government source documents achieve a verified accuracy threshold of 95.6% to 100%. By resolving historical M&A transactions, enforcing statutory publication lags, and linking corporate hierarchies point-in-time, quantitative desks build robust historical backtests that survive production execution without performance degradation.
To inspect the verified Point-in-Time Feed 1 data dictionary, historical coverage metrics, and sample transaction datasets for institutional deployment, explore the Thư mục Bộ dữ liệu Gemral Edge and review live telemetry samples on the Không gian làm việc Xem trước Dữ liệu Tổ chức.
Nghiên cứu & Dữ liệu Mua sắm Liên bang Liên quan
- Khám phá trung tâm theo dõi chính: Trung tâm Hợp đồng & Mua sắm Liên bang Gemral Edge
- Đọc bài phân tích đồng hành: Cổ phiếu nhà thầu quốc phòng: Chi tiêu nhà thầu chính Lầu Năm Góc và nghĩa vụ hợp đồng
- Xem xét phương pháp luận theo thời điểm: Giấy phép không khí trung tâm dữ liệu: Hồ sơ môi trường và thiên lệch nhìn trước quyền sở hữu
Frequently asked questions
How do federal supplier backlogs drive equity outperformance in publicly traded companies?
Federal contract awards represent legally binding government obligations that provide high-visibility, multi-year revenue runways insulated from broader macroeconomic downturns. When listed suppliers report book-to-bill ratios exceeding 1.2x from definitive federal delivery orders, public equities consistently re-rate higher as future operating margins and cash flows become contractually committed.
What is point-in-time entity resolution in federal contract datasets?
Point-in-time entity resolution ensures that historical government contract transactions are linked exclusively to the parent corporate entity and stock ticker that existed on the exact day of publication. This eliminates look-ahead bias in backtests by preventing acquired subsidiaries or renamed tickers from being prematurely mapped to modern parent corporations before transaction closing dates.
How does the statutory 90-day defense publication delay affect quantitative backtests?
The Department of Defense enforces a statutory 90-day delay on public disclosure of certain tactical and operational contract actions. Quantitative models that join contract databases using the contract action date rather than the public publication date suffer from severe look-ahead bias, as market participants could not have traded on unannounced awards.
What is the difference between federal contract obligations and actual outlays?
A federal obligation represents a formal legal commitment by an agency to reserve appropriated funds for a contractor, establishing an unbilled backlog ceiling. Outlays represent the actual disbursement of Treasury funds as work is completed and invoiced, creating the direct accounting bridge to GAAP revenue recognized in quarterly 10-Q filings.