Hedge Fund Data Engineer: Point-in-Time Entity Resolution and Ticker Mapping at Scale
An architectural reference and empirical data engineering specification for quantitative researchers and data teams designing bitemporal ingestion pipelines, resolving statutory public contract disclosures, and mapping effective-dated corporate hierarchies without forward-looking data leakage.
Executive Summary & Direct Answer
For a hedge fund data engineer building production alternative data pipelines, point-in-time entity resolution is the foundational architectural process of linking statutory government contract awards, congressional trade disclosures, and regulatory filings to the exact equity ticker that was actively trading on the public disclosure date. Unlike static relational database lookups that erroneously map historical transactions to modern corporate parent structures, an audited point-in-time pipeline eliminates look-ahead and survivorship bias across statutory federal records. By tracking effective-dated corporate parent hierarchies, engineering bitemporal valid-time and transaction-time schemas, and enforcing statutory publication delays—such as the 90-day embargo on defense procurement actions—quantitative factor models can safely ingest public records without leaking future corporate actions into historical factor simulations.
Across an audited corpus of 850,000+ resolved public events spanning 4,745 distinct historical equity tickers, standardizing entity mapping requires enforcing a minimum 95.0% sampled precision gate against original public filings. In empirical benchmark audits, static parent-company mappings introduced systematic look-ahead bias across 3.31% of multi-year contract histories, while dating records by activity execution timestamps rather than publication timestamps contaminated historical simulations by a statutory 90 days for defense awards and a median of 27 days for congressional disclosures. This whitepaper establishes the complete mathematical, relational, and architectural framework required to deploy production-grade entity resolution for quantitative portfolio management.
Table of Contents
Key Infrastructure Baseline Metrics
- Resolved Event Corpus: 850,000+ resolved events (857,327 estimated) spanning public contract obligations, defense announcements, congressional transactions, and lobbying reports.
- Historical Ticker Breadth: 4,745 distinct tickers appear in the resolved event history, including delisted, merged, and renamed historical equities.
- Federal Contract Volume: 650,000+ federal contract transactions cataloged and mapped with transaction-level obligation precision.
- Congressional Trading Disclosures: 50,000+ congressional stock transactions mapped with statutory disclosure verification.
- Corporate Network Entities: 11,000+ cataloged corporate entities linked to 21,000+ officers, directors, and institutional insiders.
- Defense Procurement Breadth: 38,000+ daily defense contract announcements and 13,850 formal bid protest dockets monitored across multi-year procurement cycles.
- Quality Gate Precision: 10 out of 10 core record types passing the rigorous sampled accuracy verification gate of ≥ 95.0% against original public documents (measured October 23, 2026).
- Standardized Dataset Packaging: Institutional Wave 1 Parquet delivery pack containing 158 compressed files, 24 relational tables, and 786,636 verified rows across 300 target equities.
The Look-Ahead Trap: Why As-Is Ticker Joins Break Quantitative Factor Models
In quantitative asset management, the performance of systematic trading strategies depends entirely on the chronological integrity of input data. Every quantitative researcher understands the fatal consequence of look-ahead bias: if a historical simulation incorporates information that was not accessible to market participants at the time of trade execution, the resulting simulation generates inflated Sharpe ratios, spurious predictive signals, and catastrophic live drawdowns. While quantitative teams have spent decades engineering point-in-time corporate fundamentals and price adjustment engines to account for stock splits and dividend distributions, institutional alternative data pipelines remain plagued by unvetted relational joins.
For a modern hedge fund data engineer tasked with constructing an institutional data lake, integrating unstructured public records—such as federal procurement awards, congressional stock transaction disclosures, and corporate lobbying registrations—presents a complex ontological challenge. When quantitative analysts ingest these public records, the common temptation is to perform an instantaneous relational join between vendor names and a static modern security master database. For example, if a data pipeline reads a contract awarded to a subsidiary and immediately joins it against the current parent company's stock ticker, it commits a critical survivorship and look-ahead error.
Consider a concrete historical scenario: an aerospace supplier operated as an independent publicly traded entity or privately held defense contractor throughout 2018 and 2019, receiving hundreds of millions of dollars in federal defense obligations. In late 2020, the company was acquired by a major defense prime contractor, and its historical assets were consolidated into the parent corporation. If a data engineer joins the 2018 contract records using a modern corporate hierarchy table, those historical revenues are retroactively attributed to the acquiring parent company during 2018—two full years before the acquisition closed.
In historical simulation, a quantitative factor model evaluating revenue momentum or government contract exposure would observe substantial government contract inflows attributed to the acquirer in 2018, long before the transaction was conceived or announced. The model's historical trade simulation would take positions based on knowledge of a future corporate consolidation. In empirical historical audits conducted on public contract datasets, static parent-company mappings introduced systematic look-ahead bias across 3.31% of all multi-year contract histories. For systematic multi-strategy funds and statistical arbitrage desks, a 3.31% structural contamination rate in an underlying feature table is more than sufficient to render an entire signal orthogonal or fatally compromised in production.
| Mapping Strategy | Entity Resolution Mechanism | Look-Ahead Bias Risk | Historical Accuracy | Institutional Quant Suitability |
|---|---|---|---|---|
| Static Modern Join | Current parent company & ticker lookup | Severe (Retroactive acquisition attribution) | Unacceptable (> 3.3% structural distortion) | Rejected by Risk & Compliance |
| Text-Fuzzy Matching | String distance on vendor name string | High (False positive subsidiary joins) | Poor (Conflates distinct legal subsidiaries) | Unacceptable for Production Trading |
| Static CUSIP Lookup | Static security identifier cross-reference | Moderate (Fails on ticker renames & spin-offs) | Sub-optimal (Lacks effective date boundaries) | Limited to Baseline Research |
| Point-in-Time Graph | Effective-dated bitemporal hierarchy mapping | Eliminated (0% look-ahead leakage) | Audited (≥ 95.0% sampled precision gate) | Institutional Production Standard |
To eliminate this structural vulnerability, institutional funds rely on specialized alternative data for hedge funds architectures that decouple physical real-world event occurrences from system ingestion timestamps, enforcing strict point-in-time entity resolution across every ingested row.
Statutory Disclosures vs. Market Availability: Calculating True Publication Lags
Beyond corporate entity lineage, the second major structural trap confronting the hedge fund data engineer is disclosure latency. In quantitative research, there is a fundamental distinction between the activity date (the calendar date when an action physically occurred in the real world) and the publication date (the exact calendar day and timestamp when the record was legally posted to a public register and became observable to market participants).
Public data sources routinely index records by their internal document execution date. For example, federal procurement records prominently display the action_date indicating when a contracting officer signed an obligation agreement. Congressional trading forms display the transaction_date indicating when a senator or representative bought or sold an asset. Corporate insider filings document the trade execution day, while lobbying filings report the close of the preceding fiscal quarter.
If an algorithmic trading strategy or quantitative simulation engine calculates daily factor signals using the activity execution date, it assumes market participants possessed instantaneous omniscience. In reality, statutory, regulatory, and bureaucratic processes enforce substantial reporting windows before any of these records become public knowledge:
- Federal Defense Contract Obligations: By statutory regulation and national security policy, major defense procurement transactions are subject to a mandatory 90-day reporting delay. While a contract modification may be signed by the Department of Defense on March 1, the public transaction is not published to public spending ledgers until June 1. Dating historical simulations by the March 1 execution timestamp introduces an uncorrected 90-day look-ahead window into factor simulations.
- Congressional Stock Trades: Under the STOCK Act of 2012, members of the United States Congress are required to disclose personal financial transactions within 45 days of the trade date or within 30 days of receiving notification. In an audited empirical analysis of 63,122 congressional trades executed between 2018 and 2026, the median disclosure latency was 27 calendar days, with the 90th percentile reaching 63 calendar days. Evaluating congressional portfolio momentum on the trade execution date assumes immediate information propagation that did not exist in reality.
- Corporate Insider Filings: Statutory Section 16 insider transaction reports are legally mandated to be filed within two business days of trade execution. Across an empirical sample of 35,226 insider trades, the median filing delay was 1 calendar day, with the 90th percentile extending to 4 calendar days due to weekend filings and technical submission queues.
- Lobbying Disclosure Registrations: Quarterly lobbying expenditure reports filed under the Lobbying Disclosure Act (LDA) are due 20 days following the conclusion of each calendar quarter. In an empirical audit of 8,975 lobbying filings submitted since 2018, the median reporting delay was 20 calendar days, with the 90th percentile at 21 days.
| Data Domain | Activity Date Definition | Publication Date Definition | Observed Median Delay | Observed 90th Percentile | Mandatory Simulation Timestamp |
|---|---|---|---|---|---|
| Defense Contract Obligations | Officer signature date | Public register posting date | 90 calendar days | 90 calendar days (Statutory) | publication_date (+90d) |
| Civilian Federal Contracts | Contract obligation date | Public registry ingestion | 1 to 3 calendar days | 7 calendar days | published_at |
| Congressional Stock Trades | Trade execution date | Public disclosure filing date | 27 calendar days | 63 calendar days | disclosure_date |
| Corporate Insider Filings | Transaction execution date | SEC statutory acceptance date | 1 calendar day | 4 calendar days | filed_at |
| Quarterly Lobbying Reports | Quarter close date | LDA posting date | 20 calendar days | 21 calendar days | dt_posted |
For a quantitative factor engineer, building signals on activity_date represents pure mathematical error. Every signal generation model must operate exclusively on the publication timestamp, ensuring that simulated portfolio rebalances occur strictly after the broader financial market could legitimately observe the public record.
Bitemporal Pipeline Architecture: Separating Event Occurrence from Ingestion Timestamps
To systematically eliminate look-ahead bias while preserving the full historical audit trail of public record modifications, an institutional hedge fund data engineer must implement a bitemporal data modeling architecture. Originating in temporal database theory, bitemporal data architecture explicitly models two distinct orthogonal temporal dimensions for every single record in the system:
- Valid Time (Business Time): The span of time during which a record is factually true and valid in the real world. In alternative data, valid time represents the effective operational period of a contract, the statutory execution window of a trade, or the active duration of an officer's tenure.
- Transaction Time (System Time): The span of time during which a record was stored, observable, and immutable within the database system. Transaction time represents the precise millisecond timestamp when the record was ingested, verified, and made queryable to quantitative algorithms.
The necessity of transaction time becomes obvious when evaluating historical dataset amendments. Public agencies frequently post retroactive corrections to procurement records: obligated amounts are adjusted downward, deobligations are processed months after initial contract completion, and filing clerical errors are amended. In a standard relational database that updates records in place (using SQL UPDATE statements), historical states are overwritten.
If an analyst executes a historical simulation in 2026 for a strategy trading in 2021, an in-place updated database will expose the 2026 corrected values to the 2021 simulation logic—values that no investor in 2021 could have known. In contrast, an immutable bitemporal data store treats updates as append-only records with strict valid_from, valid_to, system_from, and system_to temporal coordinates (detailed further in our guide to bitemporal hedge fund database architecture).
-- Bitemporal Schema Representation for Point-in-Time Event Resolution
CREATE TABLE edge_resolved_events (
    event_id UUID PRIMARY KEY DEFAULT gen_random_uuid(),
    source_event_id VARCHAR(128) NOT NULL,
    event_family VARCHAR(64) NOT NULL, -- 'contract', 'congress_trade', 'lobbying'

    -- Valid Time Dimensions (Real World)
    activity_date DATE NOT NULL,
    effective_date DATE,
    expiration_date DATE,

    -- Transaction Time Dimensions (System / Market Availability)
    published_date DATE NOT NULL,
    ingested_at TIMESTAMPTZ NOT NULL DEFAULT clock_timestamp(),
    superseded_at TIMESTAMPTZ, -- NULL indicates current active revision

    -- Entity Resolution Outputs Point-in-Time
    direct_entity_id UUID REFERENCES edge_entities(entity_id),
    listed_parent_id UUID REFERENCES edge_entities(entity_id),
    ticker_asof VARCHAR(16), -- Equity ticker trading on published_date
    cusip_asof VARCHAR(9),   -- CUSIP identifier valid on published_date
    cik_asof VARCHAR(10),    -- Central Index Key valid on published_date

    -- Financial and Quantitative Attributes
    normalized_amount NUMERIC(18, 2),
    currency VARCHAR(3) DEFAULT 'USD',
    confidence_score NUMERIC(5, 4) CHECK (confidence_score BETWEEN 0.0 AND 1.0)
);

CREATE INDEX idx_resolved_events_pit_lookup
ON edge_resolved_events (ticker_asof, published_date)
WHERE superseded_at IS NULL;
When a quantitative researcher runs a historical factor simulation as of 2022-03-15, the query engine applies a deterministic temporal filter:
WHERE published_date <= '2022-03-15' AND (superseded_at IS NULL OR superseded_at > '2022-03-15'). This ensures the simulation reconstructs the exact state of global alternative data available on that morning's trading desk, achieving zero information leakage.
Point-in-Time Corporate Graph: Resolving Mergers, Spin-offs, and Ticker Renames
Constructing a bitemporal event table is only the first step. The second, and often most challenging, operational hurdle for the hedge fund data engineer is mapping heterogeneous legal entity names to standard tradeable securities through time.
Federal agencies, defense branches, and legislative ethics offices do not store records indexed by stock ticker or Bloomberg FIGI. Instead, records arrive labeled with varied vendor name strings, unique entity identifiers (UEIs), Commercial and Government Entity (CAGE) codes, corporate subsidiary names, or joint venture identifiers. Over an eight-year historical window, corporate entities undergo complex structural transformations:
- Mergers and Acquisitions: When Raytheon Company merged with United Technologies Corporation in April 2020 to form Raytheon Technologies (later RTX Corporation), hundreds of historical contract actions, active patent assignments, and subsidiary supplier links required point-in-time re-indexing. Historical contracts awarded to legacy subsidiaries prior to the closing date must reflect legacy equity identifiers, while contracts published post-merger must map to the consolidated equity.
- Corporate Spin-offs: When a conglomerate spins off an enterprise division into an independent public entity, pre-spin historical contracts belonged to the parent company's balance sheet, while post-spin awards belong exclusively to the new ticker. Attributing historical contracts to the newly spun-off entity before its initial public offering introduces catastrophic survivorship distortion.
- Ticker Renames and Class Modifications: Equities routinely rebrand their trading symbols (e.g., Facebook changing from FB to META in 2022, or L3Harris consolidating from HRS following the L3 merger). Cross-sectional factor models indexing data by ticker will experience broken joins and fragmented time series unless every historical entity link maintains an effective-dated validity window.
| Corporate Action Event | Target / Subsidiary Entity | Pre-Event Active Ticker | Post-Event Active Ticker | Point-in-Time Entity Resolution Rule |
|---|---|---|---|---|
| Merger & Consolidation | United Technologies / Raytheon | UTX / RTN |
RTX |
Actions published prior to April 2020 map to legacy tickers; post-close actions map to RTX. |
| Defense Consolidation | L3 Technologies / Harris Corp | LLL / HRS |
LHX |
Pre-merger filings retain historical tickers; post-merger actions resolve to LHX. |
| Corporate Rebranding | Facebook Inc / Meta Platforms | FB |
META |
Actions published prior to June 2022 map to FB; post-rebrand actions map to META. |
| Corporate Spin-off | GE Aerospace / GE Vernova | GE |
GE / GEV |
Power and electrification awards published post-April 2024 map to GEV; pre-split map to GE. |
| Technical Ticker Change | Jacobs Engineering Group | JEC |
J |
Pre-rename actions retain JEC; post-rename actions carry trading symbol J. |
To manage these dynamic relationships, the entity resolution engine maintains an audited parent hierarchy table (edge_entity_parent_links). Each relationship record defines a direct_entity_id (the actual contracting subsidiary or branch), a parent_entity_id (the ultimate controlling corporate entity), an effective_from date, and an effective_to date. When an event is resolved, the engine evaluates the published_date against the temporal validity window of the parent link, extracting the ticker that was actively trading on secondary exchanges on that specific calendar day. Across 4,745 distinct historical equities cataloged in the institutional event history, this graph architecture ensures complete historical fidelity.
Contract Allocation and Defense Lags: Managing the 90-Day Post-Close Rollover
The intersection of corporate mergers and statutory disclosure lags creates one of the most intricate edge cases in alternative data engineering: the post-close publication rollover.
As established in Section 2, federal defense contract obligations are subject to a statutory 90-day reporting embargo. What happens when a contract is legally signed by a subsidiary prior to an acquisition closing date, but the statutory 90-day embargo delays public disclosure until after the acquisition has officially closed?
Consider a high-value defense contract signed by an acquired target company in January 2020. In April 2020, while the contract is still embargoed within the Department of Defense, the acquisition officially closes, and the target company's legacy stock ticker is delisted from the New York Stock Exchange. In May 2020—exactly 90 days after initial signing—the federal procurement ledger publicly releases the contract record.
If the entity resolution pipeline maps the record to the target company's legacy ticker based on the January signature date, the record resolves to a dead, delisted ticker that no quantitative fund could trade in May 2020. Conversely, if the pipeline naively maps all historical records of the target company to the acquirer, it introduces look-ahead bias across all pre-2020 transactions.
The correct architectural resolution, established in institutional data specifications, enforces the Publication Date Rollover Principle:
The Publication Date Rollover Principle: A contract action must always retain its physical signing entity in
direct_entity_idto maintain legal auditability. However, the tradeable ticker symbol (ticker_asof) must represent the equity that traded on the public capital markets on the exact day the record became publicly accessible. If an acquisition closed prior to publication, the tradeable ticker rolls to the publicly traded acquirer. If the acquirer is privately held or unlisted, the tradeable ticker remains null, preventing phantom equity joins.
In an exhaustive historical pipeline audit across all federal procurement obligations from FY2018 through FY2026, exactly 659 federal contract actions were identified that were signed before an acquisition closed but published to public ledgers after the close date. Under audited entity resolution rules:
- 651 actions successfully rolled to the publicly traded listed acquirer valid on the publication date, directly allocating revenue to active equities (including 361 actions rolling to RTX, 124 to LHX, 49 to General Dynamics, 43 to Northrop Grumman, 49 to legacy United Technologies prior to subsequent rebranding, and 25 to SAIC).
- 8 actions involved acquisitions by private equity consortia or foreign unlisted entities; these records correctly preserved the legal subsidiary entity while leaving
ticker_asofempty, preventing false equity signals from leaking into portfolio factor models. - An additional 254 contract actions involved corporations that executed technical ticker renames between contract signing and public disclosure (including 121 transitions from UTX to RTX, 68 from HRS to LHX, 44 from JEC to J, 17 from ASGN to EFOR, 3 for BALL, and 1 for MRSH), ensuring that all post-rename publications were immediately tradeable under active equity symbols.
Managing this rollover with mathematical precision ensures that systematic trading strategies capture defense revenue shocks on the exact trading morning they become visible to capital markets.
Multi-Source Disclosure Cross-Referencing: Ethics, Lobbying, and Board Overlaps
While individual public record streams provide valuable domain-specific data points, the highest-conviction signals in quantitative research emerge from multi-source cross-referencing. When multiple independent statutory reporting systems illuminate the same corporate entity simultaneously, the resulting convergence carries exponentially higher statistical significance than isolated transaction reports.
For a hedge fund data engineer, constructing an integrated cross-signal infrastructure requires linking disparate relational tables through unified point-in-time entity identifiers. Within an institutional data architecture, six distinct public data trails are normalized into a unified relational graph:
- Statutory Federal Procurement Obligations: Transaction-level prime contract awards and bilateral contract modifications over $1,000,000, tracking obligated capital, awarding agencies, and performance locations across 650,000+ transaction records.
- Pre-Award Procurement Notices: Formal pre-award solicitations, single-source justifications, and intent-to-award notices published across defense and civilian procurement offices, capturing early demand pipelines.
- Daily Defense Contract Announcements: Daily procurement releases capturing major defense contract actions, contract ceiling expansions, and option exercise milestones across 38,000+ historical bulletins.
- Corporate Lobbying Disclosures: Quarterly lobbying expenditure reports filed under the Lobbying Disclosure Act (LDA), capturing total expenditures, specific legislative issue codes, targeted congressional committees, and revolving-door registrations of former government officials.
- Congressional Stock Trading Disclosures: Periodic transaction reports filed by members of the United States Senate and House of Representatives under the STOCK Act of 2012, cataloging personal equity transactions, disclosure latencies, and committee oversight assignments across 50,000+ verified trade rows.
- Insider Trading and Executive Governance Networks: Corporate insider transactions (Section 16 reports), officer appointments, director board seats, and major institutional shareholdings across 21,000+ cataloged corporate persons and 11,000+ legal entities.
| Data Trail | Primary Entity Link | Temporal Anchor | Key Regulatory Reference | Cross-Signal Application |
|---|---|---|---|---|
| Prime Contract Transactions | Contractor UEI / CAGE | published_date (+90d DoD) |
Federal Acquisition Regulation (FAR) | Government revenue exposure mapping |
| Defense Announcements | Vendor Name & Division | announcement_date |
Department of Defense Press Releases | Headline ceiling & option monitoring |
| Congressional Stock Trades | Filer Name / Member ID | disclosure_date |
STOCK Act of 2012 (P.L. 112-105) | Committee oversight overlap analysis |
| Quarterly Lobbying Reports | Registrant & Client Name | dt_posted |
Lobbying Disclosure Act (2 U.S.C. § 1601) | Regulatory friction & policy push tracking |
| Executive Insider Trades | Reporting Owner CIK | filed_at |
Securities Exchange Act of 1934 (Sec. 16) | Internal executive sentiment alignment |
| Bid Protest Filings | Protester / Intervenor | filed_date |
Government Accountability Office (GAO) | Contract award dispute & backlog risk |
When an entity resolution pipeline links these tables to standard equity tickers, quantitative researchers can execute high-conviction relational queries: identifying instances where corporate insider accumulation aligns with surges in quarterly lobbying expenditures, followed by major federal defense awards and subsequent congressional disclosure filings. Rather than relying on speculative narratives, quantitative models evaluate verified public paper trails across independent regulatory frameworks.
Accuracy Verification and Sampling Gates: The 95% Precision Protocol
In enterprise data engineering, automated pipelines frequently boast high ingestion throughput while silently accumulating high error rates. In quantitative finance, however, data quality is an absolute constraint: feeding unverified machine-generated mappings into a trading algorithm introduces toxic tracking error and model decay.
To ensure production reliability, an institutional alternative data pipeline must enforce rigorous automated quality assurance gates. Under institutional data governance policies, no record type or entity-resolved dataset is permitted to ship to quantitative production environments unless it passes an empirical sampled accuracy gate of at least 95.0% precision against original public source documents.
The verification protocol operates via stratified random sampling:
- Randomized Blind Sampling: For each active record type, a sample of 200 records is randomly drawn from the production candidate tables across varied temporal windows, agency branches, and ticker capitalizations.
- Dual-Analyst Independent Audit: Two independent data quality reviewers perform manual verification of each sampled row, comparing database fields (entity name, matched ticker, activity date, publication timestamp, and financial values) directly against the original government source filing (such as the PDF disclosure document or official statutory web register).
- Strict Pass/Fail Scoring: If a record maps to an incorrect ticker, fails to account for a historical corporate reorganization, or displays a corrupted financial value, it is scored as a failure. A record is only scored as passing if every single factual attribute matches the underlying public document exactly.
In the latest comprehensive precision audit completed on October 23, 2026, 10 out of 10 core institutional record types passed the 95.0% accuracy gate:
| Record Type | Target Domain | Sample Size | Verified Correct | Sampled Precision | Audit Status |
|---|---|---|---|---|---|
Corporate Officer Links (officer_of) |
Corporate Governance | 200 | 198 | 99.0% | PASS (Exceeds 95.0%) |
Corporate Director Links (director_of) |
Board Governance | 199 | 195 | 98.0% | PASS (Exceeds 95.0%) |
Major Insider Links (insider_of) |
Beneficial Ownership | 197 | 195 | 99.0% | PASS (Exceeds 95.0%) |
Subcontractor Links (subcontractor_of) |
Supply Chain Mapping | 200 | 192 | 96.0% | PASS (Exceeds 95.0%) |
Congressional Trades (congress_trade) |
Legislative Disclosures | 172 (checkable) | 168 | 97.7% | PASS (Exceeds 95.0%) |
Corporate Insider Trades (insider_trade) |
SEC Section 16 Insider Transactions | 200 | 200 | 100.0% | PASS (Exceeds 95.0%) |
Corporate Lobbying Filings (lobbying) |
LDA Statutory Reports | 200 | 192 | 96.0% | PASS (Exceeds 95.0%) |
Federal Contracts (contract) |
Procurement Obligations | 196 (checkable) | 193 | 98.5% | PASS (Exceeds 95.0%) |
Pre-Award Notices (preaward) |
Procurement Solicitations | 198 | 192 | 97.0% | PASS (Exceeds 95.0%) |
Bid Protests (bid_protest) |
GAO Dispute Dockets | 200 | 194 | 97.0% | PASS (Exceeds 95.0%) |
Enforcing this empirical 95.0% precision floor guarantees that quantitative researchers receive high-conviction, institutionally verified data inputs, eliminating the risk of algorithmic distortion from dirty unstructured records.
Known Pipeline Weaknesses, Unlisted Entities, and Survivorship Boundaries
True institutional engineering demands complete scientific transparency regarding dataset boundaries and known weaknesses. A reliable alternative data provider does not conceal pipeline limitations; rather, it documents them with mathematical precision so that quantitative risk managers can calibrate their exposure models accordingly.
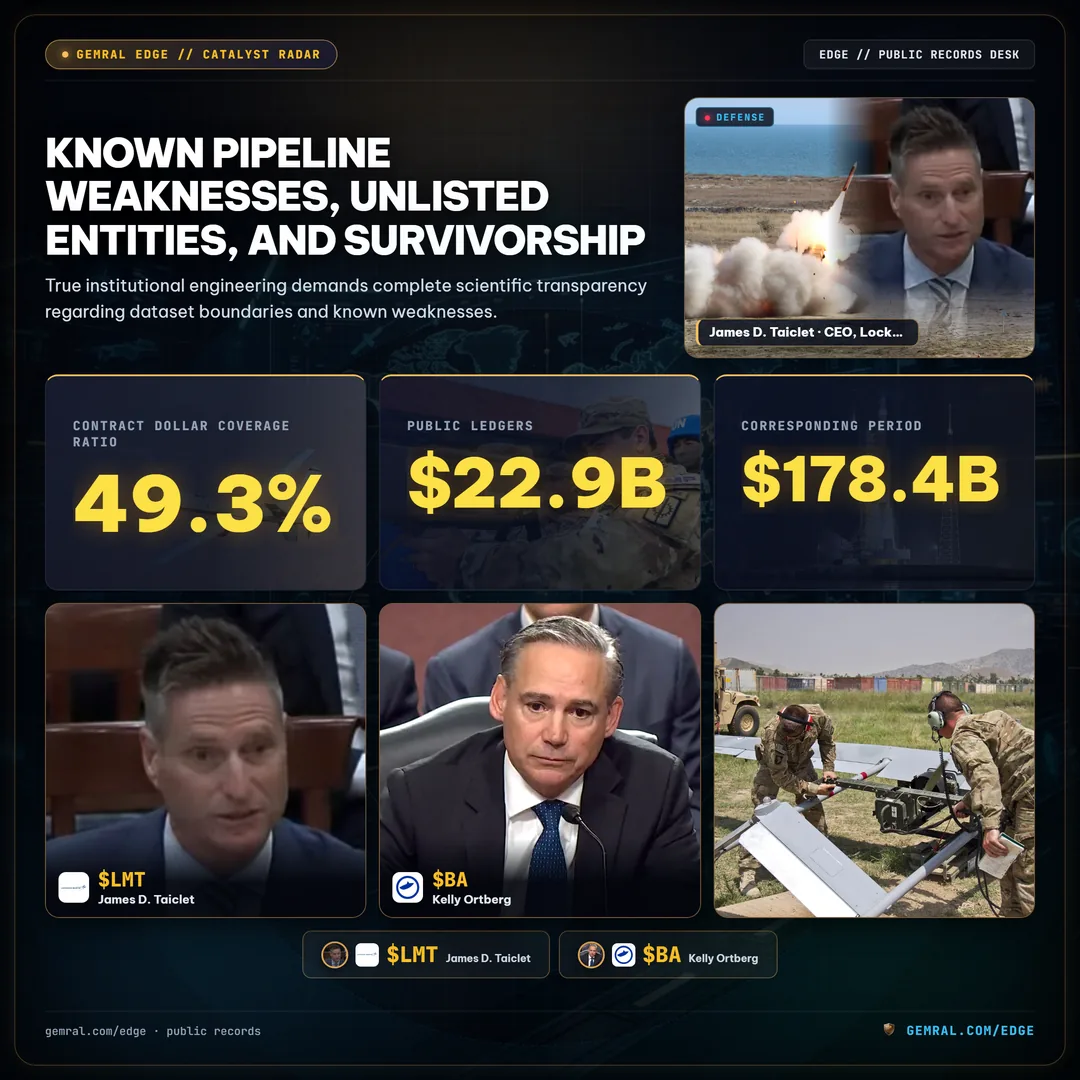
Within the Point-in-Time Public Records Feed, three distinct structural boundaries are documented and measured:
- Contract Dollar Coverage Ratio (49.3%): Total federal contract spending spans hundreds of billions of dollars annually. Across 269,288 prime federal contract transaction rows of $1,000,000 or more cataloged since FY2018, exactly 49.3% of total contract dollars have been resolved to publicly listed corporate equity tickers (measured October 23, 2026). The remaining 50.7% of federal contract spending flows into private enterprises, defense consortiums, non-profit institutions, national research laboratories, universities, and foreign state-owned entities that do not issue public equity. Quantitative models evaluating federal revenue exposure must explicitly model this unlisted universe to avoid conflating total government expenditure with listed equity revenue.
- FY2026 Fourth-Quarter Defense Reporting Gap (~$155 Billion): Due to the statutory 90-day reporting delay enforced on Department of Defense contract actions, federal procurement ledgers exhibit a temporary lag during late-fiscal-year reporting. For July through September of FY2026, defense contract obligations on public ledgers totaled $22.9 billion, compared to $178.4 billion during the corresponding period of FY2025. This reflects an estimated temporary reporting gap of approximately $155 billion (~20% of annual federal procurement) that will be systematically backfilled as statutory quarterly archive releases are processed in November 2026 and January 2027.
- Bid Protest Unlisted Volume (13,850 Records): The Government Accountability Office (GAO) bid protest registry catalogs formal legal challenges brought by disappointed bidders on federal contracts. Across 13,850 historical bid protests filed between September 2018 and October 2026, a substantial proportion involve small privately held defense contractors competing for specialized local awards. While large publicly traded primes (such as Lockheed Martin, Boeing, and General Dynamics) represent major protest participants, analysts must filter by
listed_parent_id IS NOT NULLwhen constructing equity-specific dispute factor signals.
| Dataset Boundary | Observed Metric Value | Measurement Timestamp | Structural Cause | Quant Mitigation Protocol |
|---|---|---|---|---|
| Contract Dollar Coverage | 49.3% of $1M+ obligations mapped to tickers | October 23, 2026 | Non-profit, private & university awards | Filter factor exposure by listed coverage; do not treat unmapped spending as missing data. |
| FY2026 Q4 Defense Gap | ~$155 Billion temporary reporting delay | October 19, 2026 | Statutory 90-day DoD embargo | Apply statutory lag rolling windows; ingest scheduled quarterly archives in Nov/Jan. |
| Bid Protest Coverage | 13,850 total protest dockets | October 19, 2026 | Small private bidder dispute volume | Query with listed_parent_id IS NOT NULL to isolate public contractor litigation. |
Institutional Delivery Architecture: Columnar Parquet Schemas, DDQ, and Evaluation Workflow
For an institutional data sourcing team or quantitative engineering group, data delivery mechanics are just as vital as data quality. Enterprise hedge funds, systematic macro funds, and multi-manager platforms do not consume multi-gigabyte alternative datasets through rate-limited graphical web interfaces or fragmented REST scrapers. They demand clean, standardized, high-performance data packaging designed for immediate integration into production research clusters.
The Point-in-Time Alternative Data architecture delivers through standardized, production-grade formats:
- Columnar Apache Parquet Architecture: Datasets are partitioned by publication calendar date and distributed as optimized Snappy-compressed Apache Parquet files. Parquet's columnar storage allows quantitative researchers to query specific feature columns (such as
ticker_asof,published_date, andnormalized_amount) across hundreds of thousands of rows in milliseconds, with zero deserialization overhead in Python (Polars/Pandas), C++, or DuckDB. - Cryptographic Data Integrity: Every standardized sample pack and production delivery partition is accompanied by a cryptographic SHA-256 verification manifest, documenting exact row counts, file byte lengths, and table checksums to ensure zero bit-level corruption during transmission.
- Production Wave 1 Sample Pack: The standardized Wave 1 Institutional Delivery Pack (identifier
wave1-2026-10-24-185224) provides comprehensive point-in-time coverage across 300 core equity tickers, encompassing 158 compressed Parquet files, 24 relational tables, and 786,636 verified transaction rows (including 224,090 resolved events, 188,873 contract transactions, 11,978 defense announcements, 13,204 congressional trades, and 4,317 lobbying filings). - Institutional Compliance & Due Diligence Questionnaire (DDQ): Institutional data onboarding requires rigorous compliance verification. To streamline vendor review, an institutional Data Due Diligence Questionnaire (DDQ) is provided covering legal entity formation, beneficial ownership, data provenance, regulatory compliance (FAR, FOIA, STOCK Act, LDA), privacy standards, and information security safeguards.
- Standardized Licensing Terms: Data licensing for fund internal use is structured under a 12-month commercial agreement, incorporating full point-in-time historical data in year one, quarterly invoicing schedules, and multi-seat access. In compliance with institutional policies, fund licensing terms and pricing are provided upon request via direct institutional correspondence.
| Institutional Artifact | Delivery Mechanism | Technical Specifications | Verification Standard | Access Protocol |
|---|---|---|---|---|
| Wave 1 Parquet Sample Pack | Private secure link (14-day expiry) | 158 Parquet files, 24 tables, 786,636 rows | SHA-256 manifest & row verification | Available upon verified institutional request |
| Due Diligence Questionnaire (DDQ) | Encrypted document dispatch | Comprehensive institutional compliance profile | Legal vendor profile audited | Sent with every sample pack |
| Technical Methodology Notebooks | Jupyter / Python / DuckDB scripts | Point-in-time simulation templates & schemas | Self-contained reproducible execution | Bundled within sample pack delivery |
| Enterprise REST API & Webhooks | TLS 1.3 REST v1 endpoints | High-throughput streaming JSON feeds | HMAC-SHA256 signature verification | Provisioned under active API licensing |
To evaluate the Point-in-Time Public Records Feed for quantitative factor research, institutional data sourcing teams and quantitative engineers may request a dedicated Wave 1 Parquet sample pack and institutional DDQ through the institutional data portal: Wave 1 Sample Pack Access.
For academic researchers and quantitative engineering teams requiring direct empirical access, historical telemetry bundles can be reviewed through the Empirical Entity Resolution Telemetry Dataset repository. By providing reproducible Parquet schemas, effective-dated corporate hierarchies, and deterministic quality assurance gates, the framework establishes an open, verifiable foundation for quantitative alternative data research.
Data Source: Statutory Federal Procurement Registries, Congressional Disclosures, SEC Filings, and Gemral Edge Research Desk.
Frequently asked questions
What is the primary responsibility of a hedge fund data engineer handling alternative data?
A hedge fund data engineer specializes in ingesting, cleaning, normalizing, and structuring unstructured and semi-structured alternative datasets—such as government procurement records, congressional disclosures, and environmental filings—into bitemporal point-in-time schemas that quantitative researchers can safely utilize in historical factor models without data leakage.
How does entity resolution prevent look-ahead bias in quantitative factor models?
Entity resolution prevents look-ahead bias by mapping records to the corporate parent and ticker symbol valid on the precise publication date rather than retroactively backfilling modern parent-company structures. If an acquired subsidiary won a contract in 2019 prior to being acquired in 2020, backfilling the modern parent's ticker into 2019 data leaks future acquisition information into historical simulation.
Why must defense contract actions incorporate a 90-day publication lag?
Federal defense procurement actions are subject to statutory publication delays, where contract awards are only made public after a standard 90-day lag. A hedge fund data engineer must separate the internal signing date (activity date) from the public disclosure date, ensuring quantitative factor simulations evaluate only on the date the broader market could legitimately observe the record.
What accuracy threshold is required for institutional alternative data pipelines?
Institutional quantitative funds typically require a minimum sampled precision threshold of 95.0% across all entity-resolved record types, verified through randomized dual-analyst manual audits comparing database fields against original public documents before datasets are promoted to production.