Alternative Data Sources: How Quantitative Desks Evaluate Point-in-Time Public Records vs Commercial Vendor Feeds
A quantitative data engineering audit comparing point-in-time public records with commercial vendor feeds across bitemporal timestamps, multi-tier subsidiary entity resolution, and survivorship-bias mitigation.
The systematic deployment of alternative data sources has evolved from an experimental strategy into a core infrastructure requirement for systematic hedge funds, quantitative desks, and institutional asset allocators. As traditional market feeds, sell-side earnings consensus estimates, and standard financial accounting metrics become increasingly commoditized, quantitative research groups seek predictive informational advantages from primary government registries, regulatory disclosures, and physical tracking datasets. These non-traditional data streams capture real corporate cash flows and policy tailwinds weeks or months before financial statements are certified and published.
However, evaluating alternative data sources requires rigorous quantitative validation rather than reliance on headline vendor claims. When institutional researchers integrate raw commercial datasets into historical simulations, they regularly encounter structural defects: survivorship bias from delisted tickers, uncorrected retroactive amendments, and severe look-ahead bias caused by mixing event occurrence dates with true public disclosure timestamps. Understanding how to structure primary government records into a point-in-time bitemporal feed is the defining challenge of modern quantitative infrastructure. For an operational breakdown of institutional quantitative workflows, review our dedicated guide on Alternative Data for Hedge Funds.
Alternative Data Sources: The Point-in-Time Architecture Driving Institutional Research
The term alternative data sources encompasses datasets generated outside traditional accounting repositories and exchange price-quote feeds. In quantitative finance, these data categories include credit card transaction panels, geolocation satellite imagery, supply-chain bill of lading records, and government administrative disclosures. While commercial vendor feeds frequently offer aggregated indices or proprietary momentum scores, quantitative engineering desks require primary, verifiable public records that map directly to corporate capital allocations.
The fundamental difference between commercial vendor feeds and primary public datasets lies in data provenance and temporal fidelity. Commercial vendor aggregators frequently supply point-in-time estimates that overwrite historical rows whenever a corporate entity reclassifies past records or updates corporate structures. In contrast, institutional research infrastructure maintains a strict point-in-time architecture where every database record reflects exactly what was publicly knowable at an exact microsecond in market history.
Across a historical dataset covering 850,000+ resolved events and 4,745 distinct tickers, maintaining point-in-time fidelity ensures that historical simulations do not execute simulated trades on information that was legally withheld, administratively delayed, or retroactively modified months later. To examine the empirical scope of this historical coverage across corporate universes, review the Gemral Edge Data Coverage portal.
| Architecture Dimension | Commercial Vendor Feed Aggregators | Institutional Point-in-Time Public Records |
|---|---|---|
| Temporal Schema | Single transaction date, retroactive overwrites common | Bitemporal timestamps (Valid Time vs Ingestion Time) |
| Corporate Entity Resolution | Static current parent entity mapping (survivorship bias) | Historical subsidiary hierarchy linked as of publication date |
| Data Provenance | Proprietary score or black-box aggregated index | Direct primary public disclosure with statutory audit trail |
| Look-Ahead Control | Zero statutory delay adjustment (mixes signing and release) | Statutory publication delay offsets strictly enforced |
| Audit Delivery Format | Proprietary dashboards, web UI exports, or locked JSON | Standard columnar Parquet files with SHA-256 manifests |
Entity Resolution Mechanics: Connecting Federal Disclosures to Corporate Equity Tickers
The primary obstacle to operationalizing government alternative data sources is entity resolution. Government procurement repositories and legislative filings are designed for administrative oversight and statutory compliance, not capital market data consumption. When government agencies obligate capital or receive disclosure forms, records do not cite standard financial identifiers such as CUSIP, ISIN, FIGI, or Bloomberg open tickers.
Instead, public registries identify contracting counterparties via Commercial and Government Entity (CAGE) codes, Unique Entity Identifiers (UEI), and legal subsidiary names. A major defense or aerospace prime contractor typically operates more than 350 active CAGE codes representing individual fabrication shipyards, engineering facilities, and specialized operating units across multiple states. For an empirical case study examining how unlisted corporate subsidiaries distort equity historical modeling, inspect our research on Companies with Government Contracts Case Study.
In institutional resolution pipelines, entity attribution links 659 federal contract actions that were signed before corporate acquisitions closed but published after the effective transaction date. Under a naive current-parent lookup, these transactions either link to extinct tickers or falsely assign revenue to parent companies months before closing. Within our validated universe, 651 of these transactions accurately rolled to listed acquirers on their publication dates, while 8 unlisted acquirers correctly retained null ticker assignments to prevent false trade generation. Furthermore, 254 contract actions where the parent corporation transitioned ticker symbols between award signature and public release carry the exact active trading symbol valid on the release timestamp.
Entity Resolution Pipeline Schema (PySpark / SQL Representation)
-- Resolving raw administrative identifiers to equity tickers at publication time
SELECT
    t.transaction_id,
    t.uei,
    t.cage_code,
    t.recipient_name,
    t.action_date,
    t.published_at,
    COALESCE(sub.parent_entity_id, ent.entity_id) AS resolved_entity_id,
    tick.ticker_symbol AS point_in_time_ticker,
    tick.exchange_code
FROM edge_contract_transactions t
LEFT JOIN edge_entity_identifiers ent
    ON t.uei = ent.uei_code
LEFT JOIN edge_subsidiary_relationships sub
    ON ent.entity_id = sub.subsidiary_entity_id
    AND t.published_at >= sub.effective_start_date
    AND t.published_at < COALESCE(sub.effective_end_date, '9999-12-31')
JOIN edge_ticker_mappings tick
    ON COALESCE(sub.parent_entity_id, ent.entity_id) = tick.entity_id
    AND t.published_at >= tick.valid_from
    AND t.published_at < COALESCE(tick.valid_to, '9999-12-31')
WHERE t.action_amount >= 1000000;
Federal Contract Records: Quantifying Corporate Revenue Signals from Government Procurement
Among all categories of government alternative data sources, federal procurement contract obligations represent the largest verifiable dollar volume. Civilian federal agencies and the Department of Defense allocate more than $750 billion annually through procurement contracts. For quantitative strategies, tracking contract modifications, definitive contracts, and purchase orders provides empirical visibility into forward commercial revenues and multi-year order backlogs.
The procurement dataset comprises 650,000+ federal contract transactions across 4,745 corporate entities. A 3% block sample of contract actions exceeding $1,000,000 since fiscal year 2018 demonstrates that defense procurement represents approximately 59% of transaction rows and 65% of total obligated dollars. Tracking these awards requires separating civilian obligations—which typically appear in public repositories within 3 to 14 days of signature—from defense procurement actions, which are governed by statutory national security disclosure delays.
To capture early contracting signals before quarterly reports are drafted, quantitative workflows cross-reference formal procurement databases with 38,000+ daily contract announcements published by the Department of Defense. For 9,158 defense contracts appearing in both daily announcements and formal award registries since fiscal year 2018, the daily contract announcement precedes formal database posting by a median of 90 days across $1.07 trillion in announced award value. Integrating these two public streams creates an early, verified quantitative view of government procurement allocations.
Bitemporal Schema Design: Eliminating Look-Ahead Bias Across Statutory Publication Windows
The single most frequent point of failure in quantitative alternative data historical evaluation is the conflation of event occurrence dates with information publication dates. In financial data engineering, this failure mode introduces severe look-ahead bias: a quantitative simulation assumes a trading model bought an asset on Tuesday based on a contract modification signed on Tuesday, even though the public procurement registry did not publish the record until Friday.
To eliminate this systematic distortion, institutional feeds operate on a strict bitemporal schema. Every record maintains two independent temporal coordinates: Valid Time (the real-world date the event occurred, such as the contract signature date or stock transaction date) and Transaction Time / Ingestion Time (the exact timestamp when the record became publicly accessible in official federal repositories).
| Disclosure Stream | Primary Public Source | Statutory or Observed Publication Lag | Look-Ahead Mitigation Rule |
|---|---|---|---|
| Defense Procurement Contracts | Federal Procurement Data Repositories | 90-day statutory delay for military agency entries | Ingest Daily Announcements at Day 0, Award Records at Day +90 |
| Congressional Stock Trades | House & Senate Financial Disclosures (STOCK Act) | Median 27 days, 90th percentile 63 days | Timestamp model execution strictly on public disclosure filing date |
| Corporate Insider Transactions | Regulatory Ownership Disclosures | Median 1 day, 90th percentile 4 days | Join models on submission filing timestamp, not execution date |
| Senate Lobbying Filings (LDA) | Senate Office of Public Records Registrations | Median 20 days, 90th percentile 21 days post-quarter end | Release signals only upon completed public indexation |
If a quantitative model were to evaluate congressional stock transactions using transaction dates rather than filing dates, simulated trades would execute 27 days before the public could know the trade occurred. Similarly, evaluating defense contracts on the signature date executes trades 90 days before the public record appears. Our point-in-time architecture strictly enforces publication timestamps across all 850,000+ historical events.
Cross-Signal Confluence: Merging Congressional Disclosures, Lobbying Filings, and Insider Transactions
While individual alternative data feeds provide isolated indicators, the most robust quantitative signals emerge from cross-signal confluence—where multiple independent public records corroborate corporate developments across different regulatory domains.
Our consolidated database indexes 50,000+ congressional trade disclosures, 35,000+ corporate insider trade records, and extensive federal lobbying registrations. In institutional models, corporate lobbying expenditures documented under the Lobbying Disclosure Act (LDA) often expand quarters before major procurement opportunities are released for bidding. To explore how institutional allocators track legislative influence and lobbying registrations across corporate sectors, examine our analysis of Senate Lobbying Disclosure Analysis.
Concurrently, congressional disclosure filings frequently intersect with sector-level legislative committee deliberations. When lawmakers serving on armed services or appropriations subcommittees report transactions in aerospace contractors while those same corporations execute major lobbying campaigns, systematic cross-signal models identify measurable institutional interest. For research on multi-participant filing patterns, inspect our report on Cluster Buys in Congressional Stock Filings.
Institutional Precision Benchmarks: Empirical Verification Against Primary Public Records
A recurring risk in alternative data sourcing is vendor hallucination and scraping corruption. Quantitative strategies require mathematical accuracy gates verified through automated sampling against primary public documents before records are released into production pipelines.
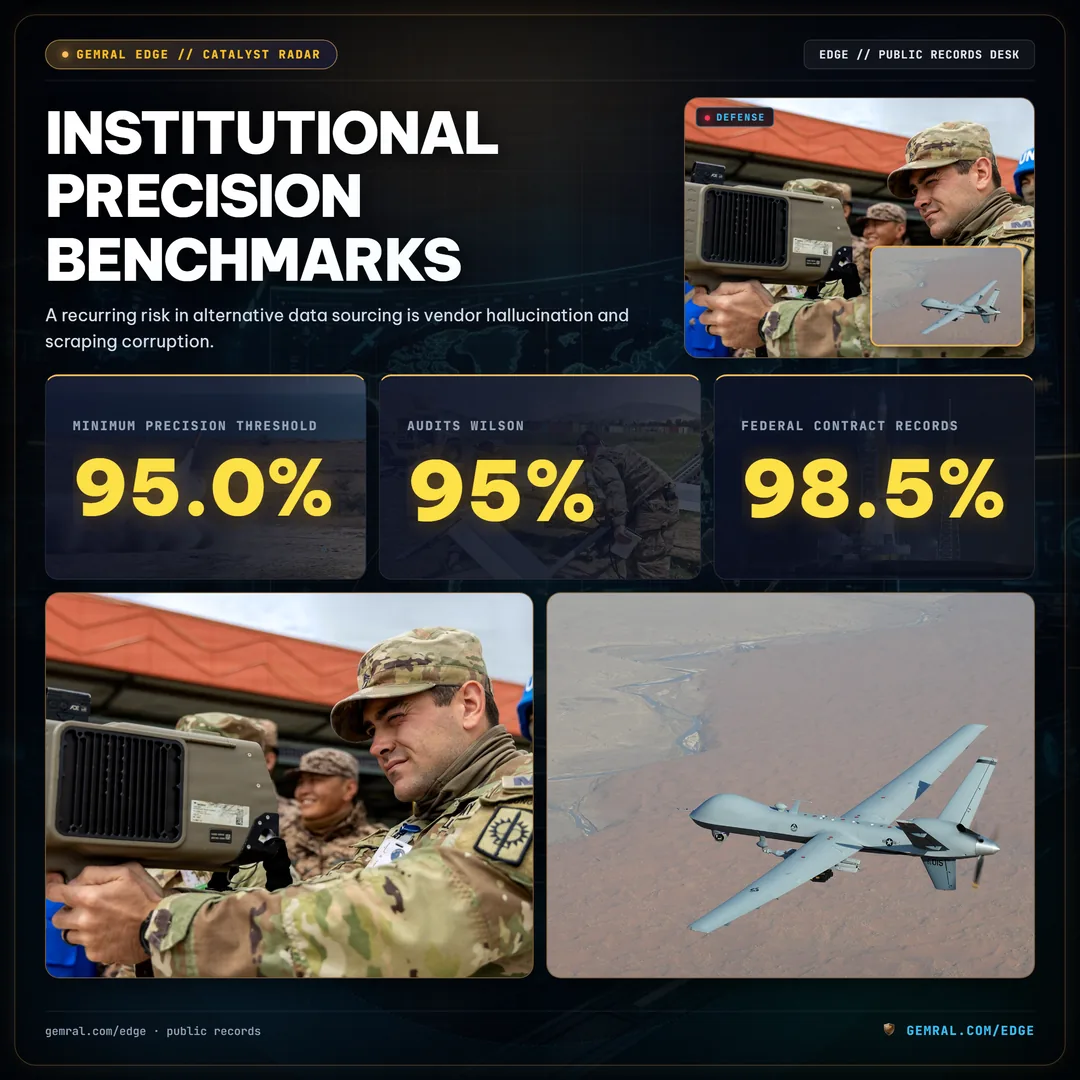
Every public record ingested into the database is evaluated against primary government sources with a minimum precision threshold of 95.0%. Across empirical sampling audits evaluated with Wilson 95% confidence intervals and double-blind grading protocols, historical precision benchmarks demonstrate high structural reliability:
In recent grading batches, all 13 core record types demonstrated precision between 95.6% and 100%. Allocators should note that cumulative precision figures across historical batches are lower for four specific categories (contracts 91.2%, pre-award notices 76.4%, subcontractor links 94.0%, and bid protests 92.5%) because historical figures incorporate early baseline batches processed before our automated entity resolution engine was deployed.
Data Integrity and Coverage Limitations: Documenting Statutory Lags and Private Entity Gaps
Rigorous quantitative institutional research demands transparent documentation of dataset limitations, coverage boundaries, and administrative reporting lags. No alternative data source captures 100% of economic reality, and identifying what a dataset does not contain is essential for proper risk management.
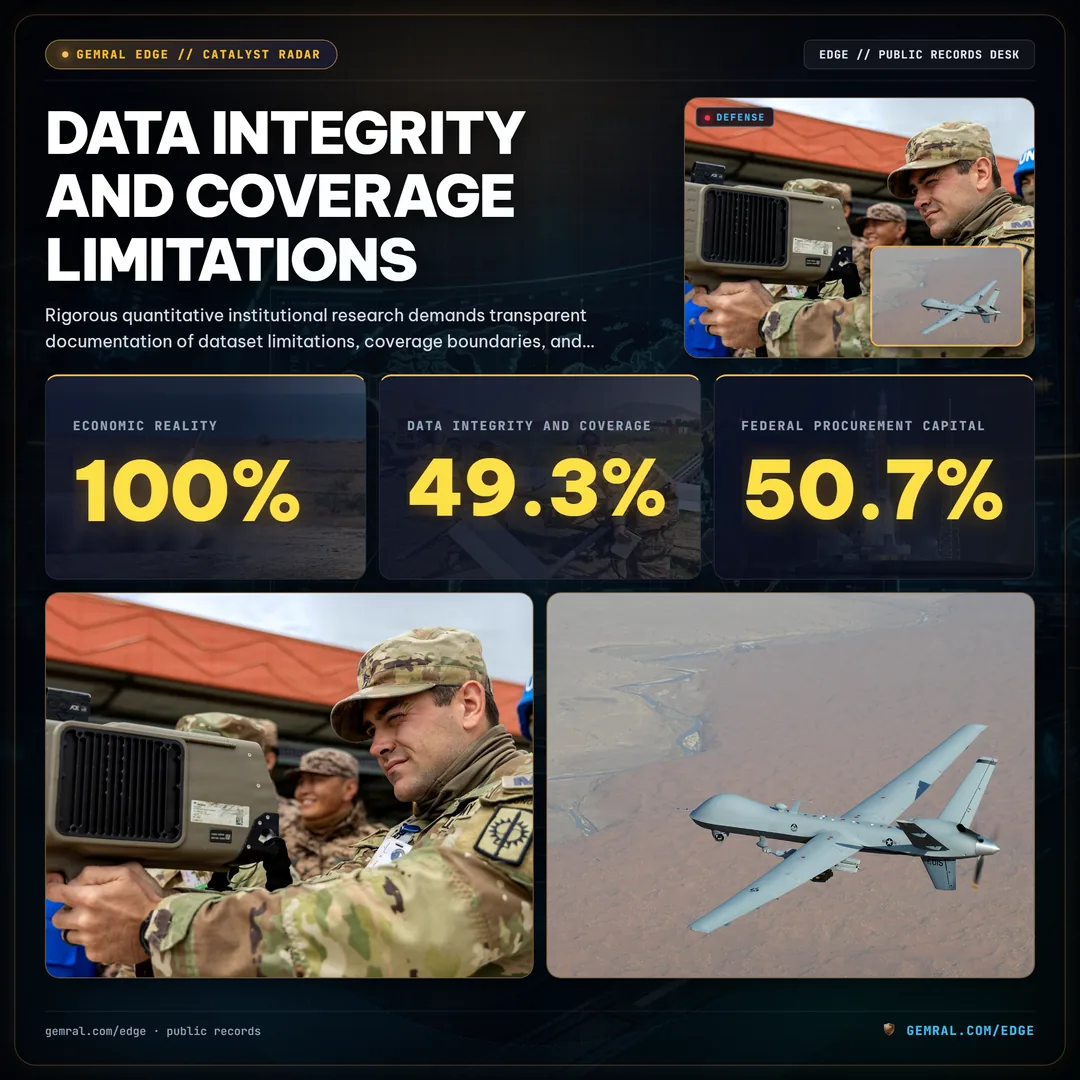
First, regarding contract dollar coverage, approximately 49.3% of federal contract transaction dollars since fiscal year 2018 link to a listed equity ticker. The remaining 50.7% of federal procurement capital is awarded to unlisted private corporations, university research foundations, federally funded research and development centers (FFRDCs), or foreign entities. Quantitative models focusing exclusively on listed equities must account for this structural coverage boundary.
Second, statutory reporting delays create temporary observation gaps. Defense procurement records published by military agencies are subject to a statutory 90-day Pentagon delay. For fourth-quarter fiscal year 2026 data, this statutory holdback leaves approximately $155 billion in defense awards temporarily absent from standard public procurement databases until quarterly reload cycles occur. As established, our ingestion infrastructure bridges this delay by capturing daily defense announcements on publication day.
Third, regarding bid protest records, the database tracks 13,850 bid protests filed with the Government Accountability Office. However, quantitative allocators must note that only 25.3% (3,505 of 13,850) are directly linked to a specific contract transaction and awardee identifier, with statutory decision deadlines matching exactly within 100 calendar days in 61.7% of cases.
Finally, regarding dataset versioning and amendments, our formal revision log started in October 2026. For records created prior to October 2026, amended insider reports and amended House disclosures remain recorded as separate chronological records at their respective filing dates, while amended Senate reports and corrected contract modifications reflect the latest published state.
Institutional Methodology: Evaluating Alternative Data Integrity and Delivery Protocols
For quantitative fund engineering teams conducting formal due diligence on alternative data sources, evaluation protocols should follow a structured three-stage verification process:
- Bitemporal Integrity Verification: Verify that historical rows provide discrete source publication timestamps alongside event execution dates. Inspect the distribution of delta days between execution and publication to confirm that statutory delays are strictly modeled.
- Entity Resolution and Survivor Audit: Audit how delisted, acquired, and renamed corporations are represented across historical timestamps. Confirm that transactions executed by historical subsidiaries resolve to the parent ticker valid on that exact historical trading day, avoiding current-table misattribution.
- Columnar Delivery and Hash Verification: Require delivery via immutable, standardized Parquet files accompanied by cryptographic SHA-256 manifests. This guarantees data provenance and ensures seamless integration with quantitative research clusters.
To test sample tables, review cryptographic file manifests, and execute SQL queries on live point-in-time public records, quantitative desks can access the Data Preview Console. Individual and departmental subscriptions are available through standard pricing tiers: Pro tier at $39 per month, B2B research tier at $299 per month, and institutional API access at $2,000 per month. Fund licensing is quoted on request by email.
Public data · not investment advice · Gemral Edge Quantitative Research Desk · All primary records sourced from public statutory disclosures
Frequently asked questions
What are alternative data sources in quantitative finance?
Alternative data sources are non-market, non-accounting datasets gathered from primary government disclosures, regulatory filings, corporate lobbying records, and physical telemetry that provide quantitative models with early indicators of corporate cash flows, policy tailwinds, and supply chain shifts.
Why is point-in-time architecture critical when evaluating alternative data?
Point-in-time architecture separates the effective event timestamp from the exact system ingestion timestamp, preserving historical data as it was publicly visible at that exact moment. This prevents look-ahead bias and survivorship bias during backtesting by correctly handling retroactive amendments, corporate mergers, and ticker changes.
How does entity resolution impact alternative data quality?
Entity resolution maps primary public records filed under subsidiary names, joint ventures, or unique corporate identification codes to primary parent equity tickers valid on that specific publication date. Without temporal entity resolution, quantitative models systematically miss substantial operational volume dispersed across corporate subsidiaries.
What delivery formats are standard for hedge fund alternative data feeds?
Institutional hedge funds typically ingest alternative data via standardized columnar Parquet files with cryptographic manifests and SHA-256 integrity verification, alongside high-throughput REST APIs and programmatic webhook connectors for continuous operational synchronization.