Critical Mineral Refining Supply Chains and Sovereign Defense Stockpiling Allocations: The 2026 Procurement Shift
在整个主权国防体制中,现代战争与威慑能力从根本上不再受制于软件算法或机身设计蓝图,而是受制于物理冶金学、化学分离动力学以及关键矿产的精炼速度。 在过去的24个月中,西方工业采购周期与高度集中的上游矿产加工基础设施之间的结构性摩擦,已升级为紧迫的国家安全防御焦点。 尽管公共政策讨论通常聚焦于澳大利亚、非洲和美洲的未开采矿产储量,但战略脆弱性依然深植于下游的工业转化枢纽:商业冶炼、湿法冶金溶剂萃取以及高纯度化学分离。
根据对2026年9月的联邦采购文件、国防生产法(DPA)第三章公开信息以及国防后勤局(DLA)战略物资库存的综合分析,美国国防部及盟国各部委已启动自1946年《战略和关键物资储存法》以来规模最大的主权工业资本化计划。 本份综合市场报告重构了全球精炼瓶颈的物理架构,量化了国家国防储备(NDS)不断扩大的交易基金缺口,追踪了紧急双边采购协议的推进速度,并评估了重塑全球冶金股票市场的资本配置动态。
1. 精炼瓶颈:化学分离对决地质开采
A persistent fallacy in commercial mineral reporting is the conflation of geological resource abundance with operational refining throughput. Earth crustal concentration charts published by standard geological surveys suggest substantial deposits of rare earth elements, antimony, titanium, and lithium distributed across North America, Scandinavia, and Oceania. However, modern military hardware does not ingest raw bastnäsite, stibnite, or spodumene ores; weapons platforms demand ultra-pure chemical precipitates, high-purity metal powders, and precision-sintered permanent magnetic alloys.
The core vulnerability of the Western defense industrial base resides in the complex chemical separation stages that convert raw mined concentrates into battery-grade precursors, optical grade elements, and structural alloys. Rare earth processing, in particular, requires sequential multi-stage liquid-liquid counter-current solvent extraction circuits involving hundreds of mixer-settler tanks and hazardous chemical reagents to separate chemically similar lanthanides such as Neodymium (Nd), Praseodymium (Pr), Dysprosium (Dy), and Terbium (Tb). While mining permits in Western jurisdictions frequently face decades of environmental litigation and regulatory delay, the capital expenditure and technical know-how required to engineer, calibrate, and operate continuous commercial separation trains has concentrated overwhelmingly in East Asia.
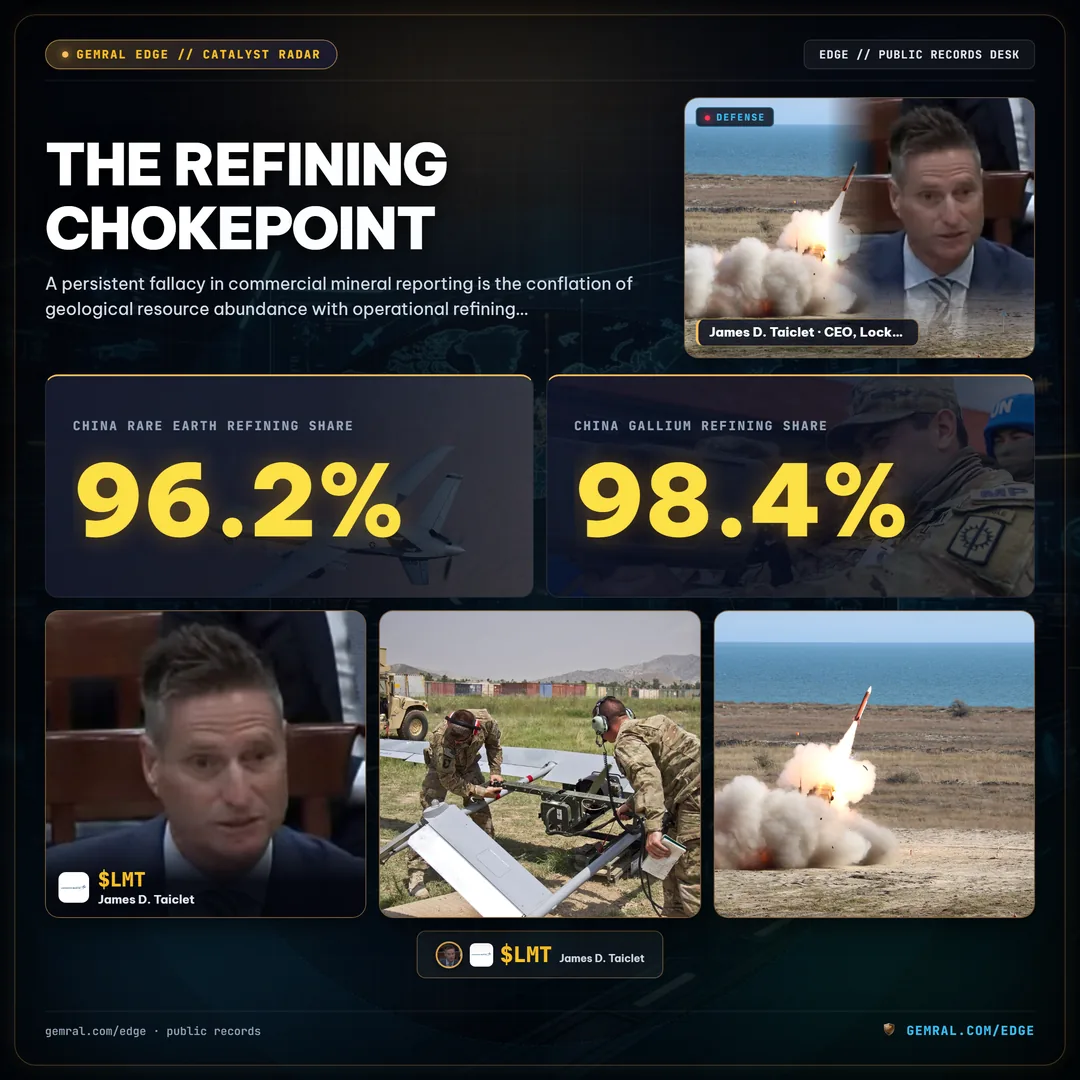
As documented in Figure 1, the concentration ratio for downstream chemical refining exceeds mining concentration across every strategic defense category. For heavy rare earths—essential for maintaining magnetic coercivity in high-temperature permanent magnet electric motors powering guided missile actuators, naval propulsion drives, and jet engine generators—China maintains an estimated 96.2% global refining market share. For gallium, which forms the substrate of advanced Gallium Nitride (GaN) active electronically scanned array (AESA) radar transmit-receive modules, refining dominance reaches 98.4%. Even for commodities with diversified mining footprints like cobalt and synthetic graphite, chemical conversion into battery cathode precursors and purified spherical graphite anode materials remains concentrated above 76% and 92% respectively.
2. 国家国防储备资本动态:逆转数十年的清算趋势
To understand the current urgency within the Pentagon Office of Industrial Base Policy, one must examine the multi-decade trajectory of the National Defense Stockpile (NDS). Established under the Strategic and Critical Materials Stock Piling Act of 1946, the NDS maintained physical commodities valued at approximately $4.2 billion during the height of the Cold War, calibrated to sustain a three-year multi-theater conventional conflict without reliance on foreign shipping corridors or adversarial supply lines.
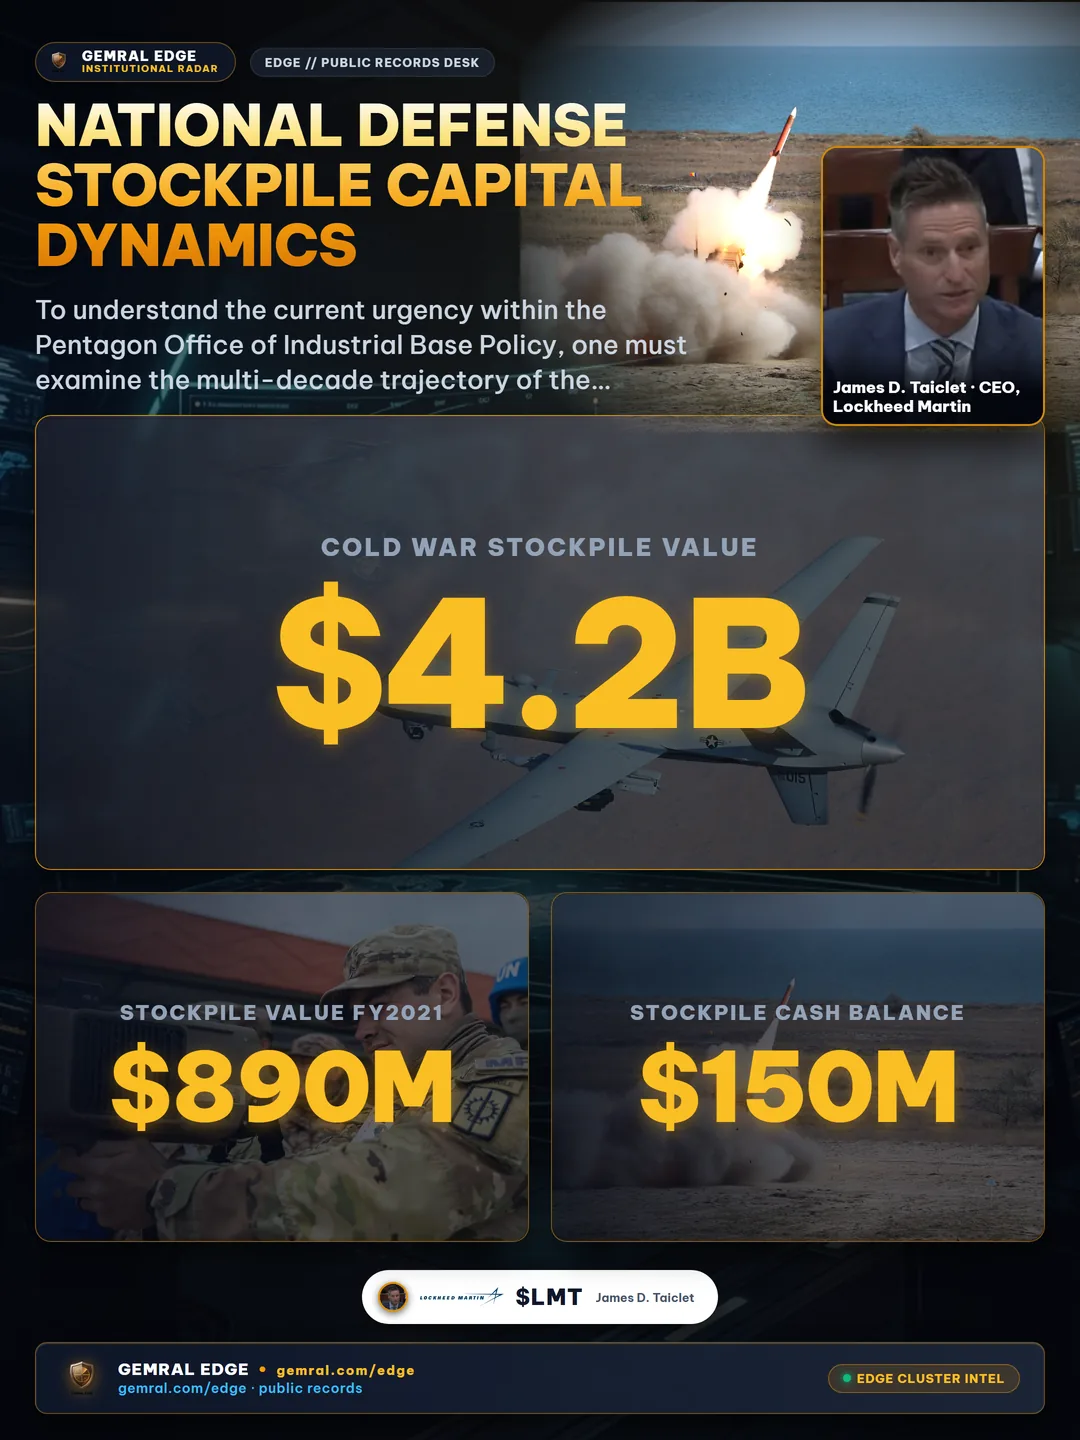
Following the dissolution of the Soviet Union in 1991, successive administrations treated the NDS not as an active national security reserve, but as an off-budget liquidatable asset. Between 1993 and 2018, Congress systematically mandated the disposal and commercial sale of critical defense stockpiles to fund military healthcare programs, highway construction trust funds, and general revenue shortfalls. Physical inventories of battery-grade cobalt, high-purity antimony, metallurgical manganese, and refined tungsten were systematically liquidated on commercial markets at historical cyclical troughs. By fiscal year 2021, the market valuation of the physical stockpile had collapsed to less than $890 million, with available transaction cash balances dropping below $150 million.
The legislative inflection point materialized in the National Defense Authorization Acts (NDAA) for Fiscal Years 2024 through 2026. Recognizing that the stockpile held less than 30 days of supply for several conflict-critical elements under high-intensity combat expenditure rates, Congress authorized expanded multi-year procurement authority. However, as illustrated in Figure 2, an acute gap persists between statutory acquisition authority and actual Treasury cash disbursements. While the authorized procurement horizon targets a restored physical asset inventory of $2.25 billion by FY2027, the current NDS transaction fund balance stands at $1.84 billion, leaving a cumulative $1.24 billion capital deficit relative to the Defense Logistics Agency (DLA) wartime requirement model of $2.40 billion.
3. 国防生产法第三章:工业资本干预
In response to legislative funding friction in the traditional stockpile budget, the Pentagon has utilized the Defense Production Act (DPA) Title III as its primary vehicle for emergency domestic industrial co-investment. Unlike standard Department of Defense procurement contracts that buy finished end-items like aircraft or munitions, Title III grants the Executive branch broad authority to issue direct capital grants, loans, purchase commitments, and price floor guarantees to establish, expand, or preserve domestic industrial processing facilities.
Public contract award registries under Title III indicate that between October 2023 and September 2026, the Department of Defense obligated in excess of $1.002 billion across six targeted critical mineral categories. This intervention represents a fundamental pivot from passive market procurement to active sovereign market architecture.
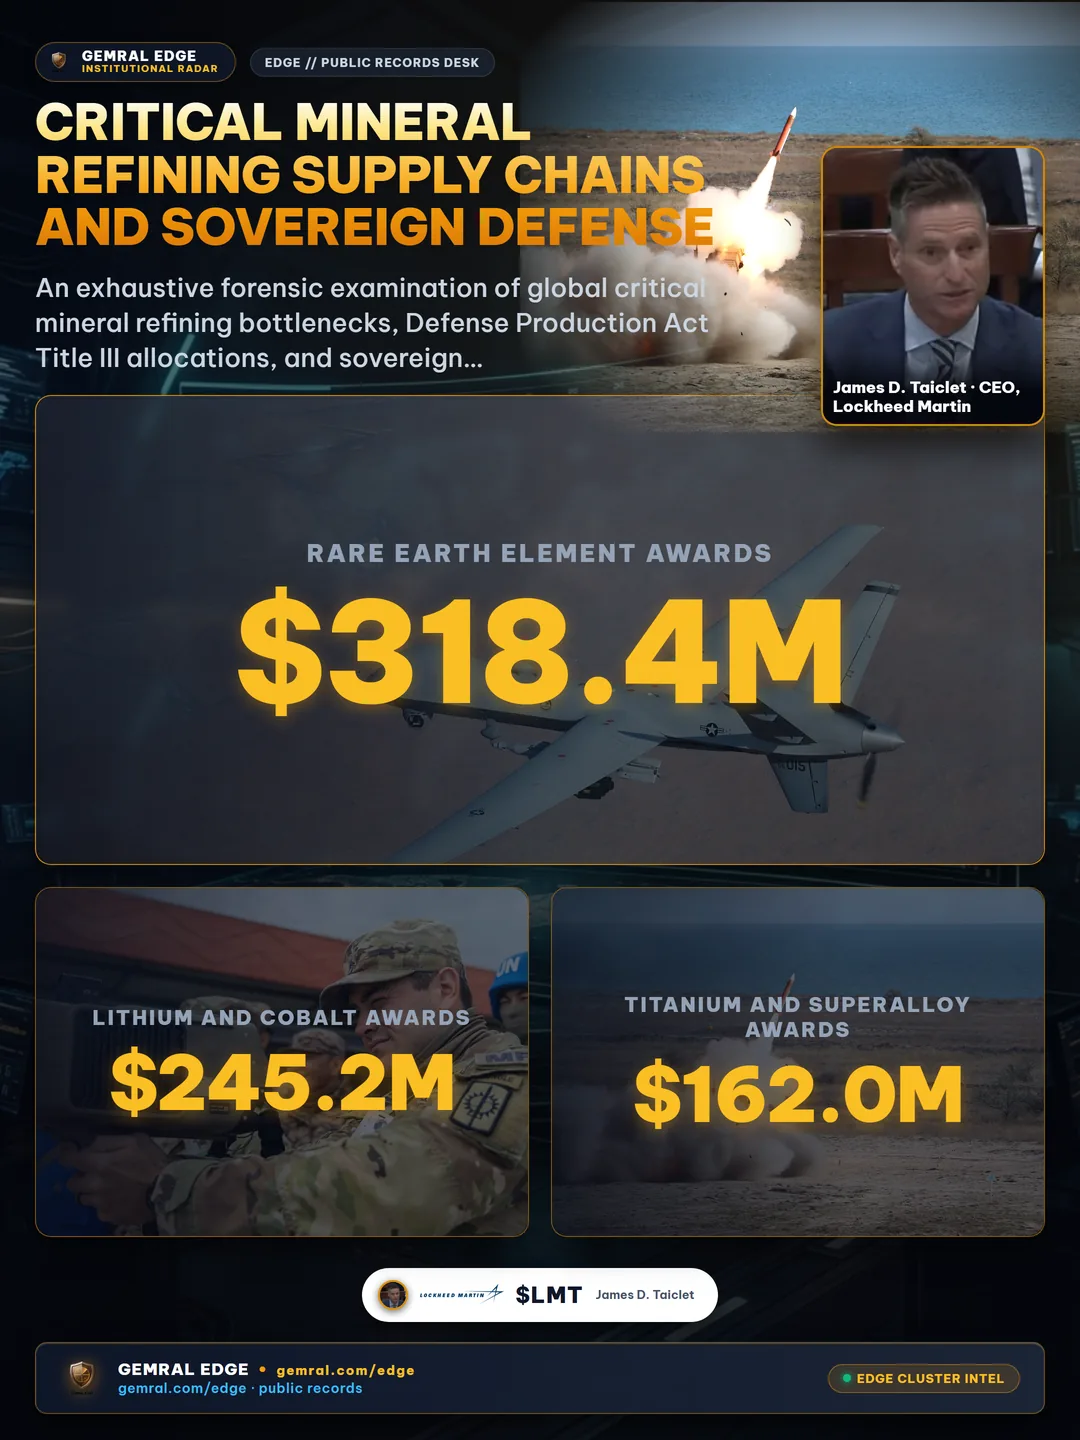
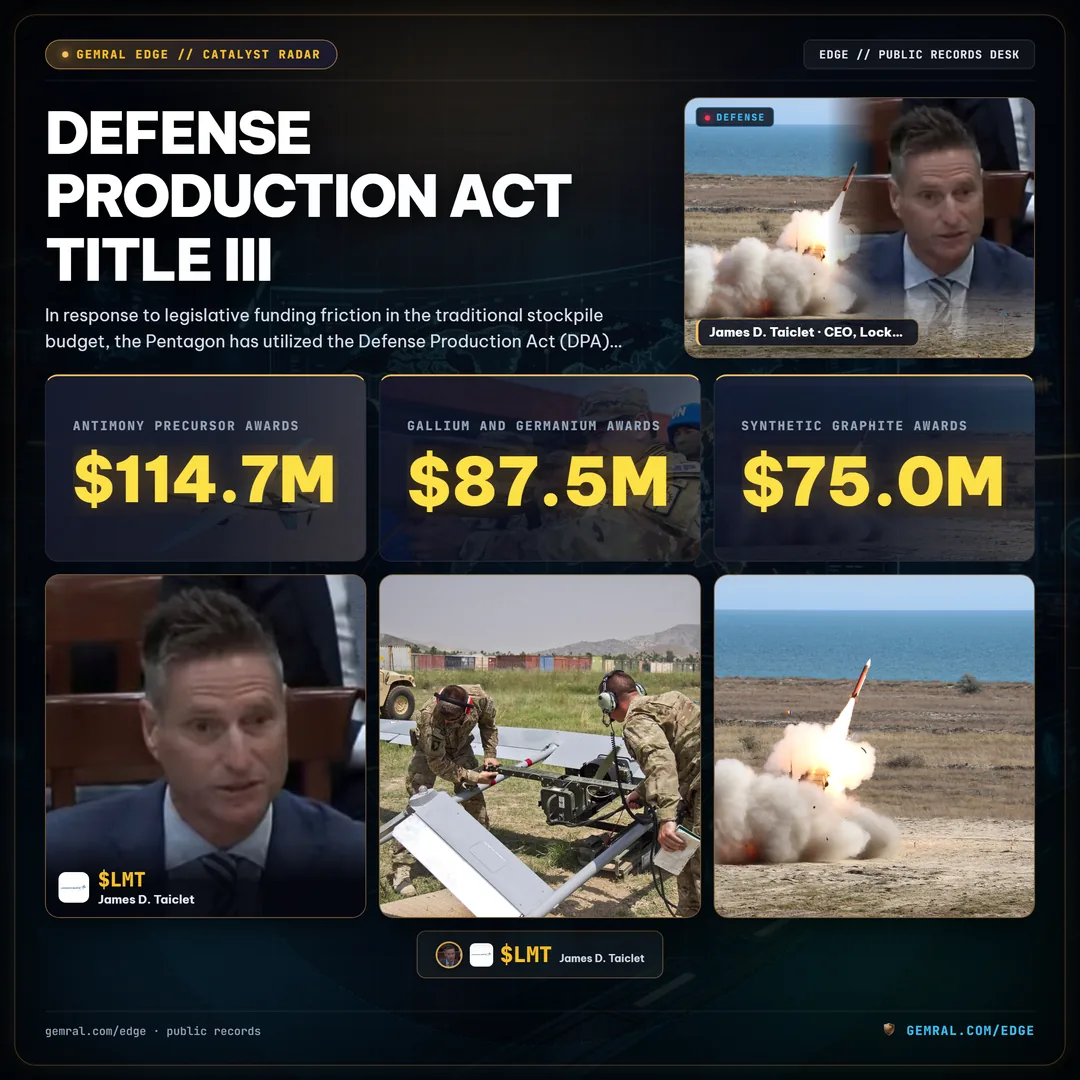
The structural allocation of these Title III funds reveals the Pentagon priority hierarchy, as broken down in Figure 3:
- Rare Earth Elements ($318.4 Million): Allocated directly to commercial operators including MP Materials in Mountain Pass, California, and Australian-headquartered Lynas Rare Earths for domestic heavy rare earth separation facilities in Seadrift, Texas. These contracts explicitly subsidize the capital cost of constructing solvent extraction circuits capable of processing light (NdPr) and heavy (DyTb) concentrates into metal-ready oxides.
- Battery-Grade Lithium & Cobalt Chemistry ($245.2 Million): Capital awards directed toward domestic cathode active material (CAM) processing and direct lithium extraction (DLE) commercial pilot plants in Nevada and Arkansas, alongside physical reserve buybacks for DoD vehicle hybridization and soldier-worn power packs.
- Titanium Sponge & High-Entropy Superalloys ($162.0 Million): Industrial grants awarded to domestic vacuum arc remelting (VAR) and electron beam cold hearth melting facilities to reconstitute domestic aerospace structural alloy supply chains following the abrupt cessation of Russian titanium sponge imports.
- Antimony Trisulfide & Energetic Precursors ($114.7 Million): Directed to Perpetua Resources and domestic downstream chemical refiners to secure domestic military-specification antimony trisulfide production for ammunition primers, ordnance delay fuses, and armor-piercing projectile cores.
- Gallium and Germanium Refining & Reclamation ($87.5 Million): Targeted grants to electronics recyclers and semiconductor foundries to extract dual-use optical and radar-grade elements from industrial tailings and manufacturing scrap.
- Synthetic Graphite Processing ($75.0 Million): Capital deployed to establish domestic high-temperature inductive graphitization furnaces capable of transforming petroleum coke into EV and defense-grade anode materials.
4. 库存消耗建模:平时消耗量对比冲突爆发消耗率
The strategic vulnerability of the existing defense supply chain is profoundly magnified when comparing peacetime operational consumption against high-intensity combat expenditure models. Peacetime procurement contracts operate on predictable, linear delivery schedules negotiated between prime defense contractors and their tier-1 through tier-4 component suppliers. In contrast, multi-theater defense simulations conducted by military planners reveal extreme material consumption acceleration rates that would overwhelm existing supply channels within weeks.
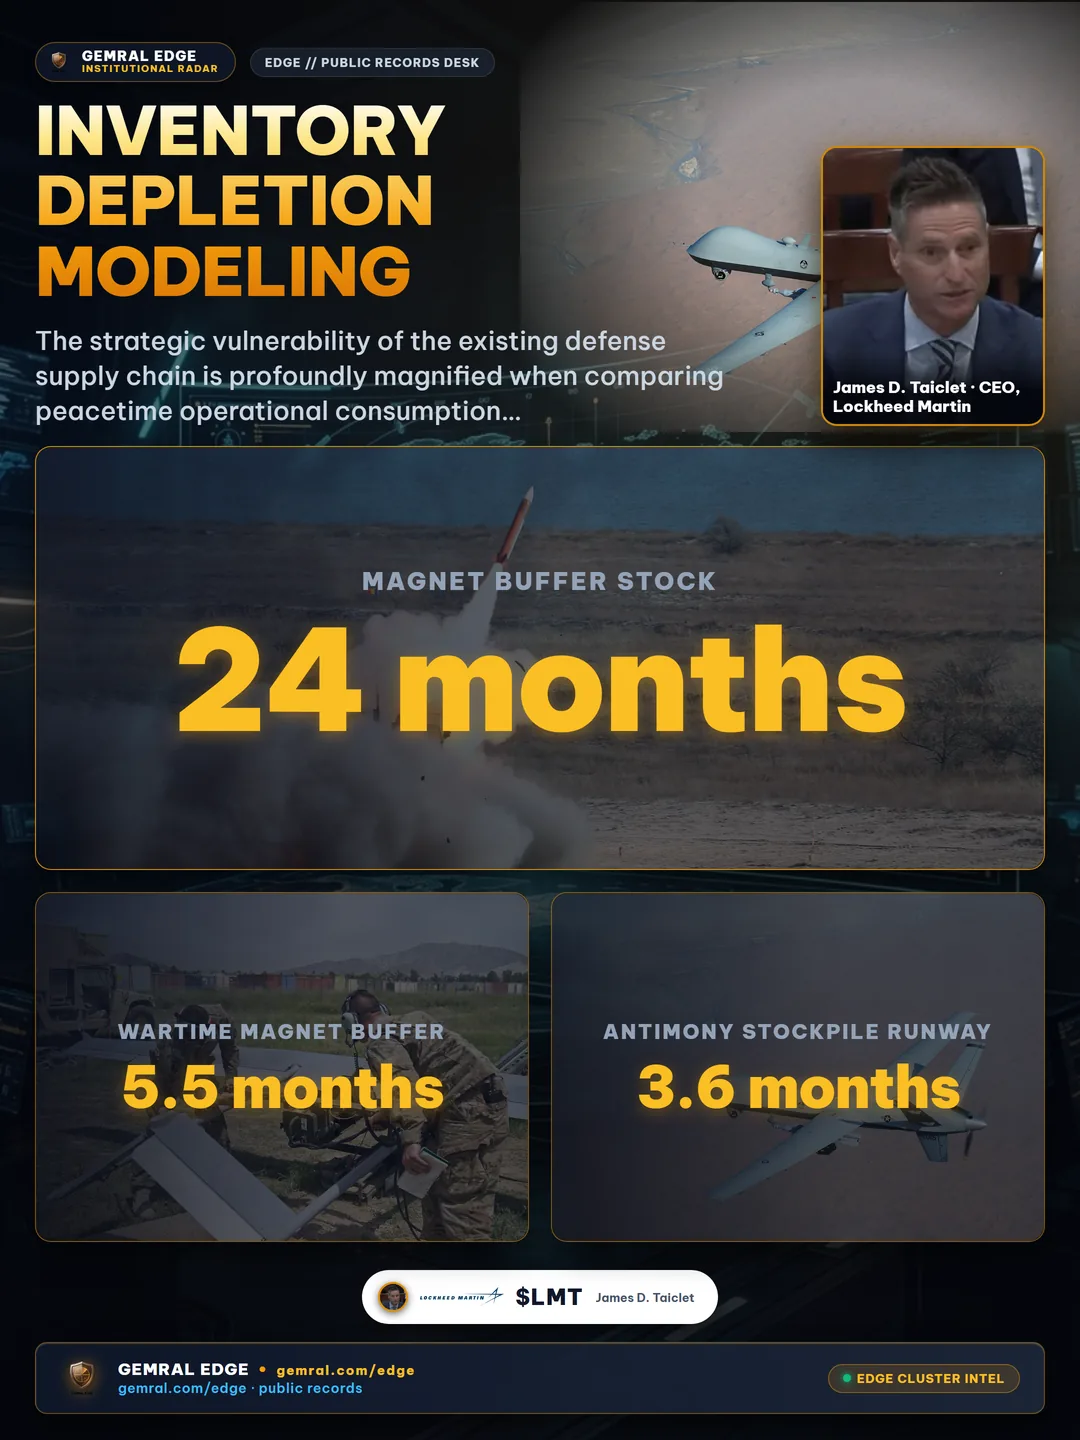
Figure 4 synthesizes Defense Logistics Agency inventory audit disclosures against simulated Indo-Pacific conflict attrition models, evaluating months of remaining supply across five critical weapon-grade material streams.
The divergence illustrated in Figure 4 is stark. In peacetime, the national inventory of Neodymium-Iron-Boron (NdFeB) permanent magnets represents approximately 24 months of buffer stock across prime contractor warehouses. Under a high-tempo conflict scenario requiring the rapid manufacturing and replenishment of expended precision-guided munitions (such as LRASM, JASSM-ER, and Tomahawk Block V missiles), that operational buffer collapses to approximately 5.5 months.
An even more acute vulnerability emerges in the antimony inventory. Antimony trisulfide serves as an indispensable primer compound in small-arms ammunition, artillery shells, and bomb fuzes. While peacetime buffer inventories reflect an 18-month baseline, wartime consumption by ammunition plants like Lake City Army Ammunition Plant would deplete strategic stockpiles in less than 3.6 months. In the absence of operating domestic refining capacity or allied airlift agreements, munition assembly lines would face immediate physical halts.
5. 武器平台投入强度:结构性依赖矩阵
To appreciate how critical mineral refining bottlenecks propagate through the broader industrial economy, one must trace material inputs down to specific primary weapon platforms. The Department of Defense modern defense catalog relies on high-performance structural, electronic, and energetic parameters that are physically unattainable with substitute baseline metals.
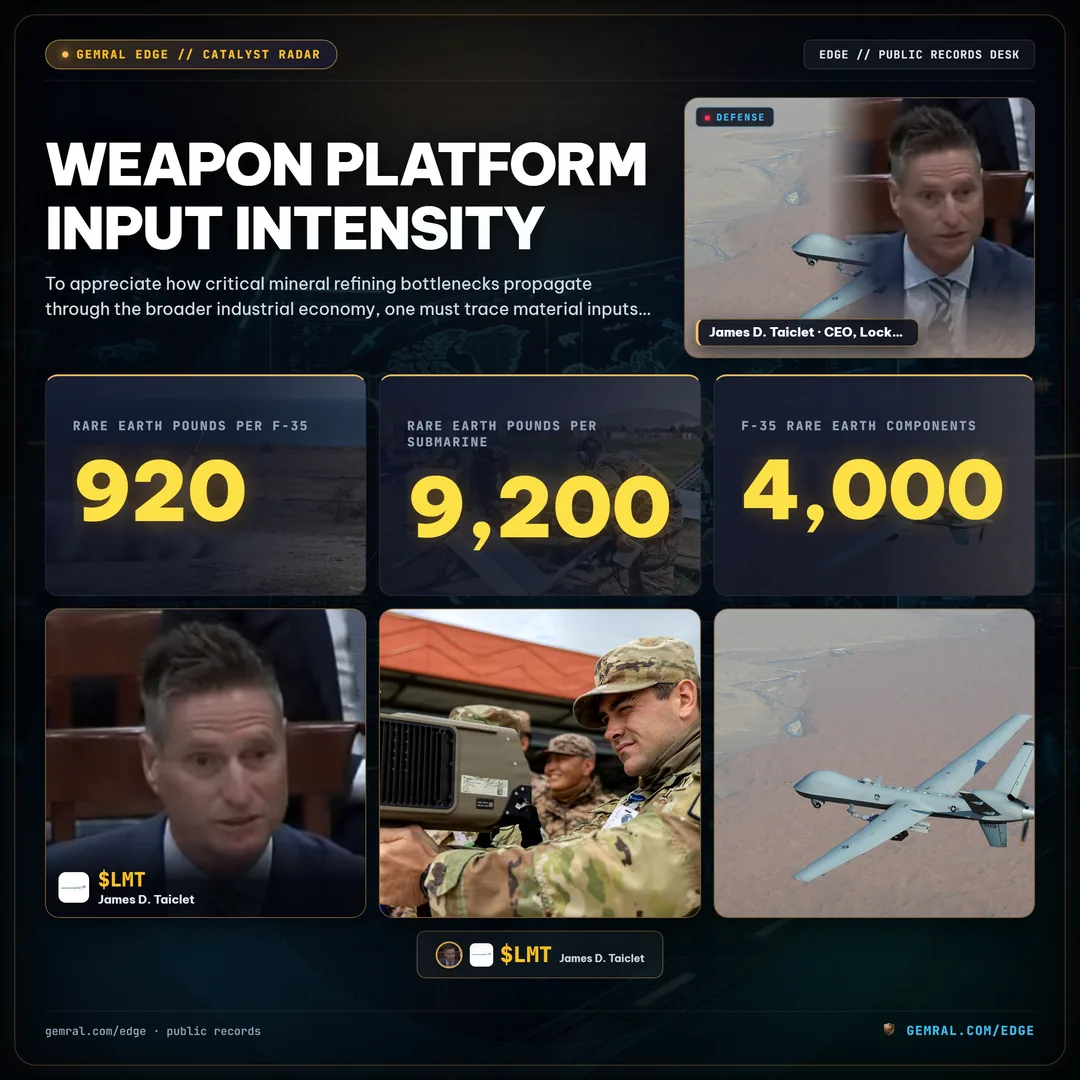
Figure 5 visualizes the reliance profile across four marquee defense production programs:
| Platform | Prime Contractor | Key Critical Inputs | Material Intensity | Supply Chain Exposure |
|---|---|---|---|---|
| F-35 Lightning II | Lockheed Martin | NdFeB Magnets, Titanium, GaN, Beryllium | 920 lbs Rare Earths per airframe | Single-point magnet alloy dependency |
| Virginia-class SSN | General Dynamics / HII | Rare Earths, Titanium, Antimony-lead seals | 9,200 lbs Rare Earths per submarine | Heavy REE sonar & actuator exposure |
| Patriot PAC-3 / LTAMDS | Raytheon Technologies | Gallium Nitride, Dysprosium, Antimony | Multi-kilogram GaN radar array wafers | High gallium precursor vulnerability |
| 155mm M795/M982 Rounds | General Dynamics OTS | Antimony Trisulfide, High-Purity Tungsten | 0.5 lbs Antimony per artillery round | Acute primer supply bottleneck |
Consider the single example of the F-35 Lightning II joint strike fighter. Each individual fifth-generation airframe requires approximately 920 pounds of refined rare earth elements integrated across more than 4,000 components. Dysprosium and Terbium are diffused into Neodymium magnets to prevent magnetic demagnetization in the severe thermal environment of the Pratt & Whitney F135 turbofan engine actuators and the electro-hydrostatic actuation systems that move flight control surfaces. Furthermore, the aircraft AN/APG-81 active electronically scanned array radar utilizes Gallium Nitride semiconductor power amplifiers that operate at vastly higher power densities and frequencies than legacy silicon, conferring detection range and electronic warfare superiority. An interruption in the flow of refined dysprosium or gallium does not merely slow aircraft assembly; it physically halts flight acceptance testing.
6. 出口管制地缘政治与两用锑的现货价格错配
The systemic risks inherent in global critical mineral refining were dramatically exposed throughout 2024 and 2025 by targeted trade restrictions on dual-use commodities. In late 2024, China Ministry of Commerce (MOFCOM) formally introduced export licensing requirements for antimony ore, metal, and downstream antimony oxide compounds, citing national security and non-proliferation objectives. Antimony is categorized as a dual-use material due to its indispensable function in flame retardants, solar glass, and ammunition priming mixtures.
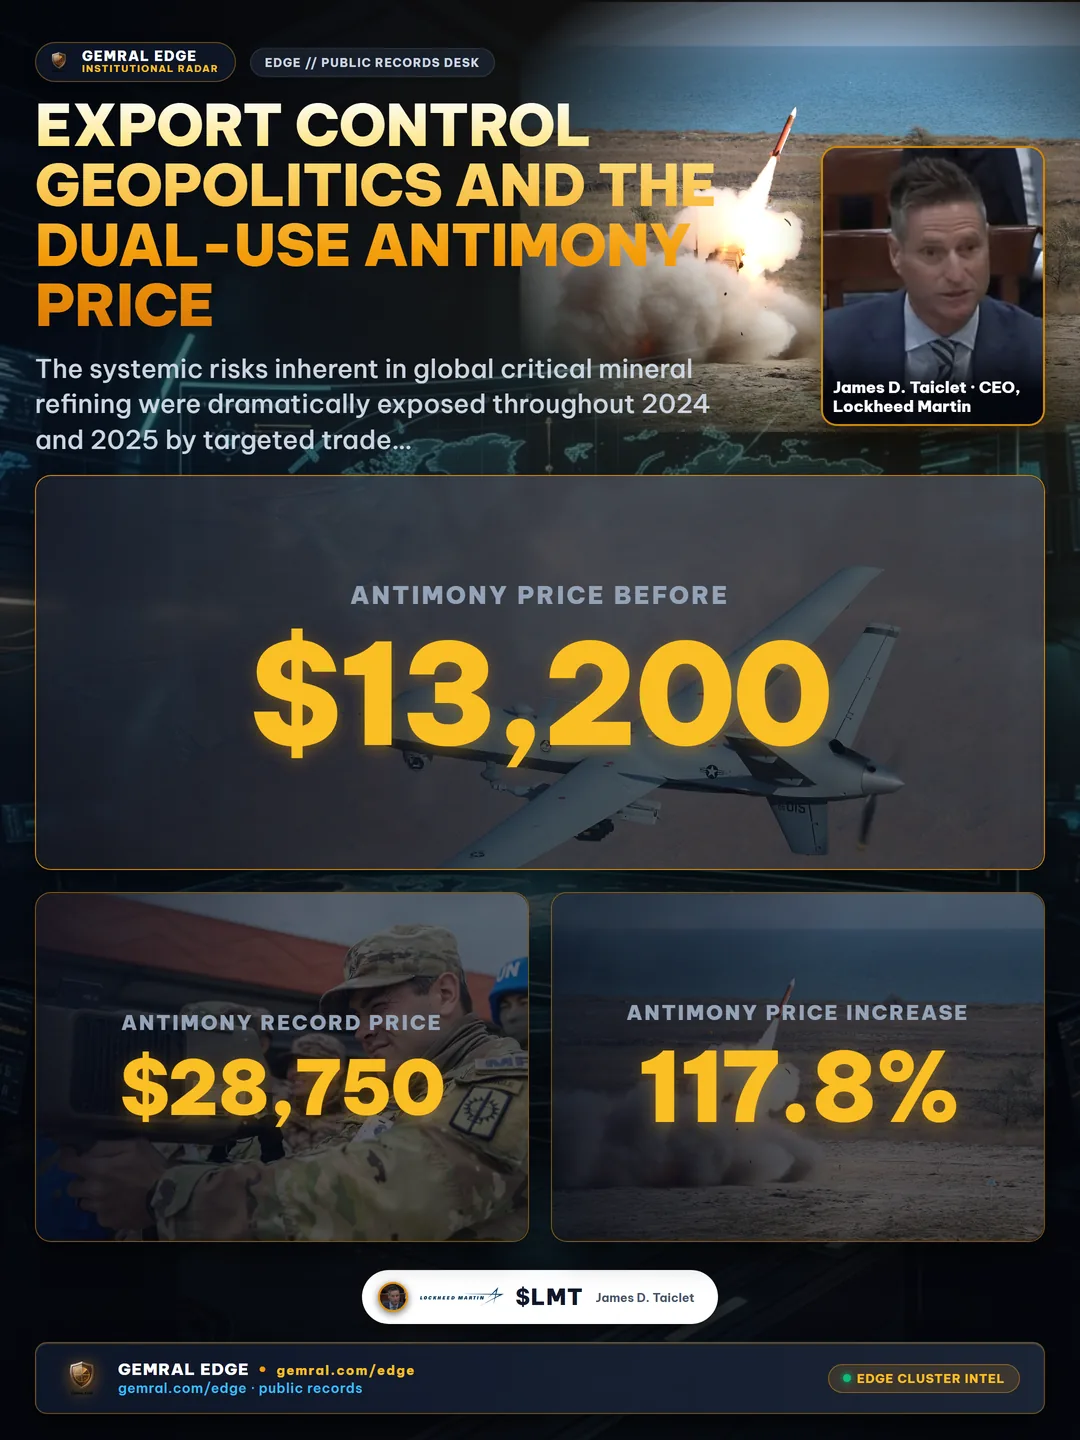
Because the Western hemisphere possessed essentially zero operating antimony smelters—with the sole historical domestic mine in Stibnite, Idaho undergoing extended permitting and development—commercial spot markets experienced immediate structural price dislocations.
As documented in Figure 6, antimony spot prices surged from approximately $13,200 per metric ton in early 2024 to an all-time record of $28,750 per metric ton by mid-2026—an increase of 117.8%. Western defense contractors attempting to procure military-grade antimony were forced into emergency open-market bidding contests against commercial battery and plastics manufacturers, triggering direct Defense Logistics Agency market intervention to secure priority deliveries under the Defense Priorities and Allocations System (DPAS).
A nearly identical dynamic unfolded in the global germanium and gallium markets following export restrictions enacted under Chinese Announcement No. 23. While Western commercial electronics companies scrambled to secure secondary scrap processing agreements in Japan and Germany, defense primes absorbed between 28% and 45% margin compression on fixed-price procurement contracts due to surging input costs for raw substrate materials. Comprehensive cross-trail verification tracks these real-time price shocks and corporate supply disclosures directly on the Gemral Edge Strategic Minerals Intelligence Terminal (gemral.com/edge/s/critical-minerals-2026).
7. 资本开支浪潮:本土精炼产能产线(2024-2028)
In response to these supply shocks, the North American industrial landscape is undergoing a capital-intensive construction boom centered on downstream mineral processing. Capital expenditure trackers across the mining and chemical engineering sectors indicate that cumulative planned investment in North American critical mineral smelting, hydrometallurgical separation, and precursor refining will expand from $2.2 billion in 2024 to an estimated $7.7 billion by 2028.
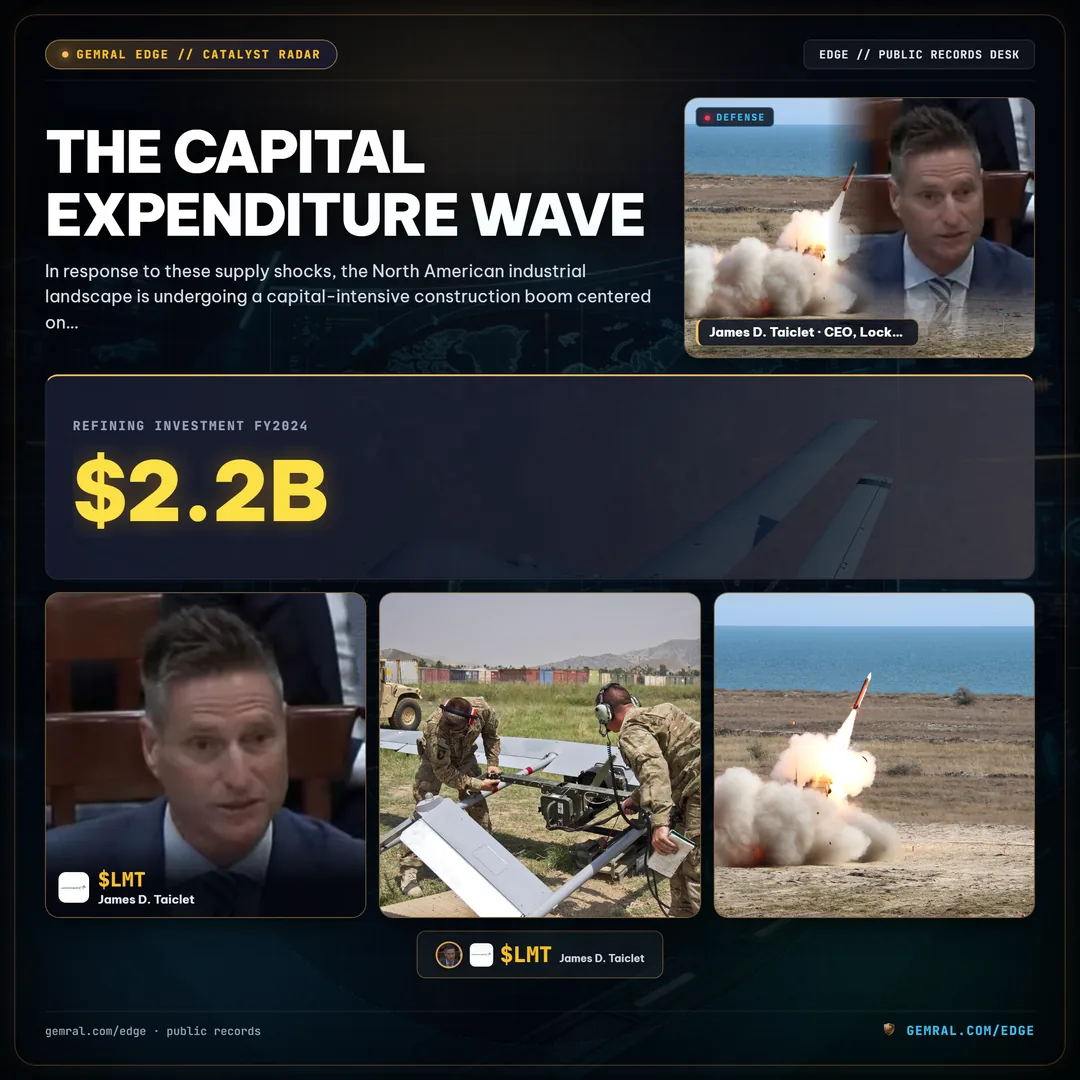
What distinguishes the current refining cycle from prior mining booms is the nature of the financing structure. As mapped in Figure 7, federal capital outlays—channeled through the DPA Title III fund, Department of Energy Title XVII clean energy loan guarantees, and Section 48C tax credits under the Inflation Reduction Act—act as de-risking equity anchors. For every dollar of direct federal grant capital committed to a commercial refining facility, private sector project finance syndicates have contributed approximately $1.75 to $2.10 in commercial debt and sponsor equity.
Key processing facilities currently under active commissioning or site preparation include:
- Lynas USA (Seadrift, Texas): A commercial hydrometallurgical separation plant designed to crack and separate heavy rare earth carbonates derived from Australian mineral sands, backed by over $250 million in Department of Defense contract commitments.
- MP Materials Stage II & III (Mountain Pass, CA & Fort Worth, TX): Developing an end-to-end magnetics supply chain that mines raw bastnäsite, refines it to 99.9% Neodymium-Praseodymium oxide on-site, and manufactures sintered NdFeB magnets at its Texas manufacturing center.
- Perpetua Resources Stibnite Project (Valley County, Idaho): Moving through final regulatory clearances with backing from an Export-Import Bank of the United States letter of interest and DPA Title III awards to establish the sole domestic source of mined and refined antimony.
- Albemarle Kings Mountain Advanced Tech Center (North Carolina): Developing novel chemical separation circuits to extract and refine battery-grade lithium hydroxide directly from spodumene pegmatites.
8. 盟国主权架构:矿产安全伙伴关系(MSP)
Despite aggressive domestic capital deployment, Department of Defense planners acknowledge that the United States cannot achieve autarky across the complete 50-mineral critical materials registry established by the U.S. Geological Survey. Environmental constraints, ore grade economics, and labor availability require an allied co-investment framework.
This operational reality led to the formalization of the Minerals Security Partnership (MSP), an international diplomatic and financial consortium comprising the United States, Australia, Canada, Japan, the United Kingdom, the European Commission, South Korea, and several partner nations. Over the past 18 months, the MSP has evolved from a diplomatic working group into an active capital deployment syndicate.
As visualized in Figure 8, the allied capital architecture functions through interlocking bilateral mechanisms:
- The US-Australia Critical Minerals Framework: Australia, possessing vast reserves of hard-rock lithium, monazite sands, and nickel, provides upstream feedstock. In return, Export Finance Australia (EFA) and the U.S. Export-Import Bank co-finance downstream refining facilities, such as Iluka Resources' Eneabba fully-integrated rare earth refinery in Western Australia ($840 million total capitalization).
- The Canada-US Defense Production Sharing Agreement (DPSA): Canadian critical mineral facilities are treated as domestic sources under Title III of the U.S. Defense Production Act, enabling direct Pentagon capital grants to Canadian graphite refiners and cobalt sulfate processors in the Becancour industrial corridor.
- Japan JOGMEC Strategic Magnet Alliances: Japan, having experienced the 2010 Senkaku Islands rare earth embargo, possesses the West most sophisticated high-efficiency permanent magnet manufacturing capabilities (Hitachi Metals/Proterial). JOGMEC co-finances processing ventures in Australia and the U.S. to ensure dual-source magnet alloy availability.
- The European Union Critical Raw Materials Act Fund: Aligning EU capital outlays ($1.15 billion allocated through 2026) with U.S. stockpile parameters to avoid predatory bidding between Western allies during supply chain crunches.
9. 市场影响与战略供应链重构
The institutional convergence of defense stockpiling mandates, export restrictions, and sovereign capital subsidies is rewriting the valuation mechanics of global mining and materials equities. For decades, institutional asset allocators valued mineral producers strictly as cyclical commodity price-takers, valuing reserves based on short-term London Metal Exchange (LME) spot pricing and discounted cash flow models heavily penalized by high capital expenditure requirements.
In the emerging geopolitical environment, a distinct bifurcation is taking place: commodity minerals vs. sovereign-aligned refined materials. Refining operators that establish verified domestic or allied custody chains, satisfy Defense Federal Acquisition Regulation Supplement (DFARS) compliance standards, and maintain physical offtake contracts with sovereign defense stockpiles are capturing structural valuation premiums.
Furthermore, sovereign capital interventions are establishing permanent price floors. Through mechanisms like the DPA Title III price stabilization guarantees and DLA long-term contracts with minimum floor clauses, the federal government is actively insulating domestic refiners from predatory price dumping. Historically, adversarial state-backed processing conglomerates utilized cyclical price suppression to bankrupt nascent Western separation plants before they reached commercial scale. Today, government-backed offtake commitments act as a structural shield, ensuring debt-service coverage for private capital partners even during severe global cyclical downturns.
10. Conclusion: Metallurgy as National Security Deterrence
The transition toward autonomous weapon platforms, hypersonic glide vehicles, directed-energy weapons, and distributed battlefield sensor meshes has irrevocably tied 21st-century military power to high-purity chemical metallurgy. Software systems can be compiled in seconds, but an industrial solvent extraction train requires three to five years of civil engineering, environmental permitting, hydrometallurgical commissioning, and process stabilization before achieving commercial purity tolerances.
The capital data from September 2026 indicates that the era of benign globalized mineral procurement has permanently closed. The United States and its allied coalition are committing billions of dollars across the National Defense Stockpile, Defense Production Act Title III programs, and the Minerals Security Partnership to reconstitute sovereign refining sovereignty. For institutional investors, defense analysts, and industrial executives, tracking this metallurgical recapitalization is no longer an exercise in commodity analysis—it is the direct observation of sovereign state power reorganizing the physical foundations of global trade.