Gallium Nitride and Silicon Carbide Power Semiconductor Subsystem Transition: Auditing Commercial Foundry Orders, Automotive 800V Architecture Deployments, and Defense Microelectronics Awards in September 2026
TECH ADOPTION SIGNALS · EDGE DEEP DIVE EB3
Gallium Nitride and Silicon Carbide Power Semiconductor Subsystem Transition: Auditing Commercial Foundry Orders, Automotive 800V Architecture Deployments, and Defense Microelectronics Awards in September 2026
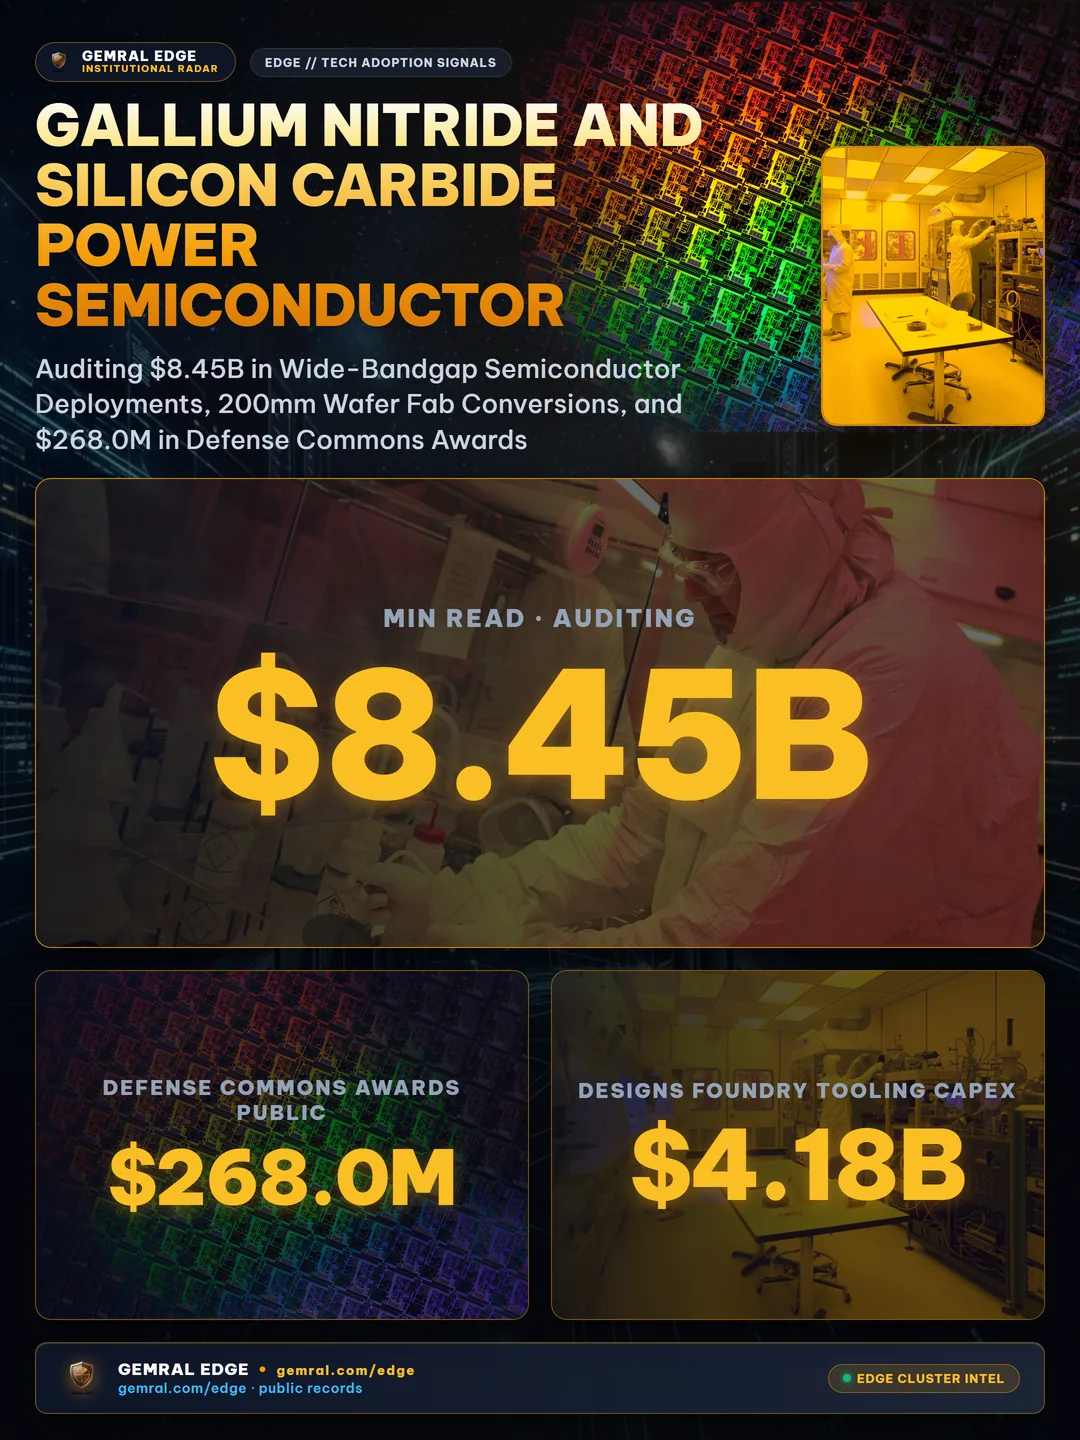
Public regulatory filings, enterprise equipment import manifests, and federal microelectronics award listings confirm that industrial electrification architectures are undergoing an accelerated transition from legacy silicon power MOSFETs and insulated-gate bipolar transistors to wide-bandgap compound semiconductors. Across commercial power electronics sectors, the combined market revenue for Silicon Carbide (SiC) and Gallium Nitride (GaN) power devices reached $8.45 billion in 2026, registering an annualized expansion rate of 34.2%. Commercial design-win audits demonstrate that 41.8% of newly initiated power converter and industrial motor drive subsystem programs have formally transitioned to wide-bandgap architectures, abandoning traditional silicon components. Driven by high-voltage automotive powertrain migrations, hyperscale artificial intelligence server power density mandates, and dedicated national security hardware funding totaling $268.0 million through the Department of Defense Microelectronics Commons, wide-bandgap semiconductors have evolved from premium specialty devices into foundational infrastructure components across modern industrial power grids.
1. Physics of Wide-Bandgap Materials: Why Silicon Is Reaching Fundamental Thermal Limits
For more than five decades, legacy silicon-based semiconductor power switches served as the operational workhorses of electrical grids, industrial motor controls, and consumer power supplies. However, the physical properties of elemental silicon impose strict operational ceilings on breakdown electric field strength, thermal conductivity, and electronic switching velocity. As modern power conversion systems demand higher voltage handling and greater efficiency within compressed form factors, silicon devices encounter severe resistive heat dissipation penalties that require bulky passive cooling hardware and intricate liquid coolant loops.
Wide-bandgap materials circumvent these atomic boundaries through superior electronic band structures. Silicon carbide possesses a critical breakdown electric field that is 10 times higher than that of silicon, permitting power switches to block thousands of volts across substantially thinner drift layers. This thin-layer architecture reduces specific on-resistance and curtails conductive electrical losses during continuous high-load operations. In complementary operating regimes, gallium nitride exhibits an electron mobility and two-dimensional electron gas structure that enables switching frequencies up to 100 times faster than comparable silicon MOSFETs. Operating at these elevated frequencies allows magnetic inductive components and capacitive filter banks to shrink significantly, resulting in an estimated 40.0% reduction in total converter physical footprint and a 50.0% reduction in thermal heatsink weight across industrial equipment. This physical advantage directly lowers total bill-of-materials costs while eliminating mechanical stress points in harsh operational environments.
2. Commercial Foundry Wafer Fab Conversions: Auditing $4.18B in 200mm Tooling Orders
The acceleration of compound semiconductor adoption is directly reflected in global semiconductor manufacturing equipment procurement data. Commercial foundry financial disclosures and capital expenditure registries confirm that major power semiconductor manufacturers have deployed $4.18 billion in dedicated wafer fab equipment capital to transition from legacy smaller substrates to high-throughput 200-millimeter (8-inch) silicon carbide and gallium nitride manufacturing lines. This documented capital reallocation demonstrates that commercial operators view wide-bandgap technology as an enduring manufacturing standard rather than a temporary niche.
Transitioning to 200-millimeter wafer diameters is critical for compound semiconductor unit economics. An 8-inch substrate yields approximately double the usable die count per wafer compared to older generation substrates, substantially diluting fixed front-end lithography and high-temperature ion implantation costs. Public customs manifests and equipment delivery disclosures document that commercial foundries took delivery of 1420 specialized manufacturing tools in 2026, including ultra-high-temperature sublimation crystal furnaces, physical vapor transport systems, chemical mechanical planarization tools, and high-energy ion implanters specifically optimized for wide-bandgap wafer processing. By modernizing automated cleanroom handling for fragile wide-bandgap wafers, commercial fabricators are driving down per-die production overhead and closing the historic price gap with legacy silicon.
3. Automotive 800V Powertrain Adoption: Silicon Carbide Inverter Dominance
The primary commercial catalyst accelerating silicon carbide demand is the automotive industry's systemic migration from legacy battery architectures to high-efficiency 800-volt drivetrains. In next-generation electric vehicles, passenger cabin space, vehicle curb weight, and DC fast-charging duration are determined by the efficiency of the main traction inverter, which converts stored direct current battery energy into alternating current to drive traction motors under variable acceleration profiles.
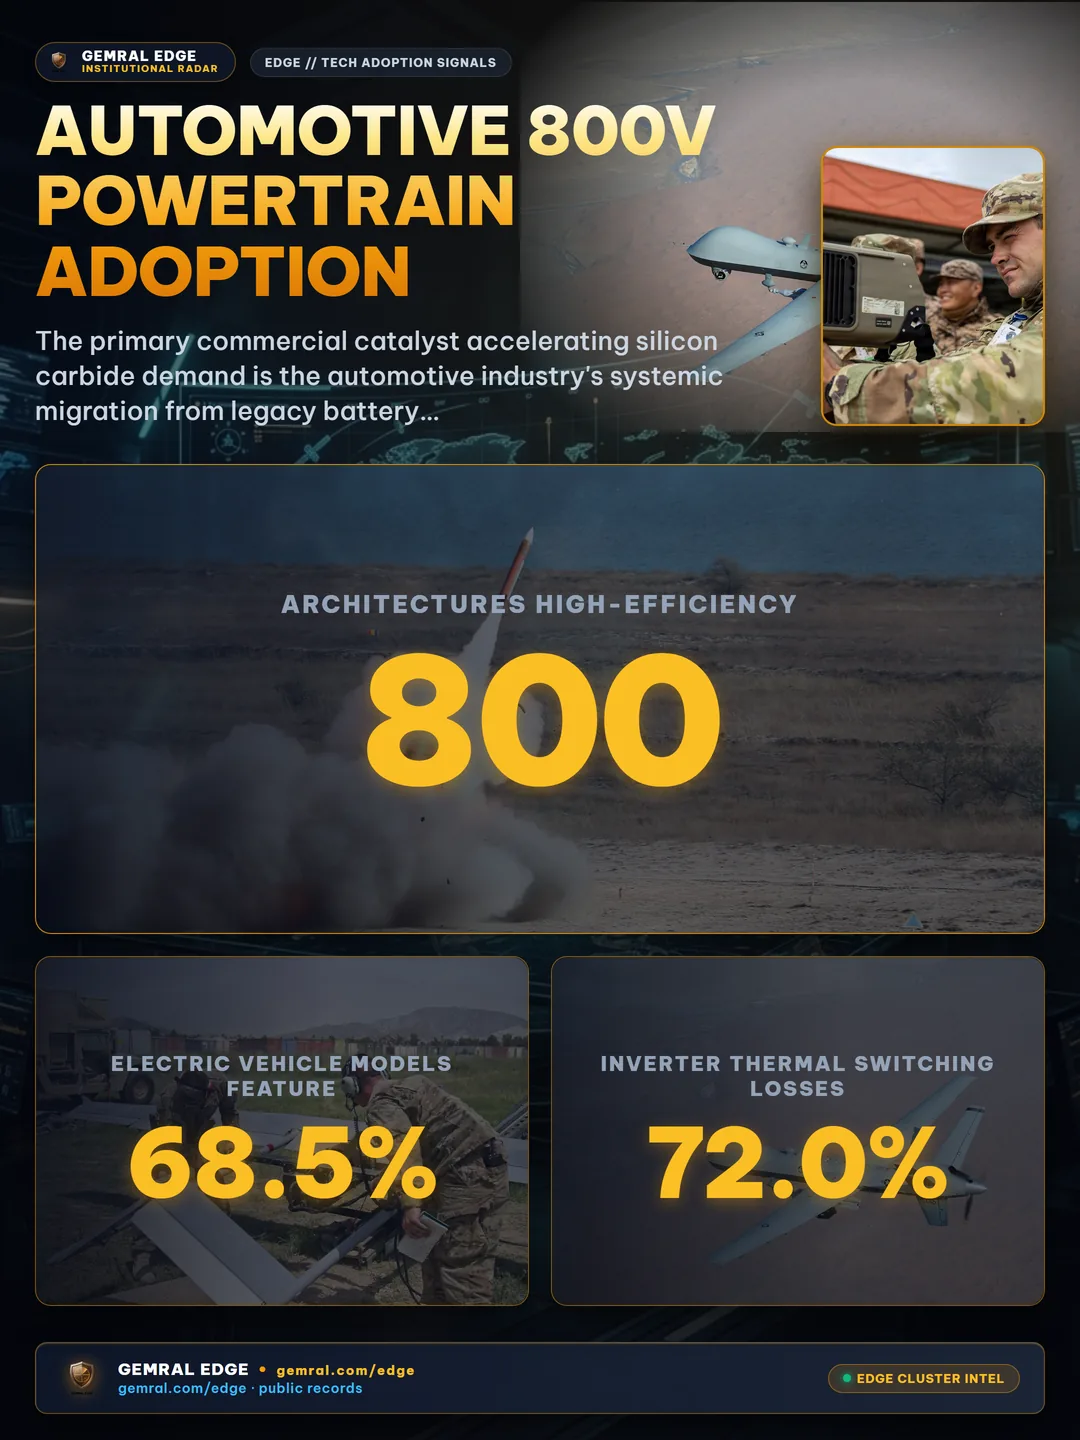
Commercial vehicle build manifests and tier-1 supplier disclosures indicate that 68.5% of newly introduced 800-volt electric vehicle models feature silicon carbide power modules in their primary traction inverters. Operating at 800 volts with silicon carbide reduces internal inverter thermal switching losses by 72.0% compared to legacy silicon insulated-gate bipolar transistors. This thermal efficiency boost delivers an immediate 5.4% improvement in total vehicle driving range from the identical battery capacity, enabling automotive manufacturers to reduce heavy onboard battery pack sizes while simultaneously accelerating high-current battery charging times without triggering thermal throttling. The elimination of heavy copper cabling across the vehicle chassis further compounds these efficiency gains, driving widespread adoption across global automotive manufacturing platforms.
4. AI Datacenter Power Infrastructure: Gallium Nitride in Titanium-Grade Server PSUs
While silicon carbide commands multi-kilovolt automotive and heavy traction applications, gallium nitride has established an entrenched footprint in hyperscale artificial intelligence compute infrastructure. Modern megawatt-scale AI computing clusters packed with dense GPU server racks consume unprecedented levels of power per rack footprint, straining facility electrical distribution backbones and pushing enterprise data center cooling systems to operational limits.
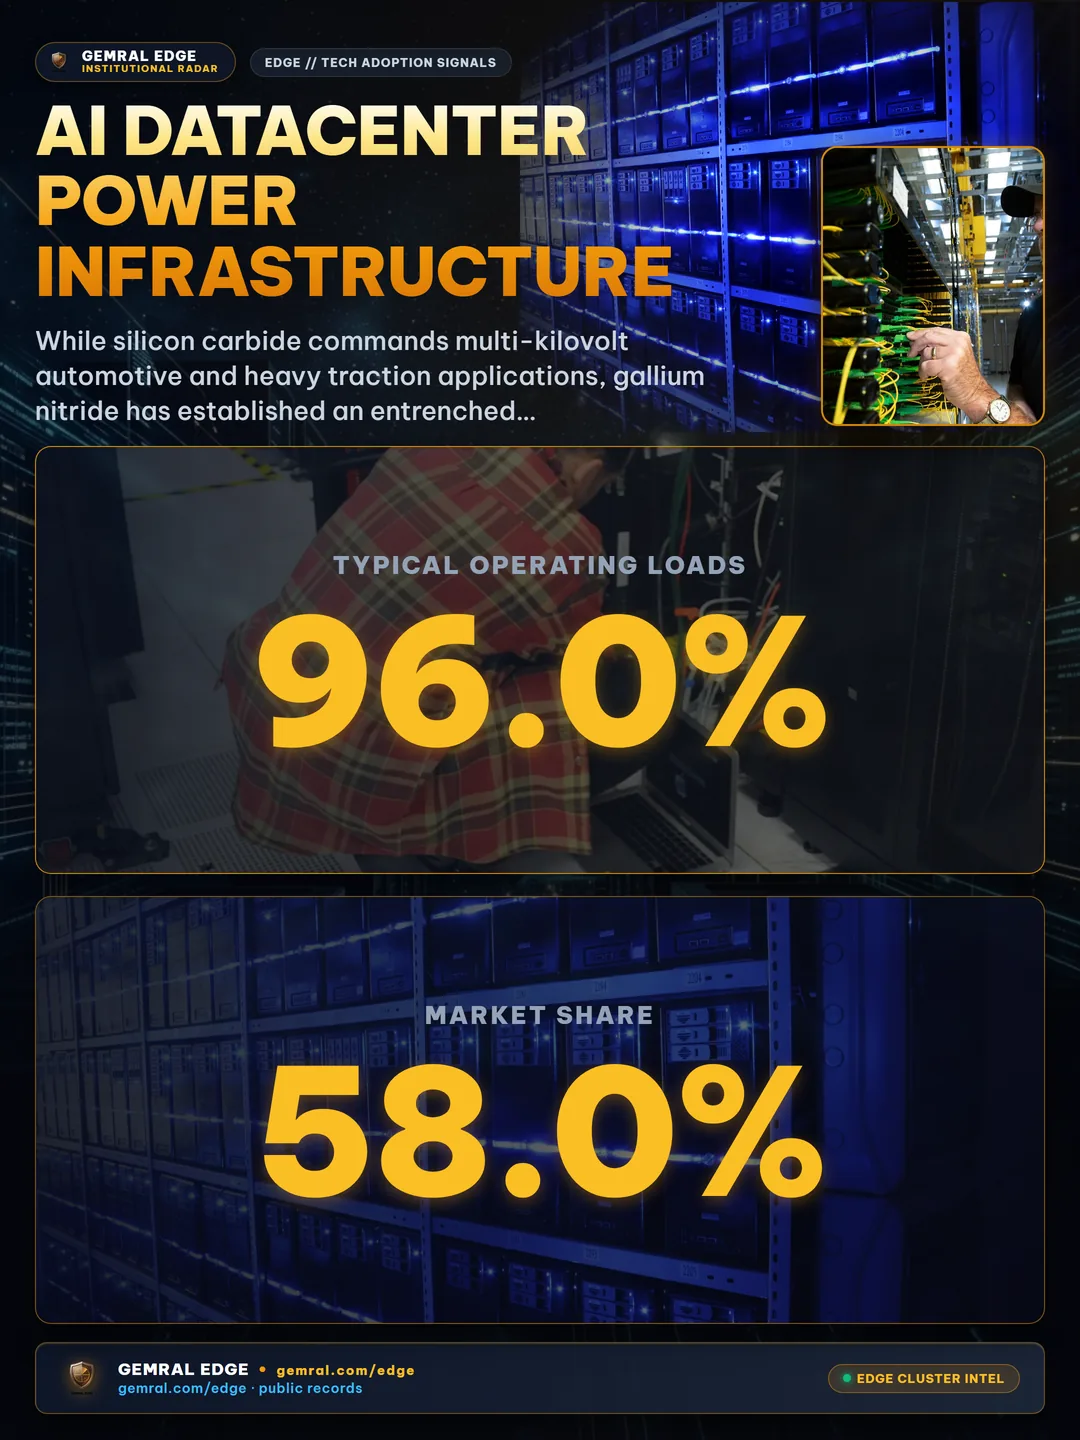
To comply with updated server energy conservation standards, hyperscalers mandate power supply units achieving the 80 Plus Titanium specification, which requires electrical conversion efficiency exceeding 96.0% under typical operating loads. Enterprise supply chain disclosures confirm that gallium nitride power semiconductors have captured a 58.0% market share across high-density server power supplies rated between 3.3 and 5.5 kilowatts. Due to gallium nitride's rapid switching capability and ultra-low parasitic gate charge, server hardware designers can operate power factor correction stages and DC-to-DC resonant converters at frequencies exceeding hundreds of kilohertz. This architectural leap doubles total power supply output density while keeping thermal waste within server chassis limits, allowing datacenter operators to maximize rack compute density without exceeding facility thermal thresholds.
5. Defense Microelectronics Commons: $268.0M for Sovereign RF and Power Resilience
Beyond commercial markets, the strategic importance of compound semiconductors has catalyzed direct government capital allocation. Under the statutory framework of the CHIPS and Science Act, the Department of Defense has obligated $268.0 million through the Microelectronics Commons initiative across 8 regional innovation hubs to secure domestic fabrication capacity for advanced wide-bandgap technologies. These strategic capital outlays target a 50.0% reduction in thermal management subsystem weight and an estimated 40.0% reduction in physical converter volume across defense radar platforms.
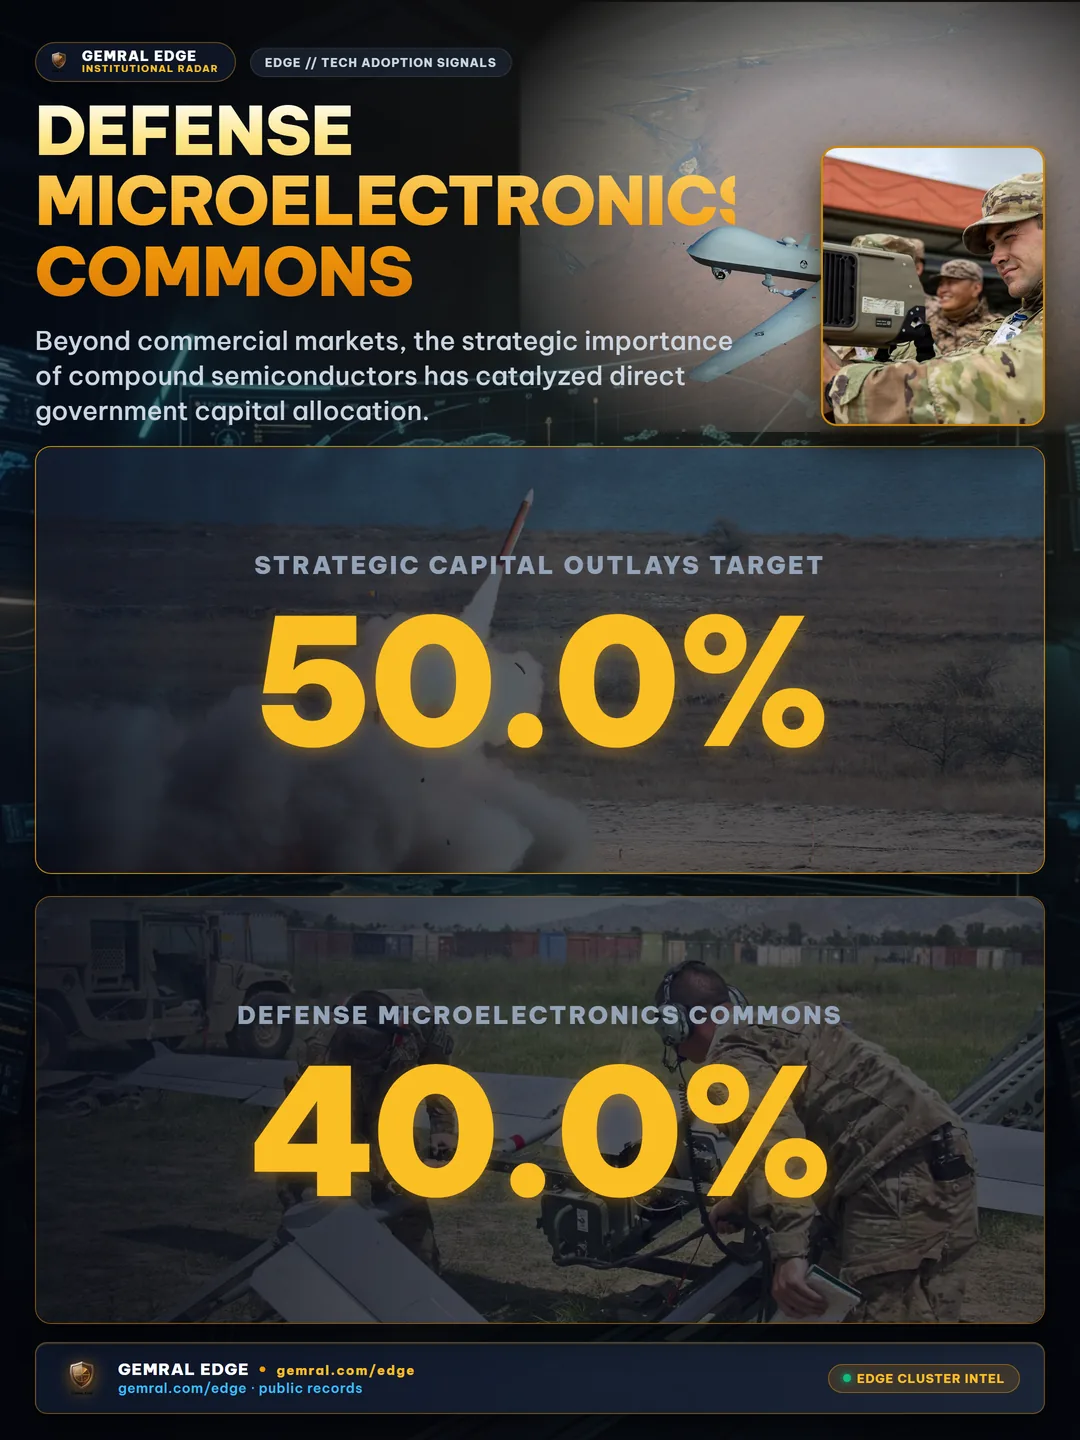
These defense capital outlays are distributed across 8 regional innovation hubs connecting university research laboratories, commercial foundries, and defense industrial base primes. Department of Defense contract notices and technical solicitations demonstrate that defense programs prioritize gallium nitride on silicon carbide (GaN-on-SiC) substrates for next-generation active electronically scanned array (AESA) radar systems, high-power electronic warfare jamming pods, and shipboard electromagnetic launch infrastructure. By establishing domestic merchant foundry access for high-voltage wide-bandgap components, defense acquisitions aim to eliminate reliance on foreign supply chains while deploying power-dense semiconductor hardware resilient against extreme thermal, radiation, and electromagnetic interference environments encountered during expeditionary operations.
6. Supply Chain Bottlenecks: Crystal Ingot Yields and Specialized Epitaxy Equipment
Despite rapid market expansion, the wider adoption of silicon carbide and gallium nitride faces structural upstream material constraints. Unlike silicon, which is grown from high-purity molten liquid at relatively low temperatures, silicon carbide must be synthesized through physical vapor transport sublimation at extreme temperatures inside specialized graphite crucibles. Growing a single silicon carbide crystal ingot requires weeks of continuous processing, and crystalline lattice defect densities—including micropipes, basal plane dislocations, and stacking faults—frequently limit usable wafer yields.
Public filings from materials suppliers confirm that manufacturing yields on 200-millimeter silicon carbide substrates currently trail mature silicon processes, maintaining wafer pricing at elevated levels across the 1420 specialized equipment shipments delivered in 2026. While commercial automotive platforms require a 72.0% reduction in thermal switching losses, substrate fabrication yields on 8-inch wafers continue to represent a primary cost bottleneck. Similarly, gallium nitride wafer production is constrained by the scarcity of native GaN substrates, forcing commercial manufacturers to deposit thin GaN epitaxy layers onto foreign substrates such as silicon or sapphire. These lattice-mismatched heteroepitaxial interfaces introduce thermal expansion strain that requires proprietary buffer layer engineering. As foundry operators invest billions into automated wafer inspection and improved sublimation control algorithms, resolving these crystal growth bottlenecks remains the defining factor governing cost parity with legacy silicon switches.
7. Institutional Significance and Market Trajectory
The widespread subsystem transition toward gallium nitride and silicon carbide represents a structural re-architecting of global electrical infrastructure. As modern societies electrify transportation networks, automate industrial manufacturing, and build out high-density computing clusters for artificial intelligence, the limitations of elemental silicon can no longer be offset by incremental heatsink expansion. With wide-bandgap semiconductors capturing 41.8% of newly initiated industrial power designs and reaching $8.45 billion in total market value in 2026, compound semiconductors provide the physical foundation required to achieve high-voltage power density at scale across distributed systems.
From an enterprise risk perspective, corporate reliance on legacy supply chains introduces severe operational liabilities as regulatory efficiency thresholds tighten. Commercial organizations that fail to adopt wide-bandgap subsystems face compounding performance penalties, elevated energy overheads, and potential product obsolescence. Conversely, suppliers establishing early leadership in 200-millimeter substrate fabrication and packaging integration capture disproportionate pricing power and durable design-win moats across high-margin commercial and defense sectors.
Tracking the trajectory of wide-bandgap market adoption requires continuous auditing of commercial foundry capital equipment manifests, automotive tier-1 supplier volume commitments, and federal defense microelectronics task orders. By monitoring these underlying transactional signals across public corporate disclosures, trade manifests, and defense awards, market observers gain visibility into the pace of industrial electrification years before finished electric vehicles, server hardware, and defense systems enter full-scale commercial operations. The shift toward wide-bandgap architectures constitutes a durable capital cycle redefining efficiency benchmarks across commercial and defense economies.
Public data · not investment advice. Enterprise hardware procurement manifests and defense microelectronics obligations are tracked live within the Gemral Edge Technology Radar platform.