In modern global financial architecture, the single largest sovereign checking account resides not in a commercial bank, but on the balance sheet of the Federal Reserve Bank of New York. The Treasury General Account (TGA) serves as the primary operating deposit account of the United States federal government. Through this single account, the Department of the Treasury collects hundreds of billions in federal income and corporate taxes, receives proceeds from sovereign debt auctions, and disburses trillions in statutory outlays ranging from social security obligations to defense procurement.
Yet, beneath its routine operational purpose, the Treasury General Account acts as a sovereign liquidity sponge. Because the TGA is a liability on the Federal Reserve balance sheet rather than a deposit in the commercial banking sector, every single dollar transferred into the TGA is instantaneously removed from the commercial banking system. For hedge funds, quantitative macro desks, and institutional asset allocators, tracking daily fluctuations in the TGA balance has emerged as an indispensable barometer of system liquidity, corporate credit spreads, and equity market valuation multiples.
How the Treasury General Account Anchors Federal Operating Cash Balances
Established under the statutory authority of the Federal Reserve Act of 1913, the Treasury General Account is the federal government's master checking account. Administered directly by the Federal Reserve Bank of New York as the fiscal agent of the United States, the TGA centralized sovereign cash management following historical periods where public funds were dispersed across private commercial depositories under the historic Treasury Tax and Loan (TT&L) program.
Under modern fiscal governance, the Treasury maintains a calibrated operating cash target, typically structured around a prudential buffer of $750B. This operating cushion is engineered to provide the Treasury with sufficient liquidity to cover approximately five to seven business days of net federal outlays without having to execute emergency debt auctions during systemic market disruptions. In extreme liquidity crunches or unexpected revenue shortages, the Treasury operates under a minimum statutory buffer floor of $100B, ensuring the sovereign can meet non-discretionary payments.
The daily mechanics of the TGA are cataloged in the Daily Treasury Statement (DTS), published every federal business day at 16:00 Eastern Time. The DTS details opening cash balances, raw tax receipts categorized by individual and corporate withholding, customs duties, public debt market issuance across Treasury bills, notes, and bonds, and aggregate federal withdrawals. By monitoring these disbursements through institutional macro liquidity tracking, macro desks quantify how federal fiscal spending circulates into high-powered reserves, contrasting sharply with periods where aggressive auction schedules absorb private capital.
Understanding the scale of the TGA requires recognizing its sheer magnitude relative to commercial balance sheets. Unlike private enterprise treasuries that manage working capital across distributed private money centers, the sovereign cash pool fluctuates by tens of billions of dollars within single trading sessions. When quarterly corporate tax deadlines arrive in mid-April, June, September, and December, sovereign cash inflows surge by over $100B in a span of 48 hours, orchestrating an immediate mechanical contraction in commercial banking reserves.
Mechanics of TGA Balances: How Treasury Tax Inflows Drain Commercial Bank Reserves
To grasp why fluctuations in the Treasury General Account dictate systemic financial conditions, one must examine the double-entry bookkeeping of the Federal Reserve balance sheet. The Federal Reserve's liabilities consist primarily of three dominant components: Currency in Circulation, Commercial Bank Settlement Balances (reserves held by depository institutions), and Sovereign Operating Deposits (predominantly the TGA and foreign official repo facilities).
Because the asset side of the Federal Reserve balance sheet—dominated by holdings of U.S. Treasury securities and agency mortgage-backed securities totaling approximately $7.1T—changes slowly under programmatic Quantitative Tightening (QT) or Quantitative Easing (QE), any expansion in one liability category must be mathematically offset by an equivalent contraction in another.
When an enterprise or retail taxpayer submits an income tax payment to the Internal Revenue Service, funds do not simply shift between corporate accounts. The taxpayer's commercial bank must settle the transaction with the Federal Reserve. The central bank debits the commercial bank's reserve account and simultaneously credits the Treasury General Account. The resulting transformation is immediate and mechanical: high-powered reserves in the private banking system decrease by the exact dollar value of the tax payment, while sovereign government cash increases.
This reserve drain reduces the total volume of cash available in the fed funds market, repo lending desks, and commercial short-term credit facilities. When aggregate reserves are drawn down by $300B to $500B during major fiscal tax settlement dates, commercial banks face higher marginal costs for balance sheet expansion. Secondary lending capacity contracts, primary dealers widen bid-ask spreads on sovereign securities, and leveraged market participants face elevated funding benchmarks in overnight collateralized lending facilities.
Conversely, when the federal government disburses capital—such as paying defense contractors, disbursing Medicare settlements, or servicing national debt coupon payments—the reverse plumbing takes place. The Federal Reserve debits the TGA liability and credits the commercial bank accounts of prime contractors and citizens. Commercial bank reserves expand dollar-for-dollar. This sovereign cash injection floods interbank funding markets with surplus settlement balances, suppressing overnight financing rates and providing liquidity that asset managers deploy across global risk assets, reinforcing empirical findings noted in our analysis of global M2 money supply and central bank liquidity.
Historical TGA Drawdowns and Refill Cycles: Tracking Debt Ceiling Resolutions
The most pronounced sovereign liquidity cycles in modern financial history have stemmed from legislative standstills surrounding the statutory U.S. debt ceiling. When the federal debt reaches its Congressionally mandated borrowing limit, the Treasury is legally prohibited from executing net new debt issuance. To fulfill statutory government obligations without defaulting, the Treasury must deploy statutory accounting measures and systematically run down the cash balance of the Treasury General Account.
During historical debt ceiling standstills across 2024 and 2025 fiscal horizons, the TGA balance experienced historic drawdowns, collapsing from normalized operating buffers above $750B down to a precarious trough of just $45B. During this cash depletion phase, the federal government spent hundreds of billions of dollars directly into the private financial system without issuing corresponding debt to absorb capital. This dynamic acted as an unintended fiscal quantitative easing program, pumping hundreds of billions of high-powered reserves into commercial banks and driving an aggressive rally in high-beta equity multiples.
However, the resolution of a debt ceiling standoff triggers an aggressive, mirrored counter-reaction: the TGA refill cycle. Once Congress suspends or raises the debt statutory ceiling, the Department of the Treasury must rapidly replenish its depleted operating cash reserves back toward its prudential $750B target or seasonal peak refill targets of $850B.
To achieve this rapid reconstitution within a compressed 60 to 90 days window, the Treasury unleashes a wave of short-term Treasury bill (T-bill) issuance, frequently exceeding $300B to $500B in net sovereign paper over single calendar quarters. The systemic question confronting quantitative desks during refill cycles is: who buys the bills?
If money market funds (MMFs) absorb the new Treasury bill supply by reallocating capital away from the Federal Reserve's Overnight Reverse Repurchase Agreement (ON RRP) facility, system liquidity remains relatively insulated. In that scenario, cash moves from the ON RRP facility directly into the TGA, swapping one non-bank Federal Reserve liability for another while leaving commercial bank reserves completely untouched.
However, once the ON RRP facility is largely depleted—falling from historical peaks above $2.5T toward lower operating bands of $250B—new Treasury bill issuance must be funded directly by private commercial deposits and institutional bank balance sheets. When bank reserves fund the refill, the liquidity vacuum is intense. Quantitative macro models track the speed and duration of TGA rebuilding cycles because rapid sovereign cash accumulation historically coincides with spikes in market volatility, tightening financial conditions, and downward multiple compression across extended equity valuations.
Deconstructing Federal Reserve Net Liquidity: Total Assets Minus TGA and Reverse Repo
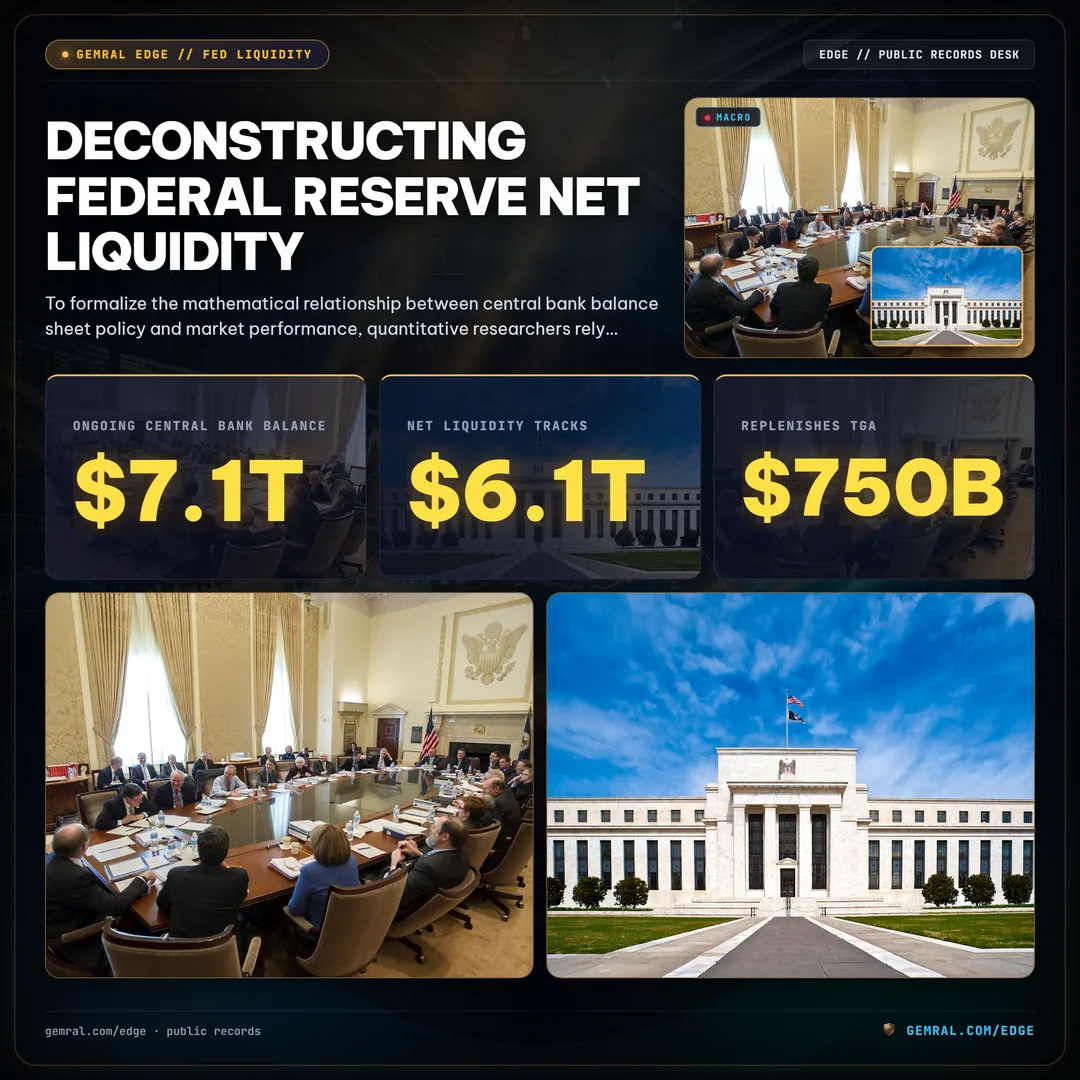
To formalize the mathematical relationship between central bank balance sheet policy and market performance, quantitative researchers rely on the Federal Reserve Net Liquidity model. While headline financial media routinely monitors the nominal size of the Fed's total balance sheet, sophisticated asset managers recognize that total assets alone offer an incomplete picture of high-powered capital circulating through capital markets.
The core Federal Reserve Net Liquidity formula is expressed through the following balance sheet identity:
Federal Reserve Net Liquidity = Total Central Bank Assets - Treasury General Account Balance - Overnight Reverse Repo Facility (ON RRP)
In this formulation, Total Assets represent the aggregate size of the Federal Reserve portfolio, currently hovering near $7.1T under the ongoing central bank balance sheet runoff program. Both the TGA and the ON RRP facility represent sterile pools of capital locked inside the central bank. Money parked in the TGA cannot be lent, hypothecated, or deployed into private risk assets by commercial banks. Similarly, cash committed by institutional money market funds to the ON RRP facility remains quarantined overnight at the central bank.
Therefore, subtracting both the TGA and ON RRP from Total Assets isolates the true quantity of high-powered bank reserves actively underpinning commercial credit extension, broker-dealer repo intermediation, and speculative market risk-taking. Under current structural benchmarks, Net Liquidity tracks closely around $6.1T.
Historical regression analysis demonstrates a strong statistical correlation between 30-day changes in Federal Reserve Net Liquidity and subsequent performance across major market benchmarks, including the S&P 500, the Nasdaq 100, and corporate high-yield credit spreads. When Net Liquidity expands—either due to Federal Reserve asset purchases, an aggressive TGA cash drawdown, or money market fund outflows from ON RRP—equity valuation multiples expand. Conversely, when the Treasury simultaneously replenishes the TGA to $750B while the central bank maintains balance sheet runoff, Net Liquidity contracts sharply, precipitating market consolidation or heightened downside volatility.
Measuring the Transmission Mechanism to Equity Volatility and Risk Asset Multiples
How does a fluctuation in a central bank deposit account transmit into the pricing of public technology equities, industrial conglomerates, or sovereign debt yields? The transmission mechanism operates across three primary financial plumbing channels: Primary Dealer balance sheet capacity, repo market spread compression, and institutional equity risk premia.
First, consider the role of Primary Dealers—the elite cohort of global financial institutions authorized to participate directly in Treasury auctions. When the Treasury floods the market with debt auctions to refill the TGA, Primary Dealers are legally obligated to absorb any unmet auction allocations. If foreign central banks or domestic private asset managers fail to bid aggressively, Primary Dealers must warehouse hundreds of billions in newly issued sovereign paper directly on their trading balance sheets.
Saddled with large inventories of sovereign debt, dealers reach internal risk limits under regulatory capital constraints, including the Supplementary Leverage Ratio (SLR). To preserve balance sheet room, dealers curtail margin financing extended to hedge funds, widen pricing across equity derivatives, and pull back liquidity provision in index futures. The result is a sharp reduction in market-making depth, leaving equities vulnerable to magnified intraday selloffs upon negative macro headlines.
Second, the TGA cash drain alters short-term money market spreads. When cash reserves are siphoned into sovereign coffers, the Secured Overnight Financing Rate (SOFR) frequently drifts upward relative to the Fed's Interest on Reserve Balances (IORB) rate. When overnight repo borrowing rates print above IORB, it signals systemic friction in cash distribution. Hedge funds executing basis trades, long-short equity arbitrage, and risk-parity strategies face increased financing costs, compelling systematic deleveraging across diversified portfolios.
Third, equity valuation multiples—especially for long-duration growth assets whose valuations depend heavily on discounted terminal cash flows—display acute sensitivity to net liquidity shifts. When sovereign cash accumulation contracts banking reserves, market participants demand higher equity risk premia to compensate for tighter financial plumbing. Empirical tracking across 12 months cycles reveals that rapid TGA expansions of $250B or greater within 30 days historically correspond with measured surges in the Cboe Volatility Index (VIX) and cyclical pullbacks in cyclical stock sectors, matching patterns documented in our investigation of defense contractor stock obligations and broader federal expenditure pipelines.
Quarterly Refunding Announcements and Strategic Projections for Sovereign Cash Targets
Because shifts in sovereign cash management carry profound macro implications, institutional investors scrutinize the Treasury's forward guidance with the same intensity reserved for Federal Open Market Committee (FOMC) interest rate decisions. The premier venue for this forward guidance is the Quarterly Refunding Announcement (QRA), released by the Department of the Treasury during the first week of February, May, August, and November.
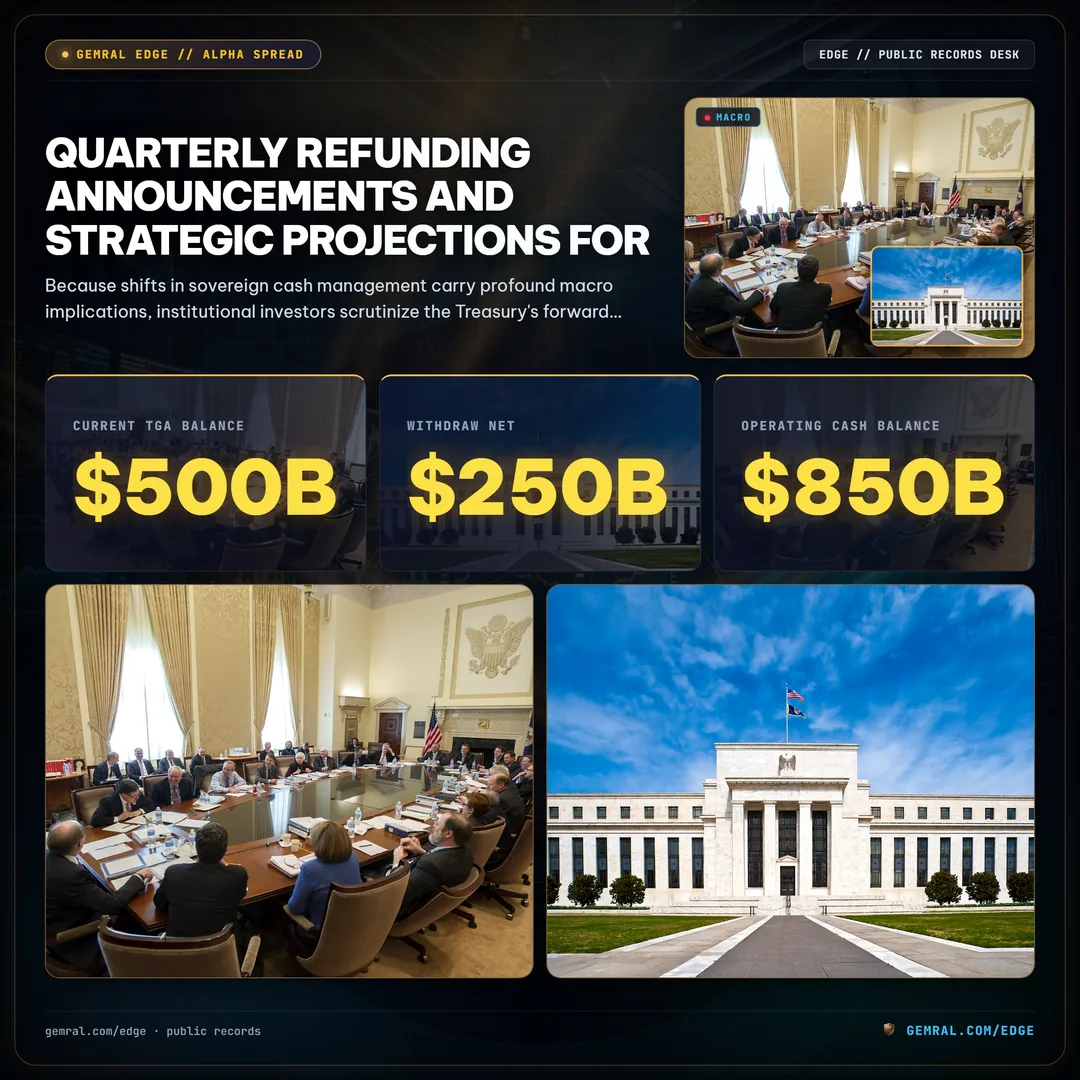
In each QRA release, the Treasury Office of Debt Management collaborates with the Treasury Borrowing Advisory Committee (TBAC)—an advisory group comprised of senior executives from global investment banks and hedge funds—to release explicit borrowing estimates and end-of-quarter TGA cash balance projections spanning upcoming quarters.
For example, when the Treasury announces a projected end-of-quarter TGA target of $750B for the subsequent quarter, quantitative macro desks immediately construct debt-issuance models. If the current TGA balance stands at $500B, the market understands that the Treasury must withdraw a net $250B in cash from financial markets over the next 90 days, on top of financing the ongoing federal budget deficit.
Conversely, if the Treasury signals that its operating cash balance has accumulated to $850B and projects a target reduction toward $700B, the announcement provides an advance green light for market liquidity. A projected cash drawdown of $150B represents an impending net liquidity injection into the commercial banking system, offering an empirical tailwind for credit spreads and equity market breadth.
Furthermore, the QRA outlines the precise auction mix between short-dated Treasury bills (maturities under one year) and intermediate-to-long-dated coupon notes (2-year to 30-year maturities). When the Treasury skews issuance heavily toward short-term bills, it minimizes term premium pressure on 10-year and 30-year benchmark yields, allowing money market liquidity to absorb sovereign paper with minimal disruption to corporate borrowing benchmarks.
Navigating these macro liquidity cycles requires granular, point-in-time data intelligence. The Gemral Edge platform monitors real-time Daily Treasury Statements, Federal Reserve balance sheet line items, and sovereign debt auction allocations to equip institutional investors with predictive macro analytics. Market participants can access these quantitative intelligence feeds through Gemral Edge subscription tiers, including the Pro tier at $39 per month (or $390 billed annually), the B2B team tier at $299 per month, or the institutional API integration tier at $2000 per month for algorithmic trading desks and proprietary factor modeling systems.
By continuously tracking sovereign cash targets, Federal Reserve net liquidity equations, and commercial reserve drains, asset allocators move beyond lagging headline narratives, positioning capital ahead of the structural liquidity tides that truly dictate equity market trends.
Public data · not investment advice. All liquidity data, Treasury cash balances, and Federal Reserve balance sheet metrics cited are sourced from public regulatory disclosures and official government publications.
Frequently asked questions
What is the Treasury General Account (TGA)?
The Treasury General Account is the federal government's primary operating checking account held at the Federal Reserve Bank of New York, used to manage daily tax collections, public debt proceeds, and federal expenditures.
How does the TGA balance affect stock market liquidity?
A rising TGA balance drains cash reserves from commercial banks into the Federal Reserve, decreasing net financial liquidity and tightening equity market conditions. Conversely, a declining TGA balance injects cash back into commercial bank reserves, boosting systemic liquidity and risk asset valuations.
What is the formula for Federal Reserve Net Liquidity?
Federal Reserve Net Liquidity is calculated as Total Federal Reserve Assets minus the Treasury General Account balance minus the Overnight Reverse Repurchase Agreement (ON RRP) facility balance: Net Liquidity = Fed Assets - TGA - ON RRP.
What happens to the TGA during a debt ceiling crisis?
During debt ceiling constraints, the Treasury is barred from issuing new debt and must exhaust its cash balance down to statutory operating troughs, artificially injecting hundreds of billions into banking reserves until Congress passes a debt limit suspension.