When corporate executives deploy their personal liquid capital into their own equities, they leave an indelible footprint on public regulatory ledgers. Across 35,195 verified filings systematically ingested by the corporate insider trading tracker, open-market purchases offer market participants an unfiltered window into corporate executive sentiment before major operational developments materialize in quarterly earnings calls.
Yet, the raw stream of regulatory filings is notoriously noisy. For every meaningful discretionary market order placed by an informed chief executive, hundreds of routine equity compensation grants, scheduled tax-withholding sales, and pre-programmed automated dispositions flood public regulatory archives. Understanding how an insider trading tracker extracts genuine conviction from regulatory noise requires dissecting transaction mechanics, statutory reporting windows, and the quantitative power of point-in-time entity resolution.
How an Insider Trading Tracker Decodes Section 16 Disclosures in Real Time
An insider trading tracker is an automated financial surveillance engine designed to monitor, ingest, normalize, and interpret public filings submitted under Section 16(a) of the Securities Exchange Act of 1934. Under federal securities regulations, corporate insiders—defined specifically as corporate officers, members of the board of directors, and any beneficial owners holding more than a 10% equity stake—must report changes in their holdings within a strict statutory deadline of 2 business days.
These disclosures are codified primarily through Section 16 regulatory filings, a structured regulatory document detailing transaction execution dates, standardized transaction codes, share volumes, and execution prices across 35,195 filings. A modern quantitative surveillance tracker ingests these XML-formatted public records within milliseconds of submission, transforming unstructured regulatory dumps into structured data streams.
The core analytical utility of an automated tracker lies in its ability to immediately filter out administrative noise. Out of millions of shares reported annually, the tracker isolates transactions executed with cash on the open market, matching ticker symbols to historical entities and calculating transaction scale relative to historical filing velocity. For investors examining executive behavior, referencing historical insider selling vs buying transaction signals reveals why open-market buying carries exponentially higher statistical signal than routine insider dispositions.
Discretionary Open-Market Buys vs Routine Rule 10b5-1 Automated Plans
The single most critical classification performed by an institutional-grade insider trading tracker is the mathematical separation between discretionary open-market purchases and pre-scheduled automated transactions. On corporate insider filings, transactions are categorized by standardized transaction codes. Transaction Code P designates an open-market or private purchase of non-derivative securities, representing a conscious, voluntary decision by an individual insider to deploy cash into company stock at prevailing market prices.
Conversely, Transaction Code S denotes an open-market sale, while Code M designates the exercise or conversion of derivative securities (such as stock option grants), and Code G reflects a bona fide gift of securities. However, examining transaction codes alone is insufficient. Following regulatory reforms, corporate insiders frequently adopt Rule 10b5-1 trading plans—pre-arranged written agreements that require a mandatory cooling-off period of 90 days for directors and officers before the first trade can execute, or a 120 days waiting period depending on filer classification.
Rule 10b5-1 plans provide corporate executives with an affirmative defense against insider trading allegations by establishing that transactions were planned well in advance of material non-public developments. While essential for executive liquidity and personal wealth planning, automated dispositions under pre-arranged schedules carry minimal informational value. In contrast, unscheduled Code P purchases executed outside of 10b5-1 plans represent spontaneous capital commitments. A thorough examination of Rule 10b5-1 trading plans and mandatory cooling off periods illustrates why institutional surveillance engines prioritize spontaneous Code P filings where the affirmative defense checkbox is left unchecked.
Detecting C-Suite Cluster Buys: The High-Conviction Insider Multiplier
While an isolated open-market purchase by an individual corporate director can occasionally stem from contractual board ownership requirements or idiosyncratic personal tax planning, an insider cluster buy represents one of the strongest empirical anomalies available in public market data. A cluster buy is quantitatively defined as a concentrated event wherein 3 or more independent corporate insiders execute open-market purchases within a rolling window of 30 calendar days, or within a compressed 14 days timeframe.
The statistical significance of an insider cluster buy increases exponentially with the breadth of leadership participating. When an operational Chief Executive Officer and an independent audit committee chair simultaneously deploy hundreds of thousands of dollars into open-market shares, it indicates an alignment of internal sentiment across distinct functional responsibilities. Independent board members possess fiduciary oversight without day-to-day operational incentives, whereas operational executives understand supply chain bottlenecks, pipeline conversion velocity, and forward margins.
Algorithmic surveillance models calculate a cluster conviction multiplier by weighting the aggregate dollar value committed, the percentage increase in each insider's total equity holdings, and the historical track record of each filer. Historically, companies demonstrating high-density executive cluster purchases following cyclical drawdowns show measurable divergence over subsequent 12 months reporting horizons compared to benchmark indices.
Point-in-Time Entity Resolution: Eliminating Survivorship and M and A Look-Ahead Bias
For quantitative hedge funds, systematic factor researchers, and fundamental analysis desks, the greatest technical barrier to utilizing historical insider trading data is entity resolution across corporate lifecycle events. Raw government and regulatory disclosure databases are notoriously susceptible to survivorship bias, ticker reassignments, corporate reorganizations, and look-ahead bias spanning 5 years to 10 years of market history.
When an equity undergoes a statutory spin-off, reverse merger, bankruptcy reorganization, or strategic acquisition, naive data systems frequently overwrite historical corporate identifiers with the acquiring parent company's current ticker. For example, if a historic defense contractor or enterprise technology vendor was acquired 3 years ago, backtesting models that join old ownership transactions against the modern parent's balance sheet introduce catastrophic look-ahead bias—simulating trades on entities that did not exist in their current corporate form on the publication date.
To deliver institutional rigor, an enterprise-grade surveillance architecture enforces point-in-time entity resolution with a verified 95% accuracy gate benchmark. Each individual ownership disclosure is permanently linked to the precise corporate parent entity, Central Index Key (CIK), and exchange-traded ticker that were legally valid on the exact calendar date the filing became public. Delisted, restructured, and acquired corporate entities remain preserved within historical records under their original historical tickers. Analyzing how parallel disclosure systems operate in our study on congressional stock trackers vs corporate insider filings confirms why point-in-time data normalization remains the gold standard of financial engineering.
Analyzing Real-World Insider Accumulation: Multi-Million Dollar Filings in Practice
Empirical market surveillance demonstrates how real-time insider tracking surfaces large-scale capital deployments across diverse market capitalization tiers. Recent filings captured across our institutional database highlight substantial discretionary capital allocations executed across the corporate landscape:
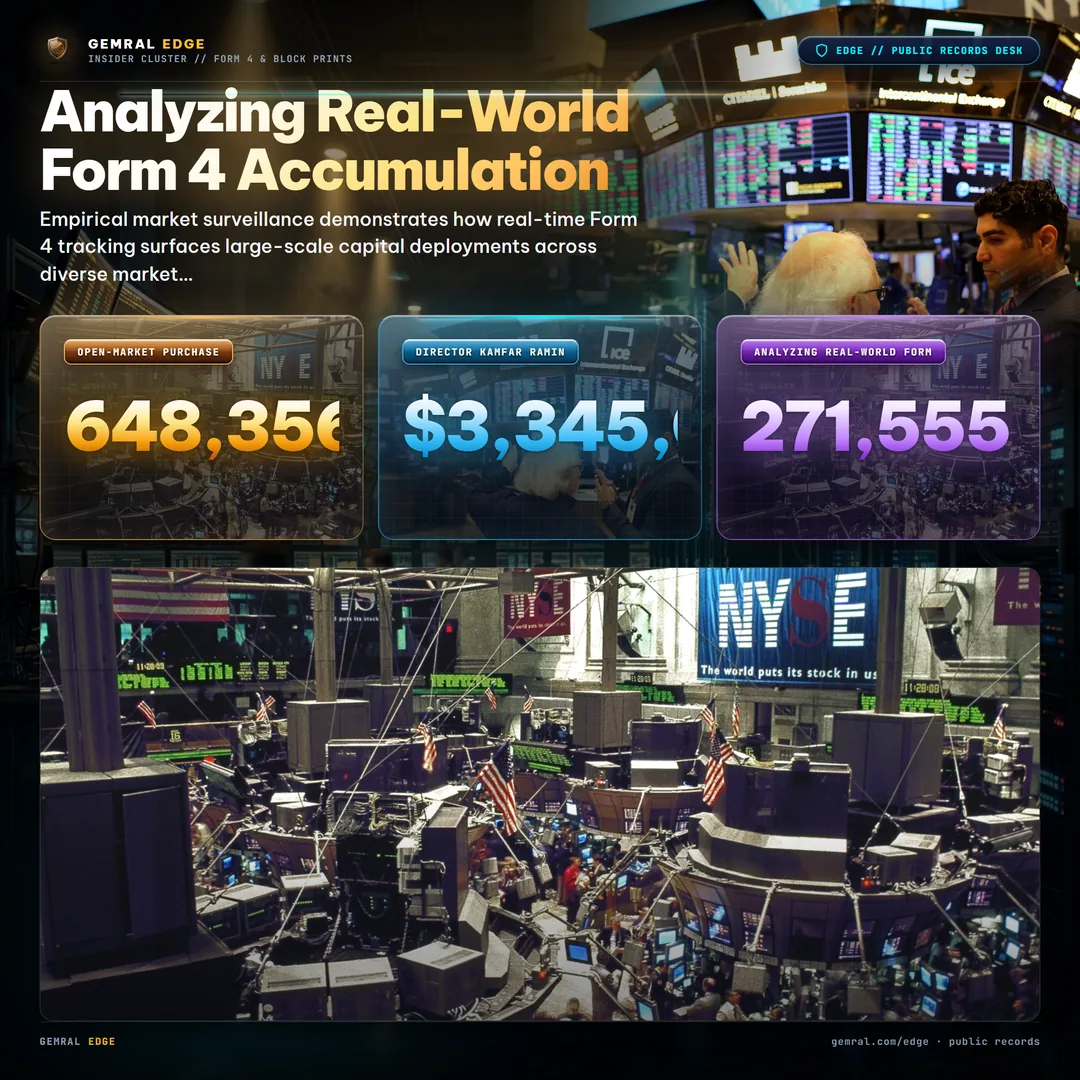
- Dole plc (DOLE): On October 22, 2026, institutional insider Pale Fire Capital SE executed an open-market purchase of 648,356 shares of DOLE. Filed publicly on October 23, 2026, the aggregate transaction value reached $8,554,410. Executed under Transaction Code P without an underlying 10b5-1 pre-scheduled plan, the purchase represented a concentrated discretionary accumulation of direct equity.
- BPRE: Demonstrating board-level conviction, Director Kamfar Ramin committed $3,345,006 on October 21, 2026, acquiring 271,555 shares via open-market execution. Disclosed under regulatory ownership filings on October 22, 2026, the transaction reflected substantial personal liquidity deployment in an opportunistic market action.
- FB Financial Corporation (FBK): Long-tenured Director Ingram Orrin H II executed an open-market purchase of 29,081 shares on October 20, 2026, at an aggregate transaction value of $1,537,787. Disclosed on October 22, 2026, the non-10b5-1 purchase substantially expanded the director's beneficial ownership stake.
- Agora, Inc. (API): Providing an operational C-suite signal, Chief Executive Officer Zhao Bin executed an open-market purchase of 38,267 shares on October 22, 2026, totaling $168,304. Submitted publicly on October 23, 2026, the transaction underscored operational leadership deploying discretionary capital into company equity.
In each instance, the transactions were characterized by three vital quantitative traits: they utilized direct open-market execution (Code P), bypassed pre-scheduled 10b5-1 automatic disposition contracts, and occurred directly on public regulatory registries within statutory disclosure windows.
Structural Blind Spots and Public Disclosure Lags in Corporate Insider Filings
While insider trading disclosures provide rigorous fundamental intelligence, sophisticated market participants must account for several structural limitations and statutory reporting delays inherent to regulatory filings:
First, the primary structural friction in insider disclosure data is the statutory reporting window. Under Section 16(a) of the Securities Exchange Act, corporate insiders have up to 2 business days—equivalent to roughly 48 hours following execution—to submit their filings to regulatory authorities. During volatile trading sessions or post-earnings market corrections, an executive purchase executed on a Monday morning may not be publicly visible until Wednesday evening after market close. Consequently, short-term price action may absorb part of the move before disclosures are broadcast.
Second, administrative equity grants and estate planning maneuvers frequently cloud aggregate volume metrics. Executives frequently transfer shares between direct holdings, family limited partnerships, and revocable trusts, or surrender shares to satisfy corporate tax withholding obligations upon option vesting. Quantitative systems must rigorously cleanse these transfers from net accumulation tallies to prevent phantom liquidity distortion across reporting quarters.
Third, beneficial ownership rules impose different disclosure requirements on major shareholders holding above a 10% threshold compared to operating officers. Large investment funds holding over a 10% equity stake are classified as statutory insiders, yet their purchasing decisions may reflect broader index reconstitution, debt-to-equity restructuring, or fund mandate rebalancings rather than intimate operational foresight into corporate product pipelines.
How Quantitative Desks Monitor Corporate Insider Conviction at Scale
To harness the predictive properties of corporate insider accumulation without falling victim to structural data traps, modern institutional trading desks integrate programmatic data pipelines that monitor public filings alongside broader capital market signals.
By linking real-time insider filings with historical Point-in-Time entity databases spanning 365 days of active disclosures, factor models construct multi-layered conviction scores. These algorithms weigh the transaction's dollar magnitude against the executive's annual cash compensation, evaluate historical filing predictive reliability across market cycles, and cross-reference insider buying with external regulatory catalysts across 12 months observation windows.
When combined with systematic factor discipline, an institutional insider trading tracker transforms raw regulatory compliance documents into an indispensable radar for corporate health, governance alignment, and executive sentiment.
Public data · not investment advice. All transaction data and regulatory disclosures cited are sourced from public regulatory filings and point-in-time financial records.
Frequently asked questions
What is an insider trading tracker?
An insider trading tracker is a data analytics system that ingests public regulatory ownership filings to detect when corporate officers, board directors, and beneficial owners purchase or sell shares of their own companies in the open market.
What is the difference between open-market purchases and routine 10b5-1 plans?
Open-market purchases (Transaction Code P) represent discretionary capital commitments where executives use personal liquidity to buy shares, signaling direct conviction. In contrast, Rule 10b5-1 plans are pre-scheduled selling or buying programs adopted months in advance, carrying significantly less predictive sentiment.
What constitutes an insider cluster buy?
An insider cluster buy occurs when three or more distinct corporate insiders (such as the CEO, CFO, and independent board members) execute open-market purchases of their company's stock within a concentrated window, typically 14 to 30 days.
How quickly must corporate insiders file disclosures after a transaction?
Under Section 16(a) of the Securities Exchange Act of 1934, corporate insiders must file regulatory disclosures within two business days following the execution date of the transaction.