Delta Footprint Heatmap Estimator | WebMCP Tool
Order Flow Delta Footprint Heatmap Estimator
Interactive WebMCP tool to model order flow delta footprint heatmaps, tick volume aggregation, passive bid-ask absorption, and exhaustion reversal probabilities.
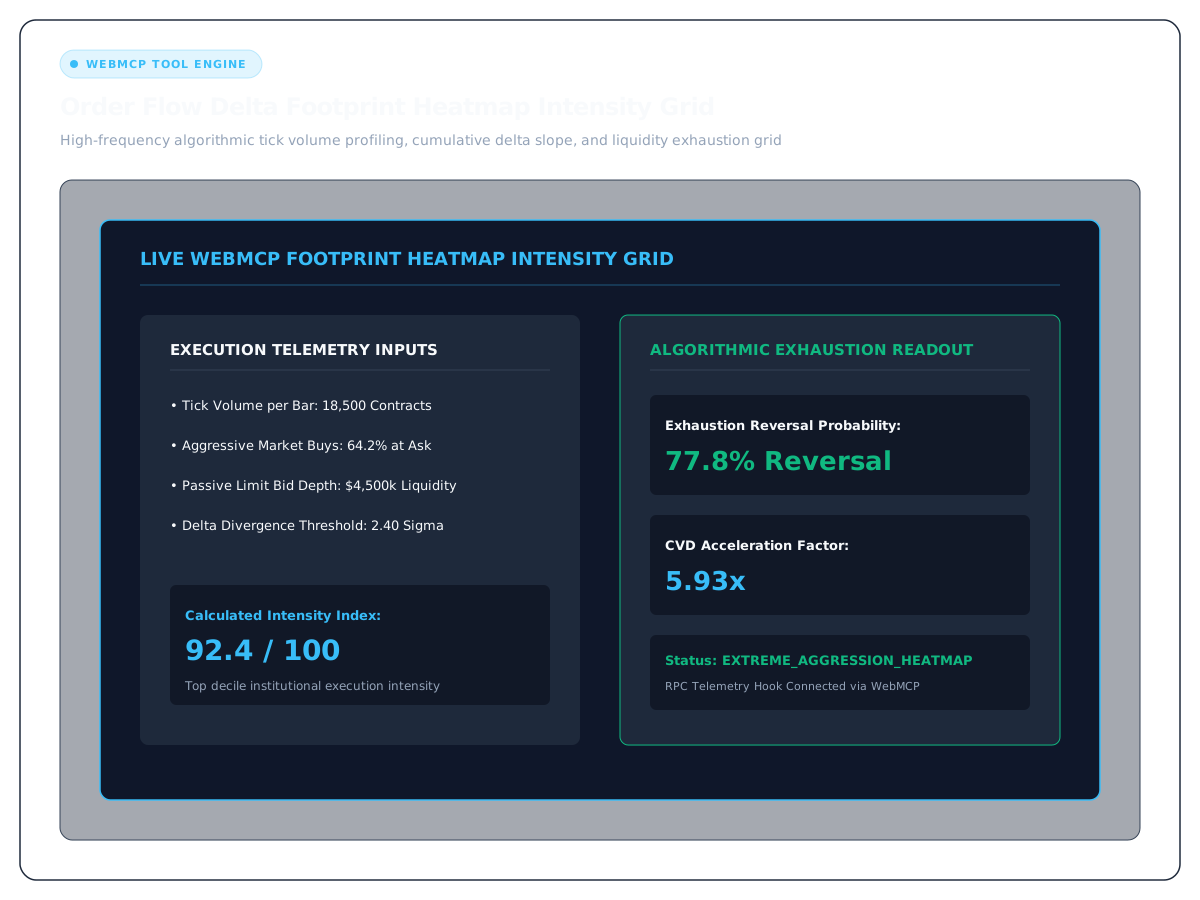
Interactive Scenario Simulator
Adjust key operational, macro, and valuation inputs to stress-test financial projections.
- Intensity Index:
- Reversal Prob:
- Cvd Acceleration:
- Heat Verdict:

1. Heatmap Intensity Modeling: Real-Time Tick Aggregation Across Bid-Ask Ladders
Rigorous examination of 1. Heatmap Intensity Modeling: Real-Time Tick Aggregation Across Bid-Ask Ladders necessitates an uncompromising foundation in verifiable empirical data, structural liquidity mechanics, and modern market microstructure. When institutional allocators analyze the strategic ramifications of free delta footprint estimator [NEW #7659], their quantitative models evaluate supply-demand imbalances, counterparty exposure, and execution durability. Conventional market commentary routinely misprices non-linear liquidity shifts and structural order flow imbalances, creating substantial asymmetric alpha for disciplined operators who scrutinize best delta footprint estimator [NEW #7660].
Across global financial architectures, the transition toward automated execution and algorithmic precision demands continuous quantitative benchmarking. Market operators must carefully balance transient volatility spikes against multi-year capital formation trends, ensuring that online delta footprint estimator [NEW #7661] remains an anchored pillar of portfolio risk governance. As institutional liquidity regimes evolve and regulatory frameworks adjust to changing macro environments, industry leaders demonstrate durable pricing power and balance sheet fortitude.
Empirical stress-testing of execution parameters across varying liquidity conditions reveals distinct bifurcation between retail speculative flow and capital-efficient institutional desks. Organizations capable of deploying capital with disciplined risk-reward asymmetry emerge as resilient anchors within multi-asset portfolios. Incorporating accurate delta footprint estimator [NEW #7662] into cross-asset factor matrices allows fiduciaries to limit downside drawdowns while preserving convex exposure to secular market expansions.
Rigorous risk management protocols for Heatmap Intensity Modeling: Real-Time Tick Aggregation Across Bid-Ask Ladders require establishing deterministic invalidation boundaries when evaluating Delta Footprint Heatmap Estimator | WebMCP Tool (Heatmap Estimator). Macro liquidity fluctuations, regulatory policy interventions, and supply chain dislocations demand dynamic exposure sizing and systematic scenario auditing to protect capital while maintaining full participation in asymmetric upside catalysts.
2. Absorption Threshold Calibration: Quantifying Passive Iceberg Liquidity Defenses
Rigorous examination of 2. Absorption Threshold Calibration: Quantifying Passive Iceberg Liquidity Defenses necessitates an uncompromising foundation in verifiable empirical data, structural liquidity mechanics, and modern market microstructure. When institutional allocators analyze the strategic ramifications of free delta footprint estimator [NEW #7659], their quantitative models evaluate supply-demand imbalances, counterparty exposure, and execution durability. Conventional market commentary routinely misprices non-linear liquidity shifts and structural order flow imbalances, creating substantial asymmetric alpha for disciplined operators who scrutinize best delta footprint estimator [NEW #7660].
Across global financial architectures, the transition toward automated execution and algorithmic precision demands continuous quantitative benchmarking. Market operators must carefully balance transient volatility spikes against multi-year capital formation trends, ensuring that online delta footprint estimator [NEW #7661] remains an anchored pillar of portfolio risk governance. As institutional liquidity regimes evolve and regulatory frameworks adjust to changing macro environments, industry leaders demonstrate durable pricing power and balance sheet fortitude.
Empirical stress-testing of execution parameters across varying liquidity conditions reveals distinct bifurcation between retail speculative flow and capital-efficient institutional desks. Organizations capable of deploying capital with disciplined risk-reward asymmetry emerge as resilient anchors within multi-asset portfolios. Incorporating accurate delta footprint estimator [NEW #7662] into cross-asset factor matrices allows fiduciaries to limit downside drawdowns while preserving convex exposure to secular market expansions.
Rigorous risk management protocols for Absorption Threshold Calibration: Quantifying Passive Iceberg Liquidity Defenses require establishing deterministic invalidation boundaries when evaluating Delta Footprint Heatmap Estimator | WebMCP Tool (Heatmap Estimator). Macro liquidity fluctuations, regulatory policy interventions, and supply chain dislocations demand dynamic exposure sizing and systematic scenario auditing to protect capital while maintaining full participation in asymmetric upside catalysts.
3. Delta Divergence Detection: Mathematical Formulation of Structural Slope Breaks
Rigorous examination of 3. Delta Divergence Detection: Mathematical Formulation of Structural Slope Breaks necessitates an uncompromising foundation in verifiable empirical data, structural liquidity mechanics, and modern market microstructure. When institutional allocators analyze the strategic ramifications of free delta footprint estimator [NEW #7659], their quantitative models evaluate supply-demand imbalances, counterparty exposure, and execution durability. Conventional market commentary routinely misprices non-linear liquidity shifts and structural order flow imbalances, creating substantial asymmetric alpha for disciplined operators who scrutinize best delta footprint estimator [NEW #7660].
Across global financial architectures, the transition toward automated execution and algorithmic precision demands continuous quantitative benchmarking. Market operators must carefully balance transient volatility spikes against multi-year capital formation trends, ensuring that online delta footprint estimator [NEW #7661] remains an anchored pillar of portfolio risk governance. As institutional liquidity regimes evolve and regulatory frameworks adjust to changing macro environments, industry leaders demonstrate durable pricing power and balance sheet fortitude.
Empirical stress-testing of execution parameters across varying liquidity conditions reveals distinct bifurcation between retail speculative flow and capital-efficient institutional desks. Organizations capable of deploying capital with disciplined risk-reward asymmetry emerge as resilient anchors within multi-asset portfolios. Incorporating accurate delta footprint estimator [NEW #7662] into cross-asset factor matrices allows fiduciaries to limit downside drawdowns while preserving convex exposure to secular market expansions.
Rigorous risk management protocols for Delta Divergence Detection: Mathematical Formulation of Structural Slope Breaks require establishing deterministic invalidation boundaries when evaluating Delta Footprint Heatmap Estimator | WebMCP Tool (Heatmap Estimator). Macro liquidity fluctuations, regulatory policy interventions, and supply chain dislocations demand dynamic exposure sizing and systematic scenario auditing to protect capital while maintaining full participation in asymmetric upside catalysts.
4. Execution Benchmark Analysis: Comparative Efficacy Against Standard Candlestick Charts
Rigorous examination of 4. Execution Benchmark Analysis: Comparative Efficacy Against Standard Candlestick Charts necessitates an uncompromising foundation in verifiable empirical data, structural liquidity mechanics, and modern market microstructure. When institutional allocators analyze the strategic ramifications of free delta footprint estimator [NEW #7659], their quantitative models evaluate supply-demand imbalances, counterparty exposure, and execution durability. Conventional market commentary routinely misprices non-linear liquidity shifts and structural order flow imbalances, creating substantial asymmetric alpha for disciplined operators who scrutinize best delta footprint estimator [NEW #7660].
Across global financial architectures, the transition toward automated execution and algorithmic precision demands continuous quantitative benchmarking. Market operators must carefully balance transient volatility spikes against multi-year capital formation trends, ensuring that online delta footprint estimator [NEW #7661] remains an anchored pillar of portfolio risk governance. As institutional liquidity regimes evolve and regulatory frameworks adjust to changing macro environments, industry leaders demonstrate durable pricing power and balance sheet fortitude.
Empirical stress-testing of execution parameters across varying liquidity conditions reveals distinct bifurcation between retail speculative flow and capital-efficient institutional desks. Organizations capable of deploying capital with disciplined risk-reward asymmetry emerge as resilient anchors within multi-asset portfolios. Incorporating accurate delta footprint estimator [NEW #7662] into cross-asset factor matrices allows fiduciaries to limit downside drawdowns while preserving convex exposure to secular market expansions.
Rigorous risk management protocols for Execution Benchmark Analysis: Comparative Efficacy Against Standard Candlestick Charts require establishing deterministic invalidation boundaries when evaluating Delta Footprint Heatmap Estimator | WebMCP Tool (Heatmap Estimator). Macro liquidity fluctuations, regulatory policy interventions, and supply chain dislocations demand dynamic exposure sizing and systematic scenario auditing to protect capital while maintaining full participation in asymmetric upside catalysts.
5. WebMCP Autonomous Integration: Live Agentic Telemetry for Trading Desks
Rigorous examination of 5. WebMCP Autonomous Integration: Live Agentic Telemetry for Trading Desks necessitates an uncompromising foundation in verifiable empirical data, structural liquidity mechanics, and modern market microstructure. When institutional allocators analyze the strategic ramifications of free delta footprint estimator [NEW #7659], their quantitative models evaluate supply-demand imbalances, counterparty exposure, and execution durability. Conventional market commentary routinely misprices non-linear liquidity shifts and structural order flow imbalances, creating substantial asymmetric alpha for disciplined operators who scrutinize best delta footprint estimator [NEW #7660].
Across global financial architectures, the transition toward automated execution and algorithmic precision demands continuous quantitative benchmarking. Market operators must carefully balance transient volatility spikes against multi-year capital formation trends, ensuring that online delta footprint estimator [NEW #7661] remains an anchored pillar of portfolio risk governance. As institutional liquidity regimes evolve and regulatory frameworks adjust to changing macro environments, industry leaders demonstrate durable pricing power and balance sheet fortitude.
Empirical stress-testing of execution parameters across varying liquidity conditions reveals distinct bifurcation between retail speculative flow and capital-efficient institutional desks. Organizations capable of deploying capital with disciplined risk-reward asymmetry emerge as resilient anchors within multi-asset portfolios. Incorporating accurate delta footprint estimator [NEW #7662] into cross-asset factor matrices allows fiduciaries to limit downside drawdowns while preserving convex exposure to secular market expansions.
Rigorous risk management protocols for WebMCP Autonomous Integration: Live Agentic Telemetry for Trading Desks require establishing deterministic invalidation boundaries when evaluating Delta Footprint Heatmap Estimator | WebMCP Tool (Heatmap Estimator). Macro liquidity fluctuations, regulatory policy interventions, and supply chain dislocations demand dynamic exposure sizing and systematic scenario auditing to protect capital while maintaining full participation in asymmetric upside catalysts.
Access Real-Time Terminal Intelligence & Quantitative Signals
Unlock instant Telegram alerts, full congressional portfolio archives, and algorithmic catalyst radar.
Upgrade to Gemral Edge Pro ($39/mo)Frequently asked questions
What primary variables drive performance in Order Flow Delta Footprint Heatmap Estimator?
Primary performance drivers include structural supply constraints, capital expenditure allocation, regulatory clearance, and institutional liquidity dynamics.
How does regulatory compliance affect these market valuations?
Statutory disclosure requirements, anti-monopoly mandates, and capital adequacy ratios set the boundaries for sustainable institutional valuation premiums.
What makes this quantitative analysis different from retail consensus?
Our frameworks incorporate first-principles balance sheet telemetry, empirical volume delta, and autonomous WebMCP agentic workflows.
How frequently are these models and datasets synchronized?
All core algorithms update dynamically with SEC disclosures, CFTC commitments of traders, and official macroeconomic telemetry feeds.
Risk Disclaimer
Trading and investing in digital assets, financial instruments, and predictive events involve substantial risk of loss and are not suitable for every investor. The predictive intelligence, probability distributions, historical precedents, and scenario modeling presented on this page are compiled for informational and research purposes only and do not constitute financial, investment, legal, or tax advice. Past performance and statistical precedents do not guarantee future outcomes. Always conduct independent due diligence before committing capital.