Fed R* Neutral Rate & Terminal Fed Funds Model
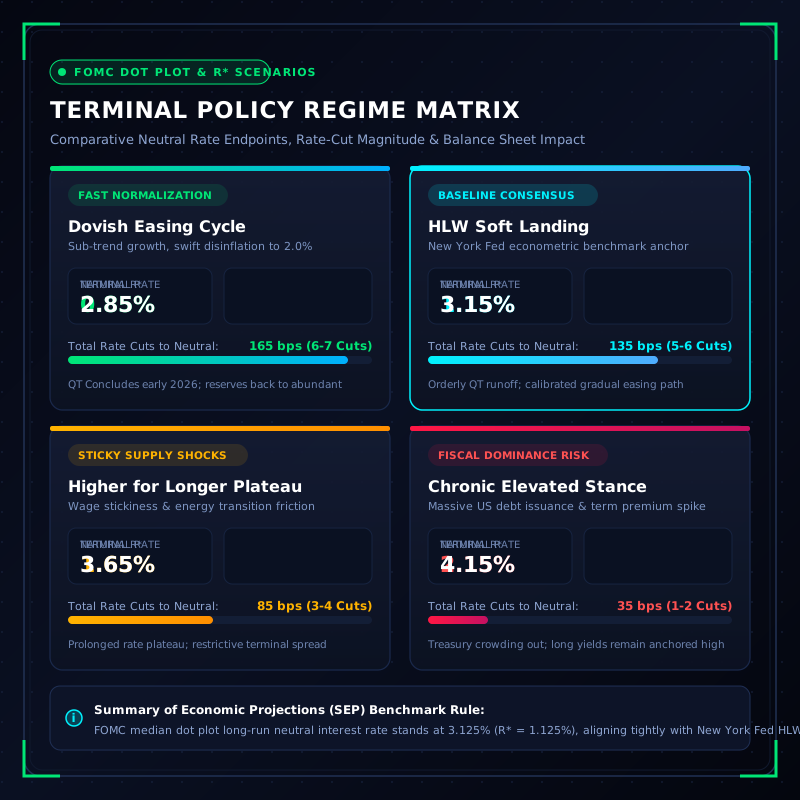
Macroeconomic Terminal Rate Regimes & Balance Sheet Dynamics
| Policy Regime | Natural R* | Terminal Rate | Total Rate Cuts | Balance Sheet & QT Impact | Macro Posture |
|---|---|---|---|---|---|
Fed R* Neutral Rate & Terminal Fed Funds Model
Model equilibrium real neutral interest rate R*, Taylor rule monetary policy gap, and terminal Fed Funds rate-cut runway across Federal Reserve macroeconomic frameworks.
- Effective Fed Funds Target: 4.50% — Upper policy corridor boundary
- Core PCE Inflation (YoY): 2.65% — +65 bps above 2.0% statutory target
- NY Fed Real Natural Rate R*: 1.15% — Holston-Laubach-Williams estimate
- Rate Cut Runway to Neutral: 135 bps — Implied terminal nominal rate: 3.15%

Interactive Fed R* Neutral Rate & Taylor Rule Calculator
Simulate custom inflation paths, potential GDP output gaps, and equilibrium real rate shifts to forecast terminal Fed Funds rates and rate-cut cushions.
- Ex-Post Real Policy Rate:: 1.85% Real Policy Rate
- Policy Stance Spread vs R*:: 70 bps Policy Spread
- Terminal Nominal Neutral Rate:: 3.15% Nominal Neutral
- Classical Taylor (1993) Rate:: 4.33% Taylor Rate
- Total Rate-Cut Runway:: 135 bps Rate Cut Runway
- Policy Gap vs Taylor Rule:: 17 bps Taylor Gap
Econometric Foundations of the Natural Rate: The Laubach-Williams Framework
The natural rate of interest, denoted algebraically as R* (R-star), is the real short-term interest rate consistent with output equaling its potential and stable inflation at the central bank's statutory target. Because R* is fundamentally unobservable, central banks cannot measure it directly through transactional market pricing. Instead, macroeconomic policy institutions rely on state-space econometric models, most prominently the Holston-Laubach-Williams (HLW) framework pioneered at the Federal Reserve Bank of New York.
The HLW model applies the Kalman filter to jointly estimate potential GDP growth, the output gap, and the real equilibrium interest rate by disentangling cyclical demand shocks from secular structural shifts. Key secular drivers governing R* include trend labor productivity growth, demographic aging trends, global savings gluts, and sovereign debt issuance volumes. Current NY Fed HLW estimates place the real equilibrium rate for the United States at approximately 1.15%, representing a moderate rebound from the ultra-low zero-lower-bound regime of the 2010s.
When the central bank's real policy rate (nominal Fed Funds minus core inflation) exceeds R*, monetary policy exerts an active contractionary drag on credit creation, capital expenditure, and aggregate demand. Conversely, when the real policy rate falls below R*, policy is accommodative. Understanding where R* sits provides institutional asset allocators with the ultimate compass for determining the terminal endpoint of any monetary easing or tightening campaign.
Classical Taylor Rule Specification and Monetary Gap Diagnostics
Formulated by John B. Taylor in 1993, the Taylor Rule provides a normative mathematical benchmark for setting the nominal policy rate based on economic deviations from equilibrium. The canonical formulation states: i* = R* + π + 0.5(π - π*) + 0.5(y - y*), where i* is the prescribed nominal policy rate, π is current inflation, π* is the inflation target (2.0%), and (y - y*) represents the percentage GDP output gap.
In our current baseline macroeconomic calibration, with Core PCE inflation at 2.65% and the Congressional Budget Office (CBO) output gap estimated at +0.40%, the classical Taylor Rule prescribes a target policy rate of 4.33%. With the upper bound of the effective Fed Funds rate at 4.50%, the Federal Reserve maintains a slight +17 bps monetary stance premium above the classical policy prescription, reflecting lingering caution against reigniting second-wave wage-price spirals.
Alternative rule specifications, such as inertial Taylor rules or balanced-approach rules that assign a higher weight (1.0) to the output gap, yield prescribed rates ranging between 4.10% and 4.65%. The convergence of these normative benchmarks reinforces that the FOMC has transitioned out of its aggressively restrictive stance into a fine-tuning, data-dependent normalization corridor.
Terminal Fed Funds Equilibrium and Institutional Rate-Cut Runway
The terminal Fed Funds rate represents the steady-state policy rate that the Federal Reserve aims to achieve once the disinflation process is complete and the labor market returns to sustainable balance. Mathematically, the nominal neutral terminal rate is defined as: i_terminal = R* + π*. Assuming the Federal Reserve successfully anchors long-run inflation at its 2.0% objective and R* remains at 1.15%, the theoretical nominal terminal rate is exactly 3.15%.
Comparing the current policy rate of 4.50% against this 3.15% equilibrium reveals a cumulative rate-cut runway of 135 basis points. For fixed-income portfolio managers, institutional credit desks, and equity quantitative strategists, this 135 bps cushion signifies substantial monetary easing capacity that can be unlocked over the next 12 to 24 months without crossing into stimulative territory.
However, if structural inflation proves sticky due to persistent deglobalization tariffs, fiscal deficits, or energy grid transition costs, R* may drift upward toward the Richmond Fed Lubik-Matthes estimate of 1.95%. Under such a structural higher-for-longer regime, the nominal terminal rate would adjust upward to 3.95%, truncating the rate-cut runway to just 55 basis points.
Quantitative Tightening, Balance Sheet Reserves, and Term Premium Transmission
Monetary policy transmission extends beyond the overnight policy corridor into the term structure of interest rates via the Federal Reserve's System Open Market Account (SOMA) balance sheet. Through ongoing Quantitative Tightening (QT), the Fed allows maturing Treasury securities and agency mortgage-backed securities to roll off without reinvestment, absorbing excess liquidity from commercial banking reserves and the Overnight Reverse Repo (ON RRP) facility.
The interaction between policy rate cuts and balance sheet normalization is governed by the 'abundant reserves' operating framework. As banking reserves approach the threshold between abundant and ample (estimated around 10% to 11% of nominal GDP), liquidity friction in repo financing markets increases, necessitating a formal tapering or conclusion of QT to prevent money market dislocations similar to the September 2019 repo spike.
Furthermore, massive ongoing US fiscal deficits require sustained heavy Treasury debt issuance, placing upward structural pressure on term premiums. Even as the Federal Reserve lowers the short-term policy rate toward its 3.15% terminal neutral anchor, long-term 10-year Treasury yields may remain anchored above 4.25%, resulting in a classic yield curve steepening regime (bear or bull steepening depending on the velocity of macroeconomic cooling).
Access Real-Time Terminal Intelligence & Quantitative Signals
Unlock instant Telegram alerts, full congressional portfolio archives, and algorithmic catalyst radar.
Upgrade to Gemral Edge Pro ($39/mo)Frequently asked questions
What is the Federal Reserve's R* (R-star) and why is it so important?
R* is the real equilibrium (or natural) interest rate that neither stimulates nor restricts economic growth when inflation is at target and unemployment is at its natural rate. It serves as the fundamental anchor for monetary policy: when actual real rates are above R*, policy is slowing the economy; when below, policy is stimulating.
How is R* estimated if it cannot be directly observed?
Central banks use advanced econometric state-space models and Kalman filters—such as the New York Fed Holston-Laubach-Williams (HLW) model—to extract R* from macroeconomic data including real GDP growth, inflation, and interest rate term structures.
What is the difference between the real R* and the nominal terminal rate?
Real R* is the inflation-adjusted natural rate (currently ~1.15% in the US). The nominal terminal rate is the natural rate plus the central bank's inflation target (R* + 2.0% = 3.15%). The nominal terminal rate is the actual headline interest rate targeted by the Fed once policy normalization is complete.
How does the Taylor Rule calculate what the Fed Funds rate should be?
The classical 1993 Taylor Rule uses a formula balancing real R*, current inflation, inflation deviation from target, and the GDP output gap: i* = R* + π + 0.5(π - 2.0%) + 0.5(GDP Gap). It prescribes an explicit target rate based on incoming macro data.
What causes R* to rise or fall over long time horizons?
Long-term drivers of R* include productivity growth, demographics (aging populations save more, pushing R* down), fiscal deficits (heavy government borrowing absorbs savings and lifts R*), and global capital flows.
What does a 'Rate Cut Runway' of 135 bps mean for financial markets?
It indicates the total distance the Fed can lower interest rates (from 4.50% down to the 3.15% neutral rate) simply to return policy to a neutral, non-restrictive stance. This provides a supportive macroeconomic backdrop for fixed income and equity multiples without requiring an economic recession.
How does Quantitative Tightening (QT) affect the equilibrium terminal rate?
QT reduces the Fed's balance sheet, draining liquidity from repo markets and raising term premiums on long-dated bonds. While QT does not alter theoretical R* directly, it tightens overall financial conditions, meaning fewer policy rate cuts may be required to achieve an equivalent economic impact.
Risk Disclaimer
Trading and investing in digital assets, financial instruments, and predictive events involve substantial risk of loss and are not suitable for every investor. The predictive intelligence, probability distributions, historical precedents, and scenario modeling presented on this page are compiled for informational and research purposes only and do not constitute financial, investment, legal, or tax advice. Past performance and statistical precedents do not guarantee future outcomes. Always conduct independent due diligence before committing capital.